The gen alpha daily zeitgeist of the physical commodity world
Oil · Gas · NGLs · Power · Coal · Ags · Metals · Fertilizers · Rare Earths · Shipping · Environment · RWA · Podcast · Kickers · Archive
Friday, November 6, 2026
Prefer audio only? Listen here.
Prefer longer? Listen to the 7-minute version.
Markets at a glance
Charts: grey is the prior session, color is today.
Macro
|
S&P 500 Fut
7,398
+0.2%
+15 |
Dollar Index
102.02
+0.5%
+0.47 |
EUR/USD
1.1176
-0.4%
-0.0042 |
US 10Y Yield
4.837
-5.7 bp
|
Last price as of Fri, Nov 6, 5:34 AM ET. Click price for news.
Downey's Take
Crude was quiet today. Brent settled at $97.76 and WTI at $90.24, with the Brent-WTI spread at $7.52.
Propane up $0.055 (+5.1%) on easing Middle East de-escalation hopes after US midterms supporting expectations of restored flows.
Ethane down $0.014 (-4.4%).
Dutch TTF European nat gas down $3.26 (-3.6%) on hopes for quicker Iran deal recovery in LNG flows through Hormuz following Democratic midterm gains.
Tin down $1152 (-2.4%) on hawkish Fed remarks and weak tech stocks weighing on AI-related demand.
Palladium down $25 (-2.4%) on broader risk-off sentiment and profit-taking after recent rebound.
Kicker: Saxo Bank sees gold consolidating after a strong short-covering rally, with support above USD 3,975 (Saxo Bank, Nov 6).
Propane up $0.055 (+5.1%) on easing Middle East de-escalation hopes after US midterms supporting expectations of restored flows.
Ethane down $0.014 (-4.4%).
Dutch TTF European nat gas down $3.26 (-3.6%) on hopes for quicker Iran deal recovery in LNG flows through Hormuz following Democratic midterm gains.
Tin down $1152 (-2.4%) on hawkish Fed remarks and weak tech stocks weighing on AI-related demand.
Palladium down $25 (-2.4%) on broader risk-off sentiment and profit-taking after recent rebound.
Kicker: Saxo Bank sees gold consolidating after a strong short-covering rally, with support above USD 3,975 (Saxo Bank, Nov 6).
Drivers and the Kicker house view are sourced from third-party news and bank or desk commentary. Informational only, not trade advice. Past Kickers by commodity and house →
The marquee commodity stories of the day
Oil Slumps as Supply Glut Emerges Post-Midterms
Bloomberg · Thu, Nov 5, 2026
Oil prices have sharply declined as geopolitical concerns ebb after the Democratic midterm sweep, demonstrating that physical supplies are comfortable behind fears over Middle Eastern flows. Brent futures slumped this week as President Donald Trump signaled he wouldn’t immediately resume hostilities against Iran, with the global benchmark tumbling almost 20% and trading near $97 a barrel in London. Read →
Oil Rebounds After Post-Election Selloff
Anthony Harrup · Wall Street Journal · Thu, Nov 5, 2026
Oil futures rebounded from the previous session’s heavy losses while the market maintains hopes for a U.S.-Iran agreement following the midterm elections. WTI rose 2.7% to $90.52 a barrel and Brent gained 3.9% to $98.29 a barrel, though signals from Washington remain mixed and no concrete diplomatic agreement has emerged. Read →
Trump Russia Diesel Deal Unravels Amid Shortage
Financial Times · Wed, Nov 4, 2026
Two Russian diesel tankers bound for the US changed course in a setback to the White House gambit to lower fuel prices and shore up political support after the midterm losses. US diesel inventories fell below 100mn barrels for the first time in more than two decades, with the supply squeeze threatening to weigh further on the fuel. Read →
UK Warned on Critical Minerals China Dependence
Financial Times · Wed, Nov 5, 2026
A UK parliamentary committee warned that Britain remains dangerously exposed due to failure to diversify critical minerals supplies from China. Committee chair Liam Byrne said the lack of diversification continues to pose significant risks to the country’s future security. Read →
Oil Heads for Sharp Weekly Drop Despite Floor
Reuters · Fri, Nov 6, 2026
Oil prices are set for a sharp weekly drop on expectations of a de-escalation of the Iran war after US President Donald Trump’s party suffered election losses, but Middle East supply concerns from the conflict continue to provide a floor for the market. Brent is on track to drop by 12% this week while WTI is set to drop 12.1%. Read →
Most clicked yesterday
In this issue · tap a section to jump to it
Oil 3US Nat Gas 4NGL/LPG & Petchems 2Global Nat Gas & LNG 3Power 3Coal 3Agriculture 4Fertilizers 3Base Metals 3Iron Ore & Steel 4Precious Metals 1Rare Earths & Critical Minerals 2Shipping & Freight 2Environment 2On-Chain Commodities 1Corporate & Deals 3Regulation & Government 3Social buzz 5Podcasts 3Prediction Markets
Markets News
| Oil | Oil 101 |
What's moving · Oil prices swing sharply on US midterm-driven de-escalation hopes and fresh tanker attacks in Gulf/Hormuz.
Cash WTI 93.64 -0.42 | Cash Brent 94.64 -0.82 | Cash Br–TI 1.00 -0.40 |
Physical cash prices from Prism.
| Futures | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| WTI Crude Dec 2026 |
90.24 | -0.3% -0.28 |
+57.1% | +51.0% | +10.1% |
| Brent Jan 2027 |
97.76 | -0.5% -0.53 |
+60.7% | +53.6% | +17.2% |
| RBOB Gasoline Dec 2026 |
2.750 | -0.5% -0.013 |
+61.3% | +41.7% | +18.4% |
| Heating Oil Dec 2026 |
4.340 | -0.3% -0.012 |
+105% | +74.8% | +75.9% |
| RBOB Crk $/bbl |
25.27 | -1.1% -0.27 |
+78.1% +11.08 |
+16.3% +3.55 |
+62.2% +9.69 |
| NY HO Crk $/bbl |
92.04 | -0.2% -0.22 |
+191% +60.41 |
+107% +47.56 |
+325% +70.37 |
| NY 321 Crack $/bbl |
47.52 | -0.5% -0.26 |
+138% +27.52 |
+62.2% +18.22 |
+170% +29.92 |
Oil prices stay below $100 as traders weigh Iran diplomacy and supply outlook
Farhan Rafid and Anthony Harrup · Wall Street Journal · Thu, Nov 5, 2026
Front-month Brent settled up 3.9% at $98.29 a barrel and WTI rose 2.7% to $90.52 after the prior session’s steep losses. Traders assessed US-Iran relations post-midterms and recovering Middle East oil supplies. The session extended volatility with prices swinging in a wide range amid mixed diplomatic signals. Read →
Brent set for biggest weekly loss since 2020 on war hopes
Bloomberg · Thu, Nov 5, 2026
Brent traded near $99 a barrel on Friday, rebounding from Wednesday’s nearly 9% drop but still down about 16% for the week. Investors weighed prospects for ending the Iran conflict after Democrats swept US midterms. Citi strategist Scott Chronert noted the sudden price drop surprised markets. Read →
Oil declines on signs of moves toward Gulf war de-escalation
Bloomberg · Fri, Nov 6, 2026
Brent traded below $98 a barrel after Qatar’s Emir discussed de-escalation efforts with President Trump by phone. The call fueled hopes for improved energy flows from the Middle East. Prices erased earlier gains in a session extending the week’s $19 range volatility. Read →
Charts of the dayPG crude oil loadings map Nov 5 2026via @LVision_Trading on X · 69 likesMap and table showing 12+ mbd loadings with every Iraqi location occupied, key for Hormuz flows and Iraq production

Germany gas storage levels chartvia @energy_charts_d

Suez Canal container traffic recovery 2026via @JavierBlas

Check out Oil 101.
| US Natural Gas | NatGas 101 |
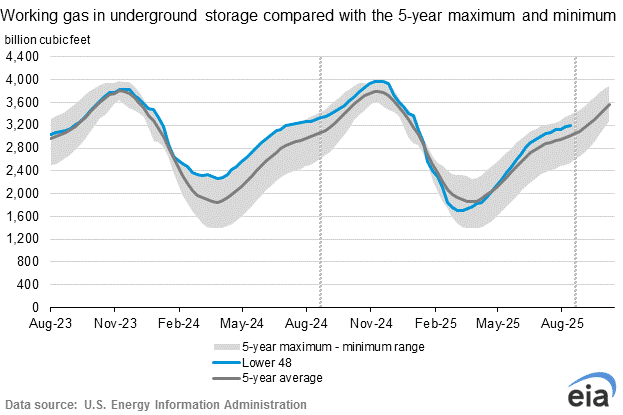
What's moving · EIA's 77 Bcf storage build missed estimates, widening surplus to 54 Bcf above five-year average amid mild weather.
| Futures | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Henry Hub Dec 2026 |
2.999 | +1.8% +0.052 |
-18.6% | -30.5% | -44.7% |
EIA gas storage · week ending Fri, Oct 30
A 77 Bcf injection took working gas to 3,801 Bcf, 54 Bcf (1%) above the five-year average and 109 Bcf below a year ago.
Working gas 3,801 Bcf +77 Bcf w/w | Year ago 3,910 Bcf | 5-yr avg 3,747 Bcf |
Consensus – this week | Year-ago chg +33 Bcf | 5-yr avg chg +70 Bcf |
Source: EIA Weekly Natural Gas Storage Report · Full EIA report →
EIA storage rises 77 Bcf, beating year-ago but widening surplus.
Anthony Harrup · Wall Street Journal · Thu, Nov 5, 2026
The EIA reported a 77 Bcf injection for the week ended Oct. 30, lifting inventories to 3,801 Bcf, 54 Bcf above the 2021 to 2025 average and 109 Bcf below year-ago levels. Analysts expected an 81 Bcf build. Mild weather kept demand low, with more builds likely into November as injection season extends. Read →
Natgas prices climb above $2.98 on smaller storage build.
Agna Gabriel · Trading Economics · Thu, Nov 5, 2026
Prices rose for a third session after the EIA's 77 Bcf build missed the 81 Bcf forecast. Lower 48 output averaged 111.2 Bcf/d in early November, down from October's 113.4 Bcf/d. LNG feedgas eased to 18.2 Bcf/d but global demand stays firm despite geopolitical supply risks. Read →
Futures drift as storage build, output and LNG data clash with warm outlook.
Andrew Baker · Natural Gas Intelligence · Thu, Nov 5, 2026
December futures held near $2.97/MMBtu midday as the 77 Bcf storage print, falling production and rebounding LNG feedgas offset forecasts for above-normal temperatures through mid-November. Output trends lower while LNG demand provides support. Read →
Permian producers restart wells after securing pipeline capacity.
Shale Mag · Wed, Nov 5, 2026
Permian Resources restarted high gas-to-oil wells curtailed in Q2 due to negative Waha prices once new firm transport deals took effect. Q3 gas output jumped 42% sequentially to 787 MMcf/d. EIA expects Texas to drive most 2026 to 2027 US pipeline additions to ease basin constraints. Read →
Check out NatGas 101.
Sponsored · Kpler
How much oil is moving, in real time
With Hormuz and the Red Sea redrawing trade routes minute by minute, you need the quickest, most reliable source of truth. Kpler tracks commodity cargoes and the vessels carrying them. You can see exports, imports, floating storage and more as they develop in real time.
Kpler covers oil, products, gas, and dry bulk. Pair flows with refinery runs, inventories and freight analytics, and the story behind a price move becomes visible before the market has priced it in.
| Wet Gas, NGLs/LPGs & Petchems | Commodities 101 |
What's moving · Propane jumps 5.1% to 113.3¢/gal at Mont Belvieu as exports and winter demand erase surplus.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Ethane C2 $/gal |
0.300 | -4.4% -0.014 |
+26.5% | +11.8% | -29.8% |
| Propane C3 $/gal |
1.133 | +5.1% +0.055 |
+83.6% | +81.9% | -17.6% |
| N-Butane NC4 $/gal |
1.857 | +1.9% +0.035 |
+149% | +120% | +16.7% |
| Isobutane IC4 $/gal |
1.853 | +1.1% +0.020 |
+138% | +113% | +16.5% |
| Pentane C5 $/gal |
2.037 | +1.3% +0.026 |
+73.8% | +64.0% | +7.9% |
| Spread | Now | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| C2 Frac Sprd ¢/gal | 10 | -2 | +11 | +12 | +3 |
| C3 Frac Sprd ¢/gal | 86 | +5 | +58 | +63 | -2 |
| C2 vs NWE Naph $/mt | -617 | -34 | -313 | -285 | -196 |
| C3 vs NWE Naph $/mt | -259 | +5 | -93 | -44 | -223 |
| C5 as % WTI | 95 | +2 | +9 | +8 | -2 |
Mont Belvieu front-month settlement. Frac spread is the liquid over Henry Hub fuel value; naphtha spreads are before freight.
Targa advances Train 14 frac and starts Bull Run pipeline early
Energy News / Pipeline & Gas Journal · Fri, Nov 6, 2026
Targa announced it is moving forward with a new 150 Mb/d NGL fractionator (Train 14) at Mont Belvieu expected online in Q1 2029 and confirmed its Train 12 fractionator and Bull Run Extension residue gas pipeline started operations ahead of schedule in Q4 2026. The expansions respond to rising Permian NGL production and customer needs amid tight fractionation capacity at the hub. Additional long-lead items were ordered for Permian processing plants. Read →
Butane hits 30-year highs in Europe, 14-year high in US
Natalia Katona · OilPrice.com · Thu, Nov 4, 2026
Northwest Europe November butane reached $1,125/t, a 30-year high, while Asia AFEI hit $1,180/t and US Mont Belvieu $920/t, a 14-year high. Asia’s pull on US cargoes plus winter gasoline blending demand in Europe tightened global supply after Middle East disruptions shifted trade flows. High US prices and freight costs limit further US-to-Asia arbitrage. Read →
Check out Commodities 101: NGLs section.
| Global Nat Gas & LNG | NatGas 101 |
What's moving · TTF slips below €90/MWh on mild weather and LNG supply signals while JKM holds near $31.57/MMBtu amid Asia-Europe cargo competition.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Dutch TTF €/MWh |
87.42 | -3.6% -3.26 |
+207% | +177% | +9.3% |
| Dutch TTF $/MMBtu |
28.63 | -3.6% -1.07 |
+207% | +177% | +9.3% |
| JKM $/MMBtu |
31.57 | -0.2% -0.05 |
+229% | +184% | -1.8% |
EU gas storage · gas day Wed, Nov 4
EU gas storage is 73.8% full, 835 TWh in store, 16.0 points below the five-year average for this date and 9.3 points below a year ago. Germany, the bloc's largest store, is 60.3%. LNG terminals are 53.6% full and sent out 3,959 GWh, 2% more than the day before.
EU full 73.8% -0.32 pts d/d | Year ago 83.0% | 5-yr avg 89.8% same date |
Germany 60.3% |
Source: GIE AGSI+ and ALSI+ · Full AGSI+ data →
TTF trades near €89/MWh after intraday swings
OilPriceAPI / Tindex · Fri, Nov 6, morning ET
Dutch TTF front-month futures settled around €87.83, €89.04/MWh on November 6 after trading as low as €87.20 intraday, down from prior-session levels near €90. The move reflects milder European weather demand and steady LNG send-out into northwest Europe offsetting low storage at 73.8% full. Norwegian pipeline flows remain the dominant physical supply source while Russian volumes stay minimal. Read →
JKM holds at $31.57/MMBtu with minor daily dip
OilPriceAPI · Fri, Nov 6, morning ET
The Japan-Korea Marker spot benchmark sits at $31.57/MMBtu, little changed day-over-day after recent peaks above $32. Northeast Asian buyers continue competing for cargoes against European demand, keeping the TTF-JKM arbitrage spread supportive of diversions toward Asia when the differential favors it. Stable JKM levels signal sustained winter procurement interest from Japan, South Korea and China despite any early warm-weather signals. Read →
EU storage at 75% lags seasonal average sharply
ACER · Tue, Nov 3 (updated context Nov 5 to 6)
EU underground gas storage reached 75% of capacity by late October, roughly 15 percentage points below the five-year average and well short of the 90% target, with Germany and other central European sites showing the largest deficits. Slow summer refill driven by high prices and Middle East-related LNG disruptions leaves the bloc entering winter with a thinner buffer. This structural tightness underpins TTF support even as near-term weather and LNG flows allow modest price relief. Read →
Check out NatGas 101: LNG section.
| Power | Power 101 |
What's moving · ERCOT data-center interconnection pause and PJM capacity shortfall dominate power markets amid rising AI load.
Texas data center pause risks delaying 20% of US pipeline
Utility Dive · Thu, Nov 5, 2026
Texas Gov. Greg Abbott ordered an audit of data centers in ERCOT’s queue, pausing new 75 MW+ interconnections and delaying the Batch Zero study. The queue holds 474 GW of requests, 90% data centers, more than five times ERCOT’s record peak. BNEF warns the pause puts nearly 50 GW of projects at delay risk and could cut expected 2026 to 2027 additions to just 1.2 GW. Read →
ERCOT targets Dec. 10 completion of data center audit
Utility Dive · Thu, Nov 5, 2026
ERCOT plans to finish auditing 300 large data-center proposals by Dec. 10 to resume the Batch Zero process. The pause affects energization reviews and the grid operator’s long-term load forecast. Officials are also seeking RFI updates on medium loads totaling nearly 8.8 GW. Read →
Texas pauses data centers amid 474 GW queue
Utility Dive · Thu, Nov 5, 2026
Abbott directed ERCOT to audit data-center requests in the 474 GW large-load queue before processing new connections. ERCOT delayed its Batch Zero transmission study and will seek a timeline exemption from the PUCT. The Data Center Coalition said the review should separate responsible projects from speculative ones. Read →
Check out Power 101.
| Coal | Commodities 101 |
What's moving · Newcastle thermal coal holds near $144.50/t as China signals ample winter stocks and India import arrivals rebound.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| API2 Rotterdam $/t |
137.25 | -0.0% -0.05 |
+40.8% | +42.2% | -5.7% |
| Newcastle $/t |
144.80 | -0.1% -0.15 |
+36.9% | +25.4% | -5.5% |
China NDRC: winter energy supply sufficient for demand
sxcoal.com · Fri, Nov 6, 2026
China's National Development and Reform Commission stated that winter heating season energy supplies can meet demand, with September coal output at 385 million tonnes rising further in October and centrally dispatched power plant stocks exceeding 210 million tonnes as of end-October (36 days' coverage). Natural gas resources secured exceed 200 billion cubic metres with full storage. This eases immediate supply fears for the world's top coal consumer, supporting stable thermal coal demand and import flows into winter. Read →
India thermal coal imports rebound to 15.06 Mt in October
Argus Media · Thu, Oct 26, 2026
Kpler estimates Indian seaborne thermal coal arrivals reached 15.06 million tonnes in October, up 33% from September and the highest since May 2025, driven by record coal-fired generation, post-monsoon industrial demand, and depleted power-plant stocks at 19.7 to 19.93 million tonnes (about six days' use). Imports predominantly reflect late-September/early-October bookings despite multi-year high prices. This lifts seaborne demand for Indonesian and South African cargoes amid thin domestic supply. Read →
Indonesia thermal coal exports constrained by logistics, quotas
S&P Global / World Ports Organization · Fri, Nov 6, 2026
Indonesia's 2026 coal production is projected at 720 million tonnes, above the initial 600 million tonne target but below 2025 levels, with thermal exports potentially falling toward 445 million tonnes as regulatory approvals, domestic obligations and low river levels on Barito/Mahakam systems constrain seaborne volumes. Shipments in the first half fell 8% year-on-year; August exports dropped 25% year-on-year. This keeps Asian supply tight, supporting Newcastle and other benchmarks despite China's winter reassurance. Read →
Check out Commodities 101: coal section.
| Agriculture | Commodities 101 |
What's moving · Soybeans and corn firm on crude oil rally but head for weekly losses ahead of USDA report.
| Futures | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Corn Dec 2026 |
441 | +0.2% +1 |
+0.1% | +3.2% | -20.1% |
| Wheat Dec 2026 |
592 | -1.2% -7 |
+16.8% | +12.2% | -22.9% |
| Soybeans Jan 2027 |
1,190 | +0.2% +2 |
+15.5% | +8.0% | +1.0% |
| Sugar Mar 2027 |
18.39 | -0.9% -0.17 |
+22.5% | +30.4% | -7.7% |
| Coffee Dec 2026 |
276.9 | -0.1% -0.3 |
-20.6% | -32.1% | +38.7% |
| Cocoa Dec 2026 |
5,144 | -0.7% -37 |
-15.2% | -14.5% | +111% |
| Cotton Dec 2026 |
78.67 | -0.1% -0.04 |
+21.9% | +23.2% | -32.8% |
Soybeans, corn rise on oil but eye weekly losses
Reuters / Business Recorder · Fri, Nov 6, 2026
CBOT soybeans rose 0.3% to $11.92 to 1/4 a bushel and corn added 0.1% to $4.40 to 1/2 a bushel, supported by higher crude oil futures that boost biofuel demand. Wheat fell 0.3% on Black Sea export resumption hopes. Both soy and corn are on track for weekly declines amid ample global supplies, with the USDA crop update due next week. Read →
Soybeans fall 1% as exports drop sharply
Anthony Harrup and Paulo Trevisani · Dow Jones / Morningstar · Thu, Nov 5, 2026
January soybeans dropped 1% to $11.39 to 3/4 a bushel while December corn fell 0.8% to $4.40 to 3/4 a bushel. Weekly export sales hit the upper end of estimates with no flash sales, but soybean exports plunged 44% week-over-week. The soybean downtrend persists ahead of next week's USDA WASDE report. Read →
Corn, soybeans drop on harvest pressure
Ben Potter · Farm Futures / Farm Progress · Thu, Nov 5, 2026
December corn settled down 4.25 cents at $4.5450 and January soybeans fell 14 cents amid accelerating U.S. harvest. Export sales data showed solid weekly volumes, but seasonal supply pressure and record crop expectations dominated. Wheat posted modest gains of 0.75 to 3 cents. Read →
Grains trade lower ahead of USDA data
ADM Investor Services · Thu, Nov 5, 2026
Corn closed lower at session lows near $4.46 while soybeans fell 10 to 14 cents with oil at a fresh 7-month low. Export commitments remain below historical averages for corn. Traders focus on next week's USDA production and stocks reports amid ongoing harvest pressure. Read →
Check out Commodities 101: agriculture section.
| Fertilizers | Commodities 101 |
What's moving · Russia cuts fertilizer export quota to 18.8M tons Dec 2026-May 2027 amid domestic priorities.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Urea | |||||
| China (ZCE) CNY/t |
1,736 | +0.1% +1 |
-0.7% | +5.6% | -27.3% |
| Brazil CFR $/t |
467.50 | -0.3% -1.50 |
+14.7% | +15.0% | -44.0% |
| US Gulf FOB $/st |
425.25 | -0.2% -1.00 |
+10.0% | +9.4% | -43.4% |
| DAP | |||||
| NOLA FOB $/st |
795.00 | +0.0% +0.00 |
+27.2% | +8.5% | +9.3% |
The 5Y column starts from the October 2021 peak, when the European gas crisis shut ammonia plants and China halted urea exports. Daily settles; these contracts barely trade, so flat days are common.
Russia sets fertilizer export quota at 18.8M tons Dec-May.
Reuters · Fri, Nov 6, 2026
Russia's government set mineral fertilizer export quotas at 18.8 million tons for Dec 1 2026 to May 31 2027, down from 20M tons previously, with 11.3M tons nitrogen including 2.3M tons ammonium nitrate and 7.5M tons complex fertilizers. The measure prioritizes domestic farm and feed producers by maintaining internal supply levels. It applies outside the Eurasian Economic Union and excludes humanitarian or transit shipments. Read →
Nutrien reports Q3 earnings miss on sulfur costs, nitrogen weakness.
Reuters · Thu, Nov 5, 2026
Nutrien posted Q3 adjusted EPS of 61 cents, missing estimates of 80 cents, with net earnings at $288M as sulfur costs spiked phosphate margins and nitrogen volumes fell. Record potash sales volumes supported results while Brazilian farmers delayed nitrogen buys due to credit constraints; the firm will close its White Springs Florida phosphate mine in H1 2027 and has shut its Trinidad nitrogen plant over gas and port issues. U.S. fall applications are expected to rebound with better weather. Read →
CF Industries Q3 EPS misses on higher costs despite volume gains.
Zacks · Thu, Nov 5, 2026
CF Industries reported Q3 EPS of $2.87, missing consensus $2.93, with net sales up 12.1% to $1.86B on 6.5% higher volumes but offset by elevated purchased product, freight and maintenance costs. Ammonia and UAN segments showed margin gains from pricing and volume, while granular urea margins declined on lower realized prices. Full-year 2026 ammonia production guidance holds at 9.5M tons amid ongoing Yazoo City outage. Read →
Check out Commodities 101: fertilizer section.
| Base Metals | Commodities 101 |
What's moving · Copper falls to lowest since July as US election undercuts AI and tariff bulls.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Copper NY $/mt |
13,790 | -0.2% -33 |
+11.1% | +26.7% | +42.0% |
| Copper SHFE $/mt |
14,186 | -1.0% -144 |
+11.7% | +31.2% | +45.3% |
| Aluminium SHFE $/mt |
3,099 | +0.0% +1 |
+4.1% | +16.1% | +11.5% |
| Zinc SHFE $/mt |
3,376 | -0.7% -24 |
+12.4% | +21.0% | +1.1% |
| Nickel SHFE $/mt |
16,247 | +2.2% +348 |
-4.1% | +8.4% | -19.0% |
| Lead SHFE $/mt |
2,137 | +0.5% +10 |
-3.0% | -1.1% | -1.8% |
| Tin SHFE $/mt |
46,508 | -2.4% -1,152 |
+10.7% | +31.2% | +18.4% |
Copper slumps to July low on US election AI, tariff fears
Bloomberg News · Bloomberg · Fri, Nov 6, 1:26 AM ET
Copper fell as much as 1.5% toward $13,640 a ton on the LME after Democrats swept Congress, denting hopes for US tariffs on imports and sparking a selloff in AI-related tech stocks that support data-center demand for the metal. The move extended Thursday's 1.2% decline and marks the lowest level since July. Industrial metals broadly joined the risk-off move as investors reassess growth and demand outlooks. Read →
LME nickel jumps nearly 3% on Indonesia quota news
Shanghai Metals Market · Thu, Nov 5
LME nickel rose 3% to $15,875 per ton and SHFE nickel gained nearly 5% after Indonesia signaled tighter ore export quotas, lifting prices from a 10-month low. The move came alongside a weakening US dollar and follows earlier production-cut speculation by Chinese smelters in Indonesia. LME nickel inventories continued to drain, adding to bullish sentiment. Read →
LME tin drops over 3% as AI spending fears mount
Shanghai Metals Market · Fri, Nov 6
LME tin fell 3.23% to $45,479 per ton and SHFE tin dropped nearly 3% as concerns over slower AI infrastructure spending weighed on the metal used in electronics. Prices hit fresh lows not seen in months amid the post-election tech selloff. Low LME inventories continue to provide a floor despite softening demand sentiment. Read →
Check out Commodities 101: base metals section.
| Iron Ore & Steel | Commodities 101 |
What's moving · China equity rally and short-covering lift DCE iron ore to one-month high near 691 yuan/mt as steel margins improve slightly.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Iron Ore 62% DCE $/dmt |
91.2 | -0.5% -0.5 |
-9.4% | -7.0% | +5.1% |
| Rebar SHFE $/mt |
400 | +0.0% -0 |
+1.5% | +4.2% | -37.0% |
| HRC SHFE $/mt |
419 | +1.0% +4 |
+1.7% | +2.2% | -38.4% |
Iron ore hits 1-month high on China stock rally
Reuters · Thu, Nov 5, 2026
The most-traded DCE iron ore contract rose 1.55% to 689.5 yuan/mt, its strongest since early October, while SGX December contract climbed toward $92.65/t. A sharp rebound in Chinese equities lifted broader commodity sentiment and improved steel margins fueled expectations of higher hot metal output at mills. Rebar and hot-rolled coil futures also gained as coking coal and coke prices rebounded amid supply constraints. Read →
SGX iron ore up 3.6% on week as shorts cover
SMM · Fri, Nov 6, 2026
SGX most-traded iron ore contract rose from $90.24/mt to $93.50/mt over the week, with Thursday’s $1.80 gain driving most of the move; DCE I2701 closed at 691 yuan/mt, up 1.3%. 35 Chinese ports saw iron ore stocks build 1.08 million mt to 149.13 million mt despite lower arrivals, as hot metal output fell and mill losses deepened to 130+ yuan/mt on rebar. Follow-through hinges on a third coke price cut and hot metal recovery. Read →
ArcelorMittal beats profit view on EU steel curbs
Reuters · Thu, Nov 5, 2026
ArcelorMittal reported 3Q core EBITDA of $2.02 billion, beating estimates, as EU steel import curbs cut non-EU imports 50% and supported shipments; shares rose nearly 6%. All European blast furnaces are back online and flat shipments are expected to accelerate in 4Q. European HRC prices have risen 22% since January to €755/t amid the protections. Read →
China iron ore port stocks rise to 175.3 Mt
Mysteel · Fri, Nov 6, 2026
Imported iron ore inventories at 47 major Chinese ports rose 2.4 million tonnes or 1.4% week-on-week to 175.3 million tonnes as of Nov 5, the highest since late June. 35-port stocks added 1.08 million mt to 149.13 million mt with outbound volumes falling. The build reflects weaker mill offtake amid thin steel margins and seasonal demand softness. Read →
Check out Commodities 101: steel section.
| Precious Metals | Commodities 101 |
What's moving · Gold holds near $4,080/oz after post-midterm rebound as dollar and yields ease.
| Futures | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Gold Dec 2026 |
4,075 | -0.9% -39 |
-6.1% | +1.6% | +123% |
| Silver Dec 2026 |
51.94 | -0.8% -0.44 |
-25.9% | +8.2% | +112% |
| Platinum Jan 2027 |
1,518 | -0.3% -4 |
-25.4% | -1.4% | +43.4% |
| Palladium Dec 2026 |
1,020 | -2.4% -25 |
-37.4% | -27.0% | -50.9% |
Central banks bought 321 tonnes of gold in Q3, up 42% YoY.
Giulia Petroni · Dow Jones / Morningstar · Thu, Nov 5, 2026
The World Gold Council reported central banks added a net 321 tonnes in Q3 2026, the strongest quarterly total since Q4 2024 and 42% above the prior year. Year-to-date purchases reached 675 tonnes, 6% ahead of 2025. China and Poland led disclosed buying with 63t and 40t respectively, while unreported activity accounted for 63% of the quarter's demand. Read →
Check out Commodities 101: gold section.
| Rare Earths & Critical Minerals | Commodities 101 |
What's moving · European dysprosium and terbium spot prices surge 4 to 5% overnight to $3,300 to 4,200/kg and $7,300 to 8,300/kg amid shrinking inventories and China controls.
MP Materials posts Q3 revenue $147.7M, beats estimates, GM magnet qualification
MP Materials · Thu, Nov 5, 2026
MP Materials reported Q3 2026 consolidated revenue of $147.7 million, up 176% year-over-year, with NdPr production of 1,018 metric tons (+41% YoY) and sales of 1,020 metric tons (+94% YoY). The company completed General Motors magnet qualification, with saleable deliveries and revenue expected to begin in Q4; it also recorded $8.1 million in US government price protection agreement income and a $31.6 million SEG+ sale to a US aerospace/defense customer. Adjusted EBITDA swung to $41.1 million from a prior-year loss. Read →
America’s Rare Earth Reckoning Is Less Than 60 Days Away
Michael Scott · OilPrice.com · Thu, Nov 5, 2026
President Trump’s $12 billion Project Vault strategic minerals stockpile, backed by a record $10 billion Ex-Im Bank loan plus private capital, aims to buffer US manufacturers from supply shocks but lacks sufficient domestic processing capacity to convert stockpiled oxides into usable metals and magnets. China still controls 90% of global rare earth refining, leaving the reserve dependent on Beijing for metallization and magnet production. The Pentagon’s Jan 1 2027 procurement rules restricting Chinese-origin rare earths in US weapons systems add urgency, with domestic magnet capacity projected at only 5,000 metric tons by year-end versus 48,000 tons of US demand. Read →
Check out Commodities 101: rare earths section.
| Shipping & Freight | Commodities 101 |
What's moving · Maersk lifts 2026 EBITDA guidance to $14 to 14.5bn on port congestion and high container rates as BDI rises to 2,740 on firmer capesize and panamax earnings.
| Route | $/day | Wk | 1Y | $/t | $/bbl |
|---|---|---|---|---|---|
| VLCC TD3C MEG to China |
$1.41M | +4.5% | +992% | 234.9 | 32.05 |
| Suezmax TD20 WAF to UKC |
$418k | -2.7% | +495% | 118.3 | 16.14 |
| Aframax TD25 USG to UKC |
$230k | +9.8% | +262% | 133.8 | 18.25 |
| LR2 TC1 MEG to Japan |
$304k | -7.7% | +781% | 199.9 | 26.83 |
| LR1 TC5 MEG to Japan |
$223k | -8.9% | +758% | 211.1 | 23.72 |
| MR TC18 USG to Brazil |
$85k | +36.7% | +178% | 114.8 | 13.51 |
| MR TC7 Singapore to Aus |
$76k | -3.5% | +278% | 104.8 | 14.07 |
Report of Oct 29, 2026. Weekly round-voyage TCE and freight cost per tonne and per barrel; TD routes carry crude, TC routes refined products. 1Y is the $/day change; Prism's history starts in October 2023, so there is no 5Y. Source: Prism.
BDI rises 46 points to 2,740 on capesize and panamax gains
Reuters · Thu, Nov 5, 2026
The Baltic Dry Index climbed 46 points or 1.71% to 2,740 on Thursday, its highest since October 13, as the capesize index rose 94 points to 4,191 and panamax index added 62 points to 1,956. Capesize daily earnings increased $851 to $34,510 while panamax earnings rose $554 to $17,603; iron ore prices also gained. Supramax slipped 11 points to 1,824. Read →
All major alliances resume Suez Canal services
SeaNews · Thu, Nov 5, 2026
All four major container alliances, Gemini, Ocean Alliance, Premier Alliance and MSC, have resumed Suez Canal operations with Premier Alliance confirming two new Asia-Mediterranean services starting mid-November. Alphaliner data shows 63% of Far East-Europe capacity now uses the Red Sea route and Suez capacity exceeds 50% of pre-crisis levels. Drewry expects volumes to reach 80% of normal by February 2027. Read →
Check out Commodities 101: shipping section.
| Environment | Commodities 101 |
What's moving · US equity sell-off triggers sharp late-day EUA profit-taking after early gains.
EUAs drop sharply on US equity sell-off profit-taking
Carbon Pulse · Thu, Nov 6, 2026
EU carbon prices fell sharply in late trading on November 5 after US equities dropped as much as 5%, prompting speculative traders to sell EUAs and erase modest earlier gains in a thin market. The move followed a period of recovery toward €90 supported by utility hedging and higher gas prices boosting fossil generation. It highlights short-term sensitivity of the EU ETS to broader equity and energy market swings amid thin volumes. Read →
CCAs top $33, WCAs over $40 on election optimism
Carbon Pulse · Thu, Nov 6, 2026
California Carbon Allowances rose above the $33 mark and Washington Carbon Allowances climbed above $39-$40 amid post-US midterm optimism that bolstered confidence in state-level compliance schemes. The gains reflect renewed buying interest following Democratic gains that may limit federal climate rollbacks. Higher prices signal tighter supply-demand dynamics ahead of upcoming joint auctions in the linked WCI market. Read →
Check out Commodities 101: carbon section.
Real-World Assets & On-Chain Commodities
What's moving · Hyperliquid HIP-3 commodity perps hit record volumes with silver, WTI and gold leading as on-chain 24/7 trading edges TradFi weekends.
World Gold Council unveils Gold as a Service tokenized framework.
Martin Young · The Markets Cafe · Fri, Nov 6
The World Gold Council and Boston Consulting Group released a white paper proposing “Gold as a Service,” a shared infrastructure platform to standardize custody, issuance, redemption and interoperability for digital gold products. The model aims to reduce fragmentation and boost fungibility for tokenized gold, which accounts for about 20% of the $36.8 billion tokenized RWA market per RWA.xyz. Read →
Industry News
Corporate & Deals
What's moving · Oil majors and midstream firms post strong Q3 beats on high prices, with TC Energy raising guidance and sanctioning C$3B gas projects while BP sells Aker BP stake for $1.06B.
TC Energy lifts 2026 profit view, sanctions C$3B gas projects
Reuters · Thu, Nov 5, 2026
TC Energy raised its 2026 adjusted core earnings forecast to C$11.8 to 12.0 billion after beating quarterly estimates, citing strong natural gas pipeline volumes. It sanctioned about C$3 billion in new projects including the $1.8 billion Crossroads Expansion and $400 million American Midwest project adding 2.4 Bcf/d capacity. The moves target rising North American gas demand from power generators and data centers. Read →
EOG beats Q3 estimates, raises dividend 8%, records production
Reuters · Thu, Nov 5, 2026
EOG Resources posted adjusted Q3 profit of $4.87 per share, beating estimates, on elevated crude prices and record 1.43 million boed production. The company generated $2.18 billion free cash flow, repurchased $1 billion shares, and raised its quarterly dividend 8% to $1.10. It approved a Delaware Basin gas plant expansion and a long-term Asian LNG supply deal. Read →
Canadian Natural beats Q3 estimates on higher prices and output
Reuters · Thu, Nov 5, 2026
Canadian Natural Resources reported adjusted Q3 profit of C$1.65 per share, beating estimates, helped by stronger crude prices and output of 1.65 million boepd. Realized liquids prices rose to C$95.93 per barrel from C$72.57 a year earlier. The largest Canadian producer maintained its 2026 production guidance amid favorable oil sands economics. Read →
Regulation & Government
What's moving · Democrats' midterm sweep tightens congressional oversight on Trump energy and tariff policies.
China diesel exports seen easing on low stocks
Reuters · Thu, Nov 5, 2026
Chinese refiners have sold only about 500,000 metric tons of diesel for November loading so far, with early estimates pointing to at most 800,000 tons total. Tight domestic inventories after prior export surges limit shipments from Asia's key swing supplier. Reduced Chinese diesel availability tightens global distillate balances already strained by Middle East disruptions. Read →
Democrats win Congress, target energy policy
Timothy Gardner and Paul Simao · Reuters via Finance & Commerce · Thu, Nov 5, 2026
Democrats gained control of both US House and Senate in Tuesday's midterms, giving them leverage to scrutinize Trump administration energy actions. Potential moves include conditions on Iran-war spending to push a Strait of Hormuz deal and delays to fossil-fuel-friendly permitting legislation. The shift also raises prospects for renewed clean-energy tax credits and tighter oversight of data-center power demand. Read →
US loans 300k barrels from heating oil reserve
Reuters · Wed, Nov 4, 2026
The Energy Department awarded contracts to loan 300,000 barrels of fuel oil from the Northeast Home Heating Oil Reserve to four companies. Deliveries from Boston and New Haven sites must finish by November 6, with borrowers required to return equivalent volumes plus a premium by next heating season. The move addresses record diesel prices above $6.50 per gallon linked to Iran-related supply strains. Read →
What traders and commodity market feeds are talking about
Iran oil exports crash to near zero on US blockade
X / multiple traders · Fri, Nov 6
Traders on X highlight Iran's oil exports dropping to almost zero after more than eight months of war and a US naval blockade. The development is seen as tightening global supply and pressuring Tehran economically, with direct implications for crude prices and Middle East risk premium. Read →
Russia YANOS refinery offline post attack
X / @finsquawk_ · Fri, Nov 6
X posts flag the shutdown of Russia's YANOS oil refinery following an attack on Nov 3. Traders note ongoing strikes on Russian energy infrastructure, adding to diesel market tightness and supply concerns in Europe. Read →
Oil dips as Iran breakthrough hopes rise
X / multiple traders · Fri, Nov 6
Discussions on X show oil prices pulling back after earlier gains as diplomatic efforts signal possible easing of Middle East tensions. Traders weigh renewed hopes for an Iran deal against persistent Hormuz risks and recent price volatility. Read →
Gold setups eye sell into 4040 to 4030 zone
X / multiple traders · Fri, Nov 6
Retail and technical traders on X post short setups for XAUUSD, citing rejection at trendlines and supply zones around 4070 to 4080 with targets down to 4040 to 4030. Momentum and RSI signals are driving the bearish bias in gold trading chats. Read →
Gold hovers near 4050 on jobs report watch
X / multiple traders · Fri, Nov 6
X conversations note gold trading around 4047 after a modest pullback, with focus on the upcoming US jobs report and rate expectations. Oil rebound is cited as a factor weighing on the metal in early Friday action. Read →
Recent video and podcast calls from respected oil and commodity analysts
Ex-Goldman natgas trader on inventory equation & volatility
John Knorring on Odds on Open podcast · Thu, Nov 5
Supply minus demand equals change in inventory, and price does all the balancing when storage is full or empty. Watch/Listen →
Ag panel on post-harvest marketing & China tariffs
Commodity Week podcast (Todd Gleason et al.) · Thu, Nov 5
December 11 ARC/PLC farm program deadline is critical for unpriced corn and soybeans in storage. Watch/Listen →
Wells Fargo metals analyst on AI demand & steel
AI may account for only a small share of copper demand while China's property weakness remains significant. Watch/Listen →
Where commodity traders watch asymmetric risk · live odds via Polymarket
Hormuz Crisis
US-Iran tensions disrupting Strait of Hormuz oil flows. Polymarket odds, last 7 days.
US announces the end of the Iran blockade by December 31
43%
+3pp w/w
Hormuz traffic returns to normal by December 31
10%
-1pp w/w
Source: Polymarket
US Diesel Export Ban
Would cut US distillate exports, widen the US-Europe diesel spread and hit Gulf Coast refining margins. Polymarket odds, last 7 days.
US announces a diesel export ban by December 31
6%
-18pp w/w
Source: Polymarket
Red Sea / Bab el-Mandeb
Houthi threat to Red Sea shipping; a closure reroutes tankers and LNG around the Cape. Polymarket odds, last 7 days.
Bab el-Mandeb effectively closed by December 31
8%
-7pp w/w
Source: Polymarket
Fed Policy
Fed rate decisions move USD strength and industrial energy demand expectations. Polymarket odds, last 7 days.
Fed hikes 25 bps at the December meeting
69%
-4pp w/w
Source: Polymarket
Russia / Ukraine Energy
A ceasefire would shift Russian crude and product flows and European gas pricing. Polymarket odds, last 7 days.
Russia-Ukraine ceasefire agreement by December 31
14%
+1pp w/w
Source: Polymarket
Paid listings · list your event
Commodity & Energy Trading Week APAC · Mar 3-4 · Singapore
Commodity Trading Week Europe · May 19-20 · London
Was this forwarded to you? Subscribe free.
The cash price of physical crude globally, real‑time live even on weekends.
Prism is Morgan’s service providing free real‑time cash prices for physical crude oil, refined products, freight, natural gas and more. See today’s prices.
Morgan Downey's Commodity News is published by Wooden Table Press LLC. Informational only, not financial or legal advice. Do your own research. No representation is made as to accuracy or completeness.
Unsubscribe · View in browser · Subscribe
One sponsor per issue. Ask us about a future month →
Unsubscribe · View in browser · Subscribe