The gen alpha daily zeitgeist of the physical commodity world
Oil · Gas · NGLs · Power · Coal · Ags · Metals · Fertilizers · Rare Earths · Shipping · Environment · RWA · Podcast · Kickers · Archive
Friday, September 25, 2026
▶ The 2-minute market brief · video · 1.25x
Listen · the 2‑minute market briefToday's markets in two minutes. Tap to play
Prefer audio only? Listen here.
Markets at a glance
Last price as of Fri, Sep 25, 5:35 AM ET · 1-day change vs prior settle. Continuous front-month futures. Click price for news.
Downey's Take
Brent down $1.52 (-1.4%) and WTI down $1.65 (-1.7%) this morning. Crude had traded intraday Thursday (yesterday) up 5% until a story broke by Reuters around 12noon NY time that US and Iranian negotiators in New York are exploring a phased path out of the war: Iran would reopen Hormuz; the US would lift its economic blockade of Iranian ports. A phased deal, not a finished agreement. Nuclear issues would likely be pushed to a later phase. Iran’s foreign minister said Tehran had given mediators a seven-day plan: if conditions are met, Hormuz would reopen at the end of that window and talks would restart. Xi at the White House told Trump that the US and Iran should go back to talks. But no public readout of the private meeting was made available.
Nat Gas down $0.110 (-3.3%) as the market cools following a big rally earlier this week.
JKM up $0.65 (+2.5%) on strong Asian LNG demand.
Wheat down $15 (-2.1%).
Corn down $10 (-1.8%) on weak export sales and advancing harvest supply.
Silver up $1.01 (+1.6%).
Nat Gas down $0.110 (-3.3%) as the market cools following a big rally earlier this week.
JKM up $0.65 (+2.5%) on strong Asian LNG demand.
Wheat down $15 (-2.1%).
Corn down $10 (-1.8%) on weak export sales and advancing harvest supply.
Silver up $1.01 (+1.6%).
Drivers and the Kicker trade idea are sourced from third-party news and bank or desk commentary. Informational only, not BoxWood trade advice.
The marquee commodity stories of the day
Oil falls as truce hopes outweigh Houthi strikes
Reuters · Thu, Sep 24, 9:11 PM ET
Oil prices fell Friday as markets weighed a possible US-Iran truce and reopening of the Strait of Hormuz against fresh Houthi missile attacks on Saudi Arabia. Brent dropped about 1.4% to around $105 a barrel while WTI fell more than 2% to near $92.60, with the Brent-WTI spread widening to its widest since May on diverging supply risks. Read →
Oil drops on phased Hormuz deal hopes
Bloomberg · Fri, Sep 25, 2:24 AM ET
Brent crude fell toward $105 a barrel as US and Iranian negotiators explored a phased deal to reopen the Strait of Hormuz. The pullback eased pressure on global bond yields after a sharp selloff, even as France signaled troops to protect a Saudi oil plant amid new Houthi attacks. Read →
EU urges Trump to keep diesel exports flowing
Financial Times · Fri, Sep 25
The EU energy commissioner warned of the continent’s ‘worst winter’ for energy prices since 2022 and pressed the Trump administration to maintain diesel export flows. Europe faces acute supply pressure as diesel prices surge amid Middle East disruptions and talk of a possible US export ban. Read →
Outokumpu develops new chrome extraction method
Financial Times · Thu, Sep 24
Outokumpu unveiled a method to produce chrome used in jet engines that could also strengthen Western supply chains for critical metals. The Finnish firm said the process supports reduced dependence on non-Western sources for key industrial inputs. Read →
Brent on longest losing streak in over a year
Financial Times · Wed, Sep 23
Brent crude fell below $99 a barrel in Asian trading amid ongoing Middle East conflict talks, putting it on course for its longest losing streak in more than a year. Prices have been pressured by hopes for de-escalation and incremental supply improvements. Read →
Most clicked yesterday
In this issue · tap a section to jump to it
Oil 3US Natural Gas 4Wet Gas, NGLs/LPGs & Petchems 2Global Nat Gas & LNG 2Power 2Coal 2Agriculture 2Base Metals 4Iron Ore & Steel 2Precious Metals 3Rare Earths & Critical Minerals 3Shipping & Freight 3Environment 2Real-World Assets & On-Chain Commodities 3Corporate & Deals 4Regulation & Government 2Social buzz 5Watch & Listen 3Prediction Markets
Markets News
Oil
What's moving · Oil dips on US-Iran truce hopes despite fresh Houthi strikes on Saudi targets and persistent Hormuz risks.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| WTI Crude | 92.96 | -1.7% -1.65 |
+61.9% | +41.4% | +23.2% |
| Brent | 105.08 | -1.4% -1.52 |
+62.2% | +40.8% | +24.1% |
| RBOB Gasoline | 3.269 | -1.9% -0.064 |
+91.7% | +60.4% | +47.0% |
| Heating Oil | 4.509 | -0.4% -0.019 |
+112.6% | +85.6% | +96.4% |
| NY RBOB Crk $/bbl |
44.34 | -2.3% -1.04 |
+212.2% +30.14 |
+123.3% +24.49 |
+147.2% +26.40 |
| NY HO Crk $/bbl |
96.42 | +0.9% +0.85 |
+204.7% +64.78 |
+165.7% +60.13 |
+359.7% +75.44 |
| NY 321 Crack $/bbl |
61.70 | -0.7% -0.41 |
+208.3% +41.68 |
+143.6% +36.37 |
+225.6% +42.75 |
Oil rises on stalled Iran talks and Saudi export delays
Karim Bastati · DTN · Thu, Sep 24, 2026
Brent climbed toward $105.07 and WTI to $93.69 amid stalled US-Iran talks and Saudi Aramco extending Yanbu shipment suspensions to Europe into November after drone damage to the East-West pipeline. US distillate stocks fell sharply last week while crude inventories built by 3 million barrels. Tehran reportedly issued a one-week ultimatum on lifting the US naval blockade, supporting prices. Read →
Oil slips on US-Iran phased Hormuz deal talks
Bloomberg · Thu, Sep 24, 2026
Brent eased toward $106 after gains of more than 7% over two days as US and Iranian negotiators explored a phased deal for Tehran to reopen the Strait of Hormuz during UNGA talks. WTI traded below $94. Supply gauges showed extreme tightness with record premiums at Cushing and a widening Brent-WTI spread to its largest since May. Read →
Saudi oil exports hit war-time high via Hormuz
Bloomberg · Thu, Sep 24, 2026
Saudi crude shipments in September reached the highest level since the Iran war began as the kingdom ramped up exports through the Strait of Hormuz following the East-West pipeline attack. Loadings from Gulf terminals surged, with nearly 100 million barrels sold to Asian buyers for October-November delivery. This shift helps offset Red Sea route disruptions but keeps tanker traffic concentrated in Hormuz. Read →
US Natural Gas
What's moving · Natgas futures drop on profit-taking after Appalachian pipeline outage and below-average 53 Bcf EIA storage build drove sharp rally.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Henry Hub | 3.187 | -3.3% -0.110 |
-11.4% | +15.1% | -42.8% |
EIA gas storage · week ending Fri, Sep 18
A 53 Bcf injection took working gas to 3,351 Bcf, 95 Bcf (3%) above the five-year average and 146 Bcf below a year ago. That is 3 Bcf below the +56 Bcf consensus, in line for price.
Working gas 3,351 Bcf +53 Bcf w/w | Year ago 3,497 Bcf | 5-yr avg 3,256 Bcf |
Consensus +56 Bcf this week | Year-ago chg +76 Bcf | 5-yr avg chg +73 Bcf |
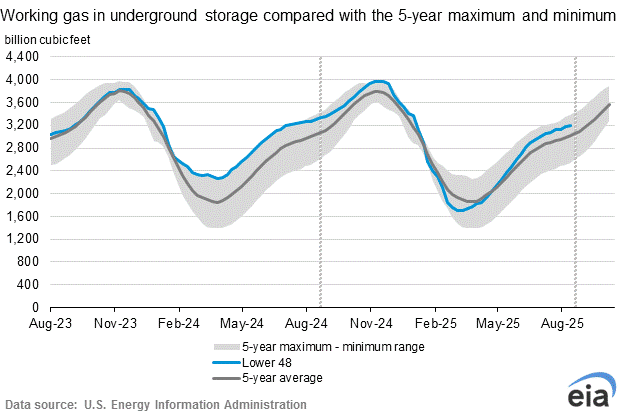
Source: EIA Weekly Natural Gas Storage Report · Full EIA report →
Natgas futures climb 2.6% to 11-week high on cooler weather, lower output, highe
Reuters · Wed, Sep 24, 2026
Front-month October NYMEX futures rose 7.6 cents to $3.041/MMBtu, the highest close since July 8. LSEG data showed daily Lower 48 output falling toward an 11-week low of 109.8 bcfd from September averages near 112.9 bcfd, mainly in Louisiana and Pennsylvania, while flows to nine major LNG plants averaged 18.0 bcfd so far in September despite Cove Point maintenance. The moves reflect tightening near-term supply amid forecasts for cooler weather boosting heating demand. Read →
53 Bcf EIA storage injection, below norms, lifts futures above $3 to multi-week
Kevin Dobbs · Natural Gas Intelligence · Thu, Sep 24, 2026
EIA reported a 53 Bcf build for the week ended Sept. 18, well below the five-year average of 76 Bcf, shrinking the storage surplus to 2.9% above normal from 3.7%. Combined with lighter production and hints of heating demand, the lean print propelled October futures to their highest levels since July amid short-covering. Read →
TC Energy Columbia Gas Transmission outage strands 1.8 Bcf/d Appalachian supply
Energy News Beat · Thu, Sep 24, 2026
TC Energy declared force majeure on its Mountaineer XPress system due to a mechanical issue on Line 100 in West Virginia, cutting the MXPSEG MA42 constraint to zero and affecting 1.8 MMDth/d of firm service starting Sept. 25. The 2.7 Bcf/d Appalachian takeaway line disruption triggered the largest single-day futures gain since January as supply tightened. Read →
Prices fall to $3.17/MMBtu after profit-taking follows 13-week high on West Virg
Judith Sib-at · Trading Economics · Fri, Sep 25, 2026
US natural gas prices eased to around $3.17 per MMBtu on Friday as traders booked profits following the prior session's surge to a 13-week high. The rally had been fueled by the TC Energy Columbia Gas Transmission force majeure in Appalachia and the below-average EIA storage build, with LNG feedgas demand remaining supportive at 17.8 bcfd average flows in September. Read →
Sponsored · Vortexa
The Vortexa Innovation Series: Four Cities, One Global Conversation
Vortexa's Innovation Series returns this fall to four cities: Dubai (Sept 30), New York (Oct 6), Houston (Oct 8), and London (Oct 14). Each stop brings Vortexa's analyst team together with the traders, shippers and financiers navigating today's most volatile energy markets, for an exclusive briefing on what's moving crude, products, freight and LNG, powered by real-time data. You'll also get a first look at how AI is reshaping trading workflows, turning natural-language questions into market-ready insight. With Hormuz and the Red Sea reshaping flows in real time, these are must-attend sessions for anyone tracking waterborne energy.
Free to attend, but seats are limited and filling fast across all four cities!
Wet Gas, NGLs/LPGs & Petchems
What's moving · Mont Belvieu propane spot at 84.6¢/gal (+2.3%) on EIA-reported 1.2 MMbbl propane/propylene draw driven by rising exports.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Ethane C2 $/gal |
0.250 | +0.7% +0.002 |
+5.5% | -0.4% | -35.0% |
| Propane C3 $/gal |
0.846 | +2.3% +0.019 |
+37.2% | +19.0% | -33.7% |
| N-Butane NC4 $/gal |
1.264 | +1.7% +0.021 |
+69.6% | +40.8% | -13.7% |
| Isobutane IC4 $/gal |
1.454 | +2.4% +0.033 |
+87.0% | +57.0% | +1.0% |
| Pentane C5 $/gal |
2.049 | +2.4% +0.047 |
+74.8% | +56.4% | +21.2% |
| Spread | Now | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| C2 Frac Sprd ¢/gal | 4 | +1 | +4 | -3 | +2 |
| C3 Frac Sprd ¢/gal | 56 | +3 | +27 | +10 | -21 |
| C2 vs NWE Naph $/mt | -653 | unch | -348 | -283 | -273 |
| C3 vs NWE Naph $/mt | -406 | +8 | -238 | -211 | -392 |
| C5 as % WTI | 93 | +4 | +7 | +9 | -2 |
Mont Belvieu front-month settlement. Frac spread is the liquid over Henry Hub fuel value; naphtha spreads are before freight.
EIA draw of 1.2 MMbbl propane/propylene lifts exports.
Adam Baker · RBN Energy · Wed, Sep 23, 2026
The EIA reported a 1.2 MMbbl U.S. propane/propylene inventory draw for the week ended September 18, concentrated in PADD 3 and tied to higher reported exports. Gulf Coast stocks fell 1.2 MMbbl to 68.4 MMbbl. The draw supports Mont Belvieu pricing amid strong export flows. Read →
ET adds 240 Mb/d ethane and 55 Mb/d LPG capacity at Nederland.
Tanks and Terminals · Thu, Sep 24, 2026
Energy Transfer will expand its Nederland NGL Export Terminal by 240,000 b/d ethane and 55,000 b/d LPG capacity, with 100% of the new ethane volume already under long-term contracts to 2040s. The project includes added Mont Belvieu-to-Nederland pipeline capacity and two new ship docks, phasing in from 2028. Combined with Marcus Hook, ET's total NGL export capacity will reach 1.7 MMb/d. Read →
Global Nat Gas & LNG
What's moving · TTF falls on warmer European weather forecasts and rising northwest Europe LNG send-out despite 38.5% storage fill.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Dutch TTF €/MWh |
75.27 | +0.2% +0.16 |
+167.3% | +130.2% | -1.6% |
| Dutch TTF $/MMBtu |
25.13 | +0.2% +0.05 |
+167.3% | +130.2% | -1.6% |
| JKM $/MMBtu |
26.38 | +2.5% +0.65 |
+174.6% | +133.6% | -9.6% |
EU gas storage · gas day Wed, Sep 23
EU gas storage is 70.3% full, 796 TWh in store, 15.7 points below the five-year average for this date and 11.7 points below a year ago. Germany, the bloc's largest store, is 57.0%.
EU full 70.3% +0.11 pts d/d | Year ago 82.0% | 5-yr avg 86.0% same date |
Germany 57.0% |
Source: GIE AGSI+ · Full AGSI+ data →
TTF falls on warmer forecasts, high LNG send-out
World Energy News · Fri, Sep 25, 2026
Dutch TTF front-month fell 0.30 euros to 34.76 EUR/MWh amid warmer temperature forecasts curbing demand. Europe's gas storage sits at 38.5% full per Gas Infrastructure Europe while northwest Europe LNG send-out is set to rise 80 GWh/day to 2,179 GWh/d. The move occurs as this week's TTF contract dropped around 14% on ample supply. Read →
JKM, TTF ease as geopolitics de-risk, supply improves
Global LNG Hub · Thu, Sep 24, 2026
JKM fell to low-USD 27s/MMBtu on 18 September from mid-USD 28s the prior week as Middle East risk premiums eased. TTF (October) settled at USD 26.7/MMBtu after initial hedging and injection support gave way to higher LNG imports and wind generation expectations. Northeast Asian inventories and subdued shoulder-season demand limited downside. Read →
Power
What's moving · ERCOT pauses data-center interconnections amid 474 GW queue audit as Texas tightens large-load rules.
Texas environmental agency freezes data center permits
Shane Snider · TechTarget · Thu, Sep 24, 2026
The Texas Commission on Environmental Quality halted air, water and other permits for data center infrastructure following the governor's directive. The freeze applies while ERCOT and water authorities review projects; compliance updates are due Oct. 19. It adds regulatory hurdles beyond grid interconnection for developers. Read →
Vistra sees excess capacity for flexible data-center loads
Robert Walton · Utility Dive · Thu, Sep 24, 2026
Vistra CEO Jim Burke stated that PJM and ERCOT have sufficient excess capacity outside super-peak hours to handle near-term data-center growth if loads are flexible or use on-site generation. Data-center interest has more than doubled year-over-year, supporting higher utilization of the company's gas plants. Read →
Coal
What's moving · India affirms coal will supply half its power through 2035 to 36 amid surging demand.
India expects coal to supply half its power through 2035 to 36
Reuters · Thu, Sep 24, 2026
Senior Indian power ministry officials said coal will generate about half of the country's electricity in 2035 to 36. India plans to expand coal-fired capacity from 224 GW to 315 GW by then to meet rising power demand alongside renewables growth. The outlook underscores thermal coal's role as baseload supply for the world's third-largest coal consumer. Read →
High European gas prices drive utilities back to coal
Reuters · Thu, Sep 24, 2026
Soaring European natural gas prices are prompting utilities to increase coal-fired power generation. Analysts expect coal output to rise by about a quarter over the next six months as gas-fired generation falls. The shift supports thermal coal demand in the Atlantic market amid elevated gas costs. Read →
Agriculture
What's moving · Weak USDA export sales and fading U.S.-China summit hopes drive grains lower.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Corn | 518 | -1.8% -10 |
+17.6% | +22.7% | -4.0% |
| Wheat | 692 | -2.1% -15 |
+36.5% | +33.2% | -4.2% |
| Soybeans | 1,305 | -1.0% -13 |
+26.6% | +28.7% | +1.3% |
| Sugar | 18.56 | -0.3% -0.05 |
+23.7% | +17.0% | -0.9% |
| Coffee | 278.7 | +1.2% +3.3 |
-20.1% | -26.3% | +43.9% |
| Cocoa | 5,598 | +0.1% +8 |
-7.7% | -19.0% | +119.9% |
| Cotton | 82.86 | -0.5% -0.45 |
+29.0% | +29.6% | -16.2% |
Export sales disappoint across grains complex
Jack Scoville · Price Futures Group · Thu, Sep 24, 2026
USDA reported 838,300 MT corn sales, 267,600 MT wheat sales and 582,400 MT soybean sales for the week ended Sept. 17. China bought 311,800 MT of soybeans and a separate 120,000 MT private sale was announced. Markets traded lower ahead of the Trump-Xi summit with limited new demand signals. Read →
Cotton rises on record weekly export sales
Austin Schroeder · Barchart / Paragon · Thu, Sep 24, 2026
Upland cotton export sales hit a marketing-year high of 230,517 running bales for the week ended Sept. 17. Mexico led with 69,800 bales and Vietnam took 51,200. Futures closed up 2 to 60 points as shipments reached 164,704 bales, 20% above the prior year. Read →
Base Metals
What's moving · China inventory draws and Escondida suspension tighten copper supply, lifting LME prices toward weekly gains.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Copper NY $/mt |
14,939 | -0.2% -31 |
+20.4% | +43.7% | +57.8% |
| Copper SHFE $/mt |
14,606 | -0.6% -87 |
+15.0% | +47.6% | +53.1% |
| Aluminium SHFE $/mt |
3,194 | -0.0% -1 |
+7.3% | +24.5% | +10.1% |
| Zinc SHFE $/mt |
3,520 | +0.2% +8 |
+17.2% | +28.0% | +15.3% |
| Nickel SHFE $/mt |
16,500 | -0.7% -119 |
-2.6% | +8.6% | -19.7% |
| Lead SHFE $/mt |
2,149 | -0.7% -14 |
-2.5% | +3.1% | +5.4% |
| Tin SHFE $/mt |
54,269 | -0.4% -205 |
+29.2% | +60.0% | +58.8% |
Copper edges higher on China supply tightness
Reuters via Business Recorder · Fri, Sep 25, 2026
Benchmark three-month LME copper rose 0.08% to $14,632/t early Friday and is set for a weekly gain after SHFE copper inventories fell 15.9% to 47,147 tons. The LME cash-to-three-month spread widened to a $124.75/t backwardation, signaling acute near-term tightness in the key consumer market. The moves follow pre-holiday stockpiling and smelter maintenance cuts in China. Read →
Escondida resumes after fatal accident
Reuters · Thu, Sep 24, 2026
BHP's Escondida, the world's largest copper mine, suspended operations Wednesday after a worker died during maintenance and is now resuming progressively following safety assessments. The incident adds to already tight physical supply signals in copper. Escondida is a joint venture with Rio Tinto and JECO Corp. Read →
Nyrstar reviews future of Dutch zinc smelter
Nyrstar · Thu, Sep 24, 2026
Nyrstar announced a strategic review of its Budel zinc smelter in the Netherlands, citing high energy costs, low treatment charges, and lack of Dutch grid-cost relief in the 2027 budget. The review will conclude by year-end while operations continue normally. The move intensified zinc supply concerns and supported LME zinc prices. Read →
Lithium carbonate futures drop 4.79%
Shanghai Metals Market · Thu, Sep 24, 2026
Battery-grade lithium carbonate futures on GFEX fell 4.79% to close at 124,400 yuan/t amid weak spot buying and lower weekly production from spodumene and lepidolite processors. Spot prices drifted lower with downstream purchase intentions below 130,000 yuan/t. The decline reflects ample near-term supply in the battery metal. Read →
Iron Ore & Steel
What's moving · SGX iron ore futures hover near $96/t as Chinese port stocks build and steel mill margins stay squeezed.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Iron Ore 62% DCE $/dmt |
94.2 | +0.1% +0.1 |
-6.4% | -1.6% | -11.6% |
| Rebar SHFE $/mt |
402 | -0.3% -1 |
+2.1% | +3.8% | -44.2% |
| HRC SHFE $/mt |
433 | -0.5% -2 |
+5.1% | +5.5% | -42.8% |
China rebar prices fell 0.6% mid-September.
Eunice Ouyang · SteelOrbis · Thu, Sep 24, 2026
China’s National Bureau of Statistics reported average 20mm HRB400E rebar prices dropped RMB 17.6/mt (0.6%) to RMB 3,165.1/mt in mid-September versus early September. HRC, wire rod and other steel products also declined 0.4 to 1.3%. The data reflect persistent weak property-sector demand pressuring finished-steel prices. Read →
Rio Tinto, Baowu finish Pilbara DRI trials.
Global Mining Review · Fri, Jun 12, 2026
Rio Tinto and China Baowu completed industrial-scale trials at Baoshan Zhanjiang using hydrogen-based shaft furnace DRI from pellets with one-third Pilbara Blend ore. The DRI was converted to steel via BOF and tested in an electric smelting furnace, showing mid-grade Pilbara ore can support lower-carbon steelmaking pathways. Read →
Precious Metals
What's moving · Gold tilts lower near $4,270/oz as Iran impasse fuels Fed rate-hike bets and dollar strength.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Gold | 4,329 | +0.7% +31 |
-0.3% | +13.7% | +147.1% |
| Silver | 65.01 | +1.6% +1.01 |
-7.3% | +40.7% | +186.9% |
| Platinum | 1,765 | +0.7% +13 |
-12.5% | +12.5% | +81.2% |
| Palladium | 1,264 | -1.4% -18 |
-22.4% | -2.1% | -35.1% |
Gold tilts lower near $4,270 as Iran talks stall and rate-hike bets rise.
Bloomberg · Thu, Sep 24, 11:53 PM ET
Gold traded around $4,270 an ounce, down more than 2% for the week. Elevated energy prices from the US-Iran impasse lifted bond yields and boosted odds of further Federal Reserve rate hikes. Oil steadied after a surge while negotiators explored a phased Hormuz deal. Read →
Gold hits one-week low at $4,265 as oil and hawkish Fed weigh.
Anjana Anil · Reuters · Thu, Sep 24
Spot gold eased 0.5% to $4,265.50 per ounce, its lowest since September 16. Higher oil after a Houthi attack and Fed officials signaling more rate hikes pressured prices. The dollar hit a two-month high and 10-year Treasury yields reached near two-decade highs. Read →
Gold heads for weekly loss as dollar and Fed outlook weigh.
Reuters · Fri, Sep 25
Spot gold fell 0.2% to $4,270.40 per ounce and is down more than 2% for the week. A firmer dollar and expectations of sustained high US rates to fight inflation weighed on bullion. Silver slipped 0.5% to $63.58 while platinum steadied and palladium fell 1.3%. Read →
Rare Earths & Critical Minerals
What's moving · Pr-Nd oxide prices rebound in China as US Army awards Vulcan Elements magnet contract for SkyFoundry drones.
US Army picks Vulcan for rare earth magnets in drone program
Vulcan Elements / Axios · Wed, Sep 23, 2026
The U.S. Army selected Vulcan Elements to supply neodymium-iron-boron magnets for its SkyFoundry initiative targeting one million small drones annually at Tobyhanna Army Depot. Vulcan was chosen for its fully China-decoupled supply chain matching high-performance specs for brushless DC motors. This marks Vulcan’s 10th Defense Department contract and highlights accelerating Western efforts to secure domestic permanent-magnet capacity amid China dominance. Read →
Neo signs MoU for Rainbow Phalaborwa NdPr and heavy REE offtake
Neo Performance Materials / Newswire.ca · Thu, Sep 24, 2026
Neo Performance Materials signed an MoU with Rainbow Rare Earths for technical support on Phalaborwa’s solvent extraction circuit in exchange for offtake of 40% of annual >99% purity NdPr oxide and 65% of mixed SEG+ heavy rare earth carbonate containing dysprosium and terbium. Test work is underway at Neo’s Estonia facilities. The deal secures non-Chinese feedstock for Neo’s European magnet supply chain ahead of Rainbow’s PFS and planned 2028 production. Read →
Pr-Nd oxide prices rebound in China this week
Shanghai Metals Market (SMM) · Thu, Sep 24, 2026
Pr-Nd oxide prices rose to 737,000 to 739,000 yuan/mt, up overall week-on-week and versus the prior Monday start, driven by large-plant purchases and international news improving NdFeB export expectations. Pr-Nd alloy quotes reached 893,000 to 900,000 yuan/mt. Medium- and heavy-rare-earth prices remained generally weak or stable with limited trading. Read →
Shipping & Freight
What's moving · Baltic Dry Index rises 1.2% to 3,473 on Thursday, highest since Sept 11, led by Capesize and Panamax gains.
Baltic Dry Index climbs as rates rise across all segments
Katha Kalia · Reuters · Thu, Sep 24, 5:48 PM ET
The Baltic Exchange’s dry bulk freight index rose 43 points or 1.2% to 3,399 points on Thursday, its highest level in nearly two weeks. Capesize rates increased 1.3% to 5,939 points with average daily earnings up $709 to $50,361; Panamax advanced 2.1% to 2,382 points. The gains reflect firmer demand for iron ore, coal and grain transport amid ongoing global trade flows. Read →
SCFI dips slightly but US-bound rates stay elevated ahead of Golden Week
Commercial Times / Liberty Times · Thu, Sep 24, 2026
The Shanghai Containerised Freight Index fell 1.21 points to 3,686.62, ending an eight-week winning streak with a 0.03% weekly decline. US West Coast rates dropped 1.28% to $7,463 per FEU and East Coast 0.78% to $10,497 per FEU, yet remain historically high due to pre-Golden Week rush shipping, Shanghai/Ningbo congestion and lingering Red Sea rerouting effects. Southeast Asia rates rose 5.61%, highlighting persistent capacity tightness on key lanes. Read →
Dirty tanker rates edge higher on key AG routes
CommodityScope · Thu, Sep 24, 2026
VLCC rates on Arabian Gulf to China routes rose to $238.05/mt (+$2.08) and to Far East $247.21/mt (+$2.16) as of 24 September. Suezmax and Aframax assessments held mostly steady across East of Suez lanes while select Mediterranean and Atlantic routes showed minor gains. Elevated levels persist amid Middle East supply disruptions and longer effective voyage distances. Read →
Environment
What's moving · Washington linkage advances create larger, more stable North American carbon market as EU countries retain spare ETS permits to buffer price spikes.
Washington nears linkage with California-Quebec carbon market.
The Spokesman-Review · Thu, Sep 24, 2026
Washington Gov. Bob Ferguson announced agreement on regulatory changes to link its carbon market with California and Quebec during Climate Alliance meetings in New York. California Gov. Gavin Newsom authorized the state to proceed with linkage, expected to complete next year and enable joint auctions with shared allowance prices. The move creates a larger market for trading credits across the three jurisdictions, with recent Washington auction prices at $32 per ton versus $32.48 in California-Quebec. Read →
D6 RIN prices drop after EPA extends 2025 compliance deadline.
World Energy News · Fri, Sep 25, 2026
D6 RIN prices fell to $1.75 per unit, their lowest in over four months, after the EPA extended the September 1 compliance reporting deadline to October 1 for the 2025 RFS year. The extension follows decisions on small refinery exemptions and provides refiners more time amid high compliance costs from elevated 2026 mandates. Biomass-based diesel RINs also eased to around $1.92. Read →
Real-World Assets & On-Chain Commodities
What's moving · CFTC guidance lets U.S. commodities firms invest in tokenized assets and use blockchain records.
CFTC clears tokenized assets for U.S. commodities firms
Jesse Hamilton · CoinDesk · Thu, Sep 24, 10:04 PM ET
The CFTC updated FAQs Thursday confirming that registered firms may invest customer funds in tokenized versions of already-permitted assets, provided legal and economic rights match the traditional form. It also stated blockchain technology satisfies recordkeeping obligations. The move gives explicit regulatory backing for tokenized commodities and RWAs within CFTC oversight. Read →
Hyperliquid gold perps surge on volatility chase
Cryptopolitan via CryptoNews · Fri, Sep 25, 2026
Gold perpetual futures rank second on Hyperliquid with $299.55M open interest, outpacing many equity contracts and oil perps on HIP-3 markets. Tokenized gold totals nearly $5B, dominated by XAUT and PAXG. 24/7 on-chain access draws traders seeking directional bets amid gold volatility near 27%. Read →
CFTC updates guidance as tokenized assets hit $46B
Crypto Times · Thu, Sep 24, 2026
The CFTC released updated FAQs on tokenized permitted investments and blockchain recordkeeping the same day tokenized RWAs reached $46B market cap. Commodities represent roughly $7.7B of that total. The clarification applies to CFTC-registered platforms handling customer funds and regulatory data. Read →
Industry News
Corporate & Deals
What's moving · Genel Energy's raised $436M bid wins back Capricorn Energy board support, topping DNO in Egypt-focused M&A battle.
Genel raises bid to $436M, tops DNO for Capricorn
Reuters · Fri, Sep 25, 2026
Genel Energy increased its cash offer for Capricorn Energy to $436 million, securing board backing with a 10% premium over DNO's rival bid. The deal gives Genel a major foothold in Egypt's Western Desert assets, ending a months-long bidding war. It diversifies Genel's production away from Kurdistan and marks heightened M&A interest in Egyptian upstream amid strong oil prices. Read →
Shell closes $840M Gulf of Mexico asset sale
Oil & Gas 360 / World Oil · Wed, Sep 23, 2026
Shell finalized the sale of its 50% non-operated interest in the bp-operated Na Kika platform and 100% interest in the Coulomb tieback for about $840 million in cash. Talos Energy and Ridgewood Energy acquired the assets, which produced 37,000 boed net to Shell in 2025. The deal advances Shell's portfolio high-grading strategy while retaining upside payments and offtake rights. Read →
BP eyes Devon Eagle Ford shale assets in data room
David French, Arathy Somasekhar · Reuters · Thu, Sep 24, 2026
BP entered data rooms for Devon Energy's Eagle Ford assets in South Texas as part of renewed shale growth efforts under new leadership. The roughly 90,000-net-acre position produced 77,000 boepd in Q2 and is valued around $3.5 to 4.5 billion. BP targets oil-weighted US shale assets valued $2 to 5 billion to expand its BPX Energy footprint. Read →
Ignitis signs 10-year US LNG deal with EQT
Enerdata / Lithuanian Ministry of Energy · Wed, Sep 23, 2026
Ignitis signed a 10-year LNG supply agreement with EQT for one cargo per year from 2027 to 2036, totaling about 10 TWh. The deal, Lithuania's first long-term US contract, links pricing to both Henry Hub and TTF indices to reduce European price volatility exposure. It will cover roughly 40% of residential gas demand. Read →
Regulation & Government
What's moving · US diesel export ban talk and White House pushback drive Regulation & Government moves amid record prices.
Wright seeks voluntary diesel export curbs from refiners
Reuters · Thu, Sep 24, 10:59 AM ET
Energy Secretary Chris Wright contacted major U.S. refiners to gauge support for voluntary restrictions on diesel exports as an alternative to a ban. The U.S. is the world's largest diesel exporter, and industry groups including the American Petroleum Institute warned restrictions could force refiners to cut runs and raise prices for gasoline and jet fuel. Diesel prices at $6.52/gallon add political pressure ahead of November midterms. Read →
Serbia seeks new US sanctions waiver for NIS refinery
Reuters · Thu, Sep 24, 8:26 AM ET
Serbia's Russian-owned NIS, operator of the country's only oil refinery supplying up to 80% of fuel needs, applied for a new U.S. sanctions waiver after the current one expires September 30. The waiver would allow continued crude imports until a planned sale of the Russian stake (held by Gazprom and Gazprom Neft) to Hungary's MOL. OFAC imposed sanctions last October over Russian ownership tied to the Ukraine war. Read →
What traders and commodity market feeds are talking about
Dated Brent hits $125 physical premium amid Iran standoff
X / multiple traders · Thu, Sep 24
Traders highlight Dated Brent cash premium surging to +$18/bbl over futures and WTI roll near $6/bbl. Physical tightness in Gulf markets signals real supply constraints from regional tensions. Discussions focus on how paper prices lag physical reality in a geopolitically charged market. Read →
Oil, freight, refined products hit records on fundamentals
X / @UnintendedCons5 · Thu, Sep 24
Posts note oil prices near records alongside record freight rates and delivered/refined product prices. Emphasis on fundamentals mattering over headlines. Traders see sustained tightness in energy logistics and product markets. Read →
Iran warns of $6.5 diesel, $4.5 gas as retaliation
X / multiple traders · Thu, Sep 24
Iranian official's comments on returning US to 1970s rates plus fuel shortages spark trader debate on diesel and gas price ceilings. Quant views suggest floors could be much higher amid AI-driven demand. #OOTT community discusses escalation risks to refined products. Read →
r/oil debates Hormuz deal hopes vs escalation risks
r/oil · Thu, Sep 24
Retail traders in daily oil thread discuss Iran threats, contract rollover, and Hormuz control signals. Skepticism over any quick deal dominates after recent news spikes and drops. Focus on how diplomacy news repeatedly whipsaws prices without resolving underlying tensions. Read →
EU methane regs threaten Repsol crude supplies
X / @staunovo · Thu, Sep 24
Analyst flags Repsol warning that 90% of its crude could breach new EU methane rules from January. Industry pushback highlights potential energy supply threats. #OOTT sees this as another layer of regulatory pressure on European oil flows. Read →
Recent video and podcast calls from respected oil and commodity analysts
Citi: Super El Niño top ag risk
Super El Niño is the highest-conviction agricultural risk. Watch/Listen →
Kpler: Oil back on edge above $105
Oil should be much higher than current levels. Watch/Listen →
Kpler's Bakr on energy security at Gastech
Energy security requires continued investment in both traditional and low-carbon sources. Watch/Listen →
Where commodity traders watch asymmetric risk · live odds via Polymarket
Hormuz Crisis
US-Iran tensions disrupting Strait of Hormuz oil flows. Polymarket odds, last 7 days.
Hormuz traffic returns to normal by December 31
23%
+6pp w/w
US-Iran ceasefire holds through October 31
57%
+1pp w/w
Saudi East-West oil pipeline restarts by October 15
60%
+15pp w/w
Source: Polymarket
US Diesel Export Ban
Would cut US distillate exports, widen the US-Europe diesel spread and hit Gulf Coast refining margins. Polymarket odds, last 7 days.
US announces a diesel export ban by October 31
12%
-8pp w/w
Source: Polymarket
Red Sea / Bab el-Mandeb
Houthi threat to Red Sea shipping; a closure reroutes tankers and LNG around the Cape. Polymarket odds, last 7 days.
Bab el-Mandeb effectively closed by December 31
18%
-1pp w/w
Source: Polymarket
Fed Policy
Fed rate decisions move USD strength and industrial energy demand expectations. Polymarket odds, last 7 days.
Fed hikes 25 bps at the October meeting
67%
+16pp w/w
US recession by end of 2026
12%
+3pp w/w
Source: Polymarket
Russia / Ukraine Energy
A ceasefire would shift Russian crude and product flows and European gas pricing. Polymarket odds, last 7 days.
Russia-Ukraine ceasefire agreement by December 31
22%
-1pp w/w
Source: Polymarket
Was this forwarded to you? Subscribe free →
Hedge smarter, not harder.
This newsletter is brought to you by BoxWood · The AI-powered programmatic hedge booking system for commodity producers, consumers, refiners, hedge funds, and trading houses. See a live demo →
Morgan Downey's Commodity News is published by Wooden Table Press LLC. Curated and rewritten from public sources; every story links to its original publisher. Informational only · not financial, investment or trading advice.
Unsubscribe · View in browser · Subscribe
One sponsor per issue. Ask us about a future month →
Unsubscribe · View in browser · Subscribe