The gen alpha daily zeitgeist of the physical commodity world
Oil · Gas · NGLs · Power · Coal · Ags · Metals · Fertilizers · Rare Earths · Shipping · Environment · RWA · Podcast · Street views · Archive
Friday, November 20, 2026
Prefer audio only? Listen here.
Prefer longer? Listen to the 7-minute version.
Markets at a glance
Charts: grey is the prior session, color is today.
Macro
|
S&P 500 Fut
7,166
-0.4%
-31 |
Dollar Index
103.87
-0.02%
-0.02 |
EUR/USD
1.0966
-0.06%
-0.0007 |
US 10Y Yield
5.052
-1.4 bp
|
Last price as of Fri, Nov 20, 5:34 AM ET. Click price for news.
Downey's Take
Crude down $1.65 (-2%) on oversupply narrative and weak macro. This will be the third straight weekly loss (roughly 5% for Brent and 8% for WTI this week alone).
Trump said Thursday in relation to Iran “Well, I’ll talk to you about it after the beginning of the year.” He added, “We’ve got time.” He has used similar deflection since Feb ahead of imminent action.
A flotilla of 14+ oil tankers are currently positioned at Kharg Island, Iran’s primary crude export terminal. Tehran plans to send them in a convoy toward the Sea of Oman in the coming days in an attempt to break or challenge the US blockade on Iranian ports. No Iranian crude tankers have successfully ran the blockade since it was imposed in July.
Silver down $1.99 (-4%) on hawkish Fed rate-hike expectations and stronger dollar.
JKM Asian LNG up $1.02 (+4%) on Middle East supply disruptions tightening Asian spot market.
Tin down $1450 (-3%) on Fed rate-hike bets and AI-trade unwind pressuring industrial metals.
Platinum down $43 (-3%) on hawkish Fed signals and weaker automotive demand outlook.
Gold down $104 (-3%) on hawkish Fed rate expectations, stronger dollar and forced liquidation from AI-equity selloff.
Trump said Thursday in relation to Iran “Well, I’ll talk to you about it after the beginning of the year.” He added, “We’ve got time.” He has used similar deflection since Feb ahead of imminent action.
A flotilla of 14+ oil tankers are currently positioned at Kharg Island, Iran’s primary crude export terminal. Tehran plans to send them in a convoy toward the Sea of Oman in the coming days in an attempt to break or challenge the US blockade on Iranian ports. No Iranian crude tankers have successfully ran the blockade since it was imposed in July.
Silver down $1.99 (-4%) on hawkish Fed rate-hike expectations and stronger dollar.
JKM Asian LNG up $1.02 (+4%) on Middle East supply disruptions tightening Asian spot market.
Tin down $1450 (-3%) on Fed rate-hike bets and AI-trade unwind pressuring industrial metals.
Platinum down $43 (-3%) on hawkish Fed signals and weaker automotive demand outlook.
Gold down $104 (-3%) on hawkish Fed rate expectations, stronger dollar and forced liquidation from AI-equity selloff.
Drivers are sourced from third-party news and bank or desk commentary. Informational only, not trade advice.
Street Commodity Views
UBS (Thu Nov 19) recommends long-term allocation to gold on central bank buying and diversification despite near-term headwinds.
Westpac (Fri Nov 20) sees Brent averaging US$101/bbl in Q4 2026 then easing to US$77/bbl in Q4 2027 on recovering supply.
Saxo Bank (Thu Nov 19) sees gold and silver under pressure from rising yields, dollar strength and tightening liquidity.
Dated views from banks and research houses, as published; houses change them without notice. Informational only, not trading advice. Past views by commodity and house →
The marquee commodity stories of the day
China pulls copper from US stockpiles amid squeeze
Traders are booking shipments of copper from massive US stockpiles to China as a historic short squeeze tightens physical supplies in the world's top consumer, with logistics firms reporting a surge in inquiries and several cargoes already secured. Read →
BHP investor tour spotlights copper growth plans
Rhiannon Hoyle · Wall Street Journal · Thu, Nov 19, 2026 · Share
The world's most valuable miner begins a two-day tour of its Australian copper operations Monday to demonstrate delivery on expansion plans as demand for the metal surges from data centers and other sectors, a year after dropping its Anglo American bid. Read →
EU delays methane rules on fossil fuel imports
Ian Johnston · Financial Times · Thu, Nov 19, 2026 · Share
The EU has agreed to delay by at least two years implementation of stricter methane monitoring and reporting rules for oil and gas imports after lobbying by the US, Qatar and the industry, with possible further postponements tied to compliance conditions. Read →
Gold loses lustre amid tech stock selloff
Financial Times · Thu, Nov 19, 2026 · Share
The precious metal, long seen as a portfolio diversifier, has failed to provide protection during the recent tech stock decline as investors rotate away amid shifting risk sentiment and other market pressures. Read →
Palm oil rally to squeeze food producers
Financial Times · Thu, Nov 19, 2026 · Share
Rising palm oil prices driven by biodiesel demand and supply constraints will boost earnings for producers while pressuring margins at large consumer goods companies reliant on the commodity. Read →
Most clicked yesterday
In this issue · tap a section to jump to it
Oil 5US Nat Gas 4NGL/LPG & Petchems 3Global Nat Gas & LNG 3Power 2Coal 3Agriculture 3Fertilizers 3Base Metals 3Iron Ore & Steel 2Precious Metals 3Rare Earths & Critical Minerals 2Shipping & Freight 2Environment 2On-Chain Commodities 2Companies said 4Corporate & Deals 3Regulation & Government 3Social buzz 5Podcasts 2Prediction Markets
Markets News
| Oil | Oil 101 |
What's moving · Ample Middle East exports and US inventory builds drive oil toward third straight weekly decline despite Hormuz tanker attacks.
| Physical cash | Last 1D | Cash vs futures |
|---|---|---|
| WTI |
85.36 -1.63 | +3.77 backwardation, tight |
| Brent |
91.59 -1.66 | +3.65 DFL, backwardation, tight |
| Brent minus WTI | 6.22 -0.03 |
Cash from WetBarrels.com. Cash vs futures is cash minus the first futures month; for Brent, Dated to frontline (DFL). Above zero is backwardation. In physical terms backwardation is a tight market, contango a loose one, and a kink or flat curve a balanced one.
| Futures | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| WTI Crude Dec 2026 |
81.59 | -1.9% -1.62 |
+41.3% | +39.8% | +5.7% |
| Brent Jan 2027 |
90.33 | -1.8% -1.65 |
+44.5% | +40.6% | +10.3% |
| RBOB Gasoline Dec 2026 |
2.470 | -1.0% -0.025 |
+43.2% | +29.7% | +8.1% |
| Heating Oil Dec 2026 |
3.933 | -0.5% -0.018 |
+81.1% | +56.4% | +65.2% |
| RBOB Crk $/bbl |
22.14 | +2.6% +0.55 |
+50.6% +7.44 |
+2.4% +0.52 |
+17.6% +3.31 |
| NY HO Crk $/bbl |
83.59 | +1.0% +0.84 |
+150% +50.12 |
+76.9% +36.33 |
+266% +60.75 |
| NY 321 Crack $/bbl |
42.62 | +1.5% +0.65 |
+103% +21.67 |
+41.3% +12.46 |
+111% +22.46 |
Oil heads for third weekly drop on strong Mideast exports.
Brent fell 1% to $91.03/bbl and December WTI dropped 1.7% to $81.81/bbl on Friday amid robust Saudi and Gulf crude shipments that have returned near pre-war levels. Strong exports outweigh Houthi strikes on Riyadh and ongoing tanker incidents in the Strait of Hormuz, pushing both benchmarks toward 5% and nearly 8% weekly losses respectively. Read →
Oil set for third weekly drop as supply outweighs war risk.
Brent traded above $92/bbl and WTI near $83/bbl after Thursday's session but face a third consecutive weekly decline as Middle East supplies recover rapidly. Trump signaled no rush on new Iran strikes while US Energy Secretary Wright highlighted record Hormuz flows; IEA sees a 2 mb/d surplus this quarter and Goldman flags a 2027 glut. Read →
Oil on track for third weekly decline despite Mideast tension.
Fareed Rahman · The National · Fri, Nov 20, 2026 · Share
Brent traded 1.34% lower at $90.75/bbl and WTI down 1.2% at $81.36/bbl on Friday, on pace for losses exceeding 3% and 6% this week. Houthi missile strikes hit a Riyadh PIF tower and Iranian attacks continued in the Strait of Hormuz, including an Adnoc vessel hit injuring 11 crew; IEA reported markets returned to surplus with 1.7 mb/d inventory rise in October as Gulf exports recovered faster than demand. Read →
China may not boost fuel exports despite US-Russia pact.
US, China and Russia leaders agreed Thursday in Shenzhen to increase refined product supplies like diesel and gasoline for global benefit, but analysts doubt Beijing will act quickly despite having spare refining capacity. The pledge follows recovering Middle East crude flows and adds to bearish sentiment on refined product balances amid expected surpluses. Read →
Oil gains as Houthi Riyadh attacks raise supply concerns.
Brent rose 0.9% to $92.77/bbl and WTI gained 0.3% to $83.46/bbl early Friday after Houthi strikes on Riyadh revived near-term supply worries. Tanker incidents in Hormuz and one-per-day attack pace add a geopolitical premium, though strong export flows and surplus forecasts still cap gains ahead of OPEC+ meetings on November 29. Read →
Charts of the day
| 1 | SPR falls to 276.4M barrels chartvia @KobeissiLetter on X · 1.2k likesChart of SPR inventory drop to 276.4M barrels, lowest since Aug 1982, down 34% since March |
| 2 | US 10Y yield vs debt rollover costsvia @ekwufinance on X · 742 likes |
| 3 | NAND flash memory prices 2022-2026via @BurggrabenH on X · 172 likes |
Check out Oil 101.
| US Natural Gas | NatGas 101 |
What's moving · Record 21.2 Bcf/d US LNG feedgas and FERC-approved Sabine Pass expansion lift futures despite mild weather and 20 Bcf storage build.
| Physical cash | Last 1D | |
|---|---|---|
| Henry Hub |
3.231 -0.076 | +0.045 kink, balanced |
Cash from WetBarrels.com.
| Futures | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Henry Hub Dec 2026 |
3.186 | -2.5% -0.082 |
-2.5% | -21.6% | -25.0% |
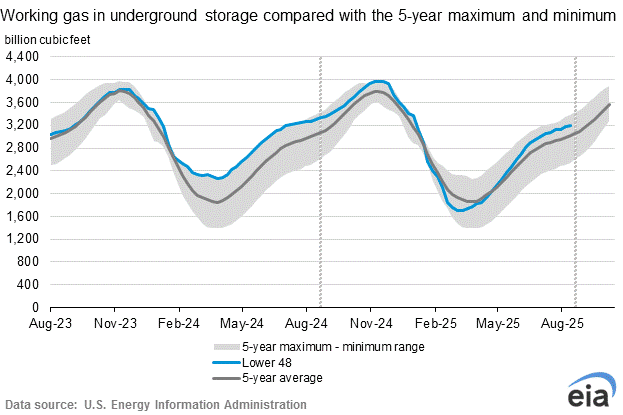
EIA gas storage · week ending Fri, Nov 13
A 20 Bcf injection took working gas to 3,882 Bcf, 80 Bcf (2%) above the five-year average and 66 Bcf below a year ago.
Working gas 3,882 Bcf +20 Bcf w/w | Year ago 3,948 Bcf | 5-yr avg 3,802 Bcf |
Consensus – this week | Year-ago chg -14 Bcf | 5-yr avg chg +27 Bcf |
Source: EIA Weekly Natural Gas Storage Report · Full EIA report →
US LNG feedgas hits record 21.2 Bcf/d Sunday
Jacob Dick · Natural Gas Intelligence · Thu, Nov 19, 2026 · Share
US LNG feedgas nominations reached 21.2 Bcf/d on Sunday, the highest level in NGI’s Entropic Analytics data since January 2025. Europe took a larger share of cargoes while Sabine Pass and other terminals ramped. Record feedgas demand supports near-term Henry Hub prices amid high export flows. Read →
FERC approves Cheniere Sabine Pass expansion
Jacob Dick · Natural Gas Intelligence · Thu, Nov 19, 2026 · Share
FERC approved Cheniere’s plan to add three liquefaction trains at Sabine Pass LNG, boosting capacity by about 19 to 20 Mt/y, plus Creole Trail and Sabine Crossing pipeline expansions. The approval advances the project toward FID and will require additional feedgas supply from the Gulf Coast over time. Read →
Mexico pipeline exports average 7.41 Bcf/d in Oct
Christopher Lenton · Natural Gas Intelligence · Thu, Nov 19, 2026 · Share
US pipeline exports to Mexico averaged 7.41 Bcf/d in October, up 7.6% year/year despite an outage at the Altamira LNG facility. Strong cross-border demand adds to domestic and LNG pull on Lower 48 supplies. Read →
EIA reports 20 Bcf storage injection for week ended Nov 13
Kevin Dobbs · Natural Gas Intelligence · Thu, Nov 19, 2026 · Share
EIA reported a 20 Bcf injection into Lower 48 storage for the week ended Nov. 13, below analyst expectations but above the five-year average. Inventories stood at 3,882 Bcf, 80 Bcf above the five-year norm and 66 Bcf below year-ago levels; futures gave back gains on the data. Read →
Check out NatGas 101.
Sponsored · Kpler
How much oil is moving, in real time
With Hormuz and the Red Sea redrawing trade routes minute by minute, you need the quickest, most reliable source of truth. Kpler tracks commodity cargoes and the vessels carrying them. You can see exports, imports, floating storage and more as they develop in real time.
Kpler covers oil, products, gas, and dry bulk. Pair flows with refinery runs, inventories and freight analytics, and the story behind a price move becomes visible before the market has priced it in.
| Wet Gas, NGLs/LPGs & Petchems | Commodities 101 |
What's moving · US propane stocks hold flat vs expected 1 MMbbl draw as strong production and softer exports keep supply ample heading into winter.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Ethane C2 $/gal |
0.287 | -0.1% -0.000 |
+21.2% | +7.6% | -28.6% |
| Propane C3 $/gal |
1.072 | +0.5% +0.005 |
+73.8% | +65.4% | -14.3% |
| N-Butane NC4 $/gal |
1.708 | +0.6% +0.010 |
+129% | +97.0% | +17.5% |
| Isobutane IC4 $/gal |
1.703 | +0.8% +0.014 |
+119% | +90.0% | +17.0% |
| Pentane C5 $/gal |
1.898 | +0.3% +0.006 |
+61.9% | +51.9% | +3.3% |
| Spread | Now | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| C2 Frac Sprd ¢/gal | 8 | +1 | +6 | +8 | -5 |
| C3 Frac Sprd ¢/gal | 78 | +1 | +46 | +50 | -8 |
| C2 vs NWE Naph $/mt | -578 | unch | -273 | -252 | -155 |
| C3 vs NWE Naph $/mt | -242 | +3 | -75 | -47 | -159 |
| C5 as % WTI | 98 | +2 | +12 | +8 | -2 |
Mont Belvieu front-month settlement. Frac spread is the liquid over Henry Hub fuel value; naphtha spreads are before freight.
US propane stocks flat vs expected draw on strong output, softer exports.
Christine Groenewold · RBN Energy · Wed, Nov 18, 2026 · Share
US propane/propylene inventories edged up 12 Mbbl to 104.2 MMbbl for the week ended Nov 13, defying the typical 688 Mbbl seasonal draw. Strong production at 2,967 Mb/d and exports slipping 210 Mb/d to 1,962 Mb/d offset rising domestic demand of 1,140 Mb/d. Midwest stocks built 488 Mbbl to 25.1 MMbbl, easing tightness there while the national surplus remains concentrated on the Gulf Coast. Read →
Propane storage surplus evaporates faster than expected into winter.
Adam Baker · RBN Energy · Thu, Nov 19, 2026 · Share
US propane inventories hit an all-time high of 109 MMbbl in late August but fell to just 2 MMbbl above year-ago levels by end-October, on track to erase the surplus by year-end. Record storage followed by early October withdrawals deviates from the normal build-season pattern of +5.1 MMbbl on average from August through October. The shift tightens balances heading into 2027 winter demand. Read →
Targa sanctions Train 14 frac at Mont Belvieu for Q1 2029 startup.
Efrain Garcia · Allstream Insiders · Wed, Nov 18, 2026 · Share
Targa Resources sanctioned a new 150 Mb/d NGL fractionator Train 14 at Mont Belvieu targeted for Q1 2029 operations, lifting its hub capacity toward 1.8 MMb/d. The company also ordered long-lead items for one potential Midland and two Delaware Permian gas plants likely needed in 2028-early 2029. Train 12 and Bull Run Extension started ahead of schedule in Q4 2026 amid record Permian gas volumes. Read →
Check out Commodities 101: NGLs section.
| Global Nat Gas & LNG | NatGas 101 |
What's moving · TTF rebounds to €86/MWh on Norway Troll maintenance, colder forecasts and Hormuz risk after 12% drop.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Dutch TTF €/MWh |
85.82 | +1.6% +1.36 |
+200% | +180% | +0.5% |
| Dutch TTF $/MMBtu |
27.58 | +1.6% +0.44 |
+200% | +180% | +0.5% |
| JKM $/MMBtu |
27.52 | +3.9% +1.02 |
+187% | +140% | -19.0% |
EU gas storage · gas day Wed, Nov 18
EU gas storage is 69.8% full, 791 TWh in store, 17.9 points below the five-year average for this date and 11.3 points below a year ago. Germany, the bloc's largest store, is 57.1%, 30.4 points below its five-year average and 16.5 points below a year ago. LNG terminals are 52.1% full and sent out 4,054 GWh, 1% more than the day before.
EU full 69.8% -0.12 pts d/d | Year ago 81.2% | 5-yr avg 87.7% same date |
Germany 57.1% | Year ago 73.7% | 5-yr avg 87.6% same date |
Source: GIE AGSI+ and ALSI+ · Full AGSI+ data →
TTF drops 12% on fading war premium, mild weather, strong US LNG.
Seb Kennedy · Energy Flux · Thu, Nov 20, 2026 · Share
Dutch TTF front-month fell 12.4% over four sessions to €80.85/MWh Wednesday on shrinking geopolitical premium, milder European weather forecasts and record US LNG feedgas plus Troll field recovery. Thursday saw a 5% bounce to around €86 as Troll maintenance cut output 50 mcm/d, Åsgard field dipped unexpectedly, colder forecasts returned and reports of possible new US strikes on Iran resurfaced. The moves highlight TTF's sensitivity to Norwegian pipeline flows, weather-driven demand and Middle East LNG transit risks amid low EU storage. Read →
Orlen, QatarEnergy discuss new LNG supply deal post-termination.
Poland's Orlen and QatarEnergy began preliminary talks for a new long-term LNG contract days after Orlen ended a decades-old deal due to delivery issues amid Hormuz disruptions. Discussions cover roughly 1 mtpa at potentially better pricing, with US-sourced LNG also considered as Orlen seeks diversification beyond its heavy US reliance. Any deal would help replace lost Qatari volumes critical for European and Asian spot markets. Read →
US LNG exporters gain comfort on EU methane rule delay.
EU lawmakers agreed a further 12-month delay to methane emissions reporting rules for importers, citing energy market disruption from the Iran conflict. Center for LNG's Charlie Riedl said the move eases exporter concerns and supports long-term US LNG contracts with Europe. The US has become Europe's top LNG supplier and the delay aids future deal flow. Read →
Check out NatGas 101: LNG section.
| Power | Power 101 |
What's moving · FERC orders PJM to create co-location rules for data centers at power plants, aiming to speed AI load connections.
FERC orders PJM co-location rules for AI data centers.
Federal Energy Regulatory Commission · Thu, Nov 19, 2026 · Share
FERC unanimously directed PJM to revise its tariff with transparent rules for co-locating large loads like AI data centers with generating facilities, addressing unjust and unreasonable terms on transmission service and withdrawals. The order combines prior proceedings and requires PJM and transmission owners to respond within 30 days on why the tariff is just or propose fixes. This targets bottlenecks for data center investments across PJM's 13-state footprint while protecting reliability and consumers. Read →
Five ISOs file large-load tariff reforms at FERC.
POWER Magazine · Thu, Nov 19, 2026 · Share
PJM, MISO, NYISO, CAISO, and ISO-NE filed tariff reforms to FERC for integrating data centers and large loads, including PJM's Fast Energization Process consolidating studies into a 12-month cycle and ride-through rules for 50 MW+ computational loads. Other operators proposed mechanisms using wholesale prices to trigger load reductions. Filings respond to FERC show-cause orders on interconnection procedures, cost allocation, and reliability for surging demand. Read →
Check out Power 101.
| Coal | Commodities 101 |
What's moving · China coking coal futures hit three-month low at 1,346 yuan/t as Shanxi mine restarts ease supply squeeze.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| API2 Rotterdam $/t backwardation |
132.25 | +0.4% +0.50 |
+35.7% | +37.6% | -8.2% |
| Newcastle $/t backwardation |
144.65 | +1.9% +2.75 |
+36.8% | +27.1% | -8.4% |
China coking coal hits three-month low on supply recovery
Tsvetana Paraskova · OilPrice.com · Wed, Nov 19, 2026 · Share
Dalian coking coal futures fell for a fourth session to 1,346 yuan ($201.90) per ton, the lowest since mid-August. Recovering domestic supply from Shanxi mine restarts and weak steelmaking demand drove the decline. The move eases pressure on seaborne metallurgical coal premiums and Indian steel margins. Read →
China coking coal prices hit three-month low as supply recovers
Dalian futures dropped as much as 1.3% to 1,346 yuan per ton amid rising domestic supply and weak steel demand. Prices have retreated one-fifth from the August peak. The decline signals looser conditions for metallurgical coal ahead of winter restocking. Read →
India power demand up 11.7% with coal stocks at 7.6 days
India’s electricity demand rose 11.7% year-on-year through October while thermal plant coal stocks stood at just 7.6 days versus a 19 to 20 day norm. Low inventories support potential import demand despite domestic production gains. The situation underscores tight supply conditions for thermal coal in the key Asian buyer. Read →
Check out Commodities 101: coal section.
| Agriculture | Commodities 101 |
What's moving · Corn, wheat rebound on USDA export sales and dollar easing while soybeans slip.
| Futures | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Corn Mar 2027 |
450 | -0.5% -2 |
+2.3% | +5.8% | -21.9% |
| Wheat Mar 2027 |
595 | -0.0% -0 |
+17.3% | +12.9% | -29.7% |
| Soybeans Jan 2027 |
1,209 | +0.1% +2 |
+17.3% | +7.5% | -5.1% |
| Sugar Mar 2027 |
17.13 | -0.2% -0.03 |
+14.1% | +15.9% | -13.3% |
| Coffee Dec 2026 |
277.1 | -1.8% -4.9 |
-20.5% | -30.7% | +19.8% |
| Cocoa Dec 2026 |
4,996 | -1.3% -67 |
-17.6% | -1.7% | +100% |
| Cotton Mar 2027 |
79.38 | -0.2% -0.13 |
+23.9% | +29.8% | -32.4% |
Corn futures rebound on export data and technical buying
Ben Potter · Farm Progress · Thu, Nov 19, 2026 · Share
December corn futures rose 3.5 cents to $4.39 per bushel on Thursday after Wednesday's selloff. USDA export sales for the week ending Nov. 12 showed 1.59 million metric tons of corn, within expectations despite a 45% week-over-week drop. Shipments hit 37.1 million bushels, up 17% from the prior four-week average, with Mexico as top buyer; the rebound reflects bargain buying amid a firmer dollar and South American crop prospects. Read →
Wheat and corn futures recover after broad commodity selloff
Anthony Harrup · Dow Jones / MarketScreener · Thu, Nov 19, 2026 · Share
December wheat rose 1.4% to $5.78 1/4 per bushel and corn gained 0.8% to $4.39 on Thursday as grains bounced from Wednesday's selloff. USDA reported wheat sales of 344,800 metric tons (up 89% week-over-week) and a private flash sale of 200,844 metric tons of soybeans to Mexico. Analysts noted the dollar's recent highs and strong South American growing conditions continue to cap upside despite the technical recovery. Read →
Corn export sales fall 45% as soybean sales rise 30%
Feed & Grain · Thu, Nov 19, 2026 · Share
USDA's weekly export sales report for the week ending Nov. 12 showed U.S. corn net sales at 1.588 million metric tons, down 45% from the prior week and 9% below the four-week average. Soybean sales rose 30% to 1.501 million metric tons while wheat sales jumped 89% to 344,800 metric tons. Mexico led corn purchases at 926,300 metric tons; China bought 580,700 metric tons of soybeans, keeping totals within analyst ranges. Read →
Check out Commodities 101: agriculture section.
| Fertilizers | Commodities 101 |
What's moving · Nitrogen split widens as ammonia/UAN hold firm on forward sales while urea eases on Chinese exports and Hormuz flows.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Urea | |||||
| China (ZCE) CNY/t |
1,711 | +0.6% +11 |
-2.2% | +2.8% | -21.7% |
| Brazil CFR $/t |
466.00 | -0.2% -1.00 |
+14.4% | +13.0% | -45.3% |
| US Gulf FOB $/st |
420.00 | +0.0% +0.00 |
+8.6% | +9.2% | -46.0% |
| DAP | |||||
| NOLA FOB $/st |
790.00 | +0.0% +0.00 |
+26.4% | +9.0% | +10.1% |
The 5Y column starts from the October 2021 peak, when the European gas crisis shut ammonia plants and China halted urea exports. Daily settles; these contracts barely trade, so flat days are common.
Cold snap lifts U.S. natural gas demand and prices
Forecasters expect a sharp cold snap across the U.S. Midwest and Northeast this weekend that will push heating demand higher. Natural gas futures rose more than 4% on the outlook. Higher feedstock costs immediately pressure ammonia and urea margins at Gulf Coast plants. Read →
India issues new urea import tender for December-January
Argus Media · Thu, Nov 20, 2026 · Share
India’s state trading arm floated a fresh tender for 1.2 million tonnes of urea for December and January delivery. Traders say the timing overlaps with expected Middle East export windows. The tender sets the immediate benchmark for NOLA and global urea pricing. Read →
CF Industries boosts Donaldsonville ammonia output
CF Industries said its Donaldsonville complex returned to full rates following a brief turnaround. Ammonia production volumes rose 12% month-on-month in the latest week. The increase adds near-term supply to the U.S. nitrogen market and caps upside in ammonia prices. Read →
Check out Commodities 101: fertilizer section.
| Base Metals | Commodities 101 |
What's moving · Copper futures slump on AI trade unwind while China physical premiums hit records and draw US metal.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Copper NY $/mt contango |
12,259 | -1.3% -161 |
-1.2% | +11.0% | +26.5% |
| Copper SHFE $/mt backwardation |
12,737 | -2.1% -280 |
+0.3% | +17.8% | +30.5% |
| Aluminium SHFE $/mt backwardation |
2,912 | +0.3% +9 |
-2.2% | +9.1% | +4.8% |
| Zinc SHFE $/mt backwardation |
3,200 | -0.8% -25 |
+6.5% | +14.7% | -4.1% |
| Nickel SHFE $/mt contango |
15,577 | -2.0% -311 |
-8.0% | +3.9% | -22.4% |
| Lead SHFE $/mt backwardation |
2,100 | +0.1% +3 |
-4.7% | -2.8% | -3.5% |
| Tin SHFE $/mt backwardation |
42,497 | -3.3% -1,450 |
+1.2% | +19.9% | +8.2% |
Copper rout deepens on AI selloff and demand doubts
Copper on the LME fell as much as 4% to its lowest since March on Thursday, extending a week of heavy selling that puts it on track for one of its worst weeks in a decade. The decline stems from unwinding of bullish positions tied to artificial intelligence spending and broader doubts about global demand. The selloff hit even as physical tightness persists in China, the top consumer. Read →
Funds sell copper as Shanghai stocks near exhaustion
LME three-month copper slumped 6% to a seven-month low of $12,379.50/t on Wednesday as funds unwound AI-linked bets amid a stronger dollar. In contrast, Shanghai Futures Exchange deliverable stocks collapsed to 27,642 tons, with just 2,270 tons available for November settlement, driving the Yangshan import premium to a record $360/t over LME. The disconnect shows fractured physical markets, with China facing genuine tightness while financial positions dominate price action. Read →
Kenya awards Mrima Hill rare earths to US group
Kenya selected Frontier Minerals Consortium, including ReElement Technologies and American Resources, to develop the Mrima Hill deposit estimated at tens of billions of dollars in rare earths and niobium. The award advances US efforts to diversify critical minerals supply away from China dominance and requires local processing commitments. Rival bidders plan challenges, but the deal signals growing competition for energy-transition metals. Read →
Check out Commodities 101: base metals section.
| Iron Ore & Steel | Commodities 101 |
What's moving · Port iron ore stocks dip 0.9% to 176Mt on firmer outflows as DCE futures hover near 4-year lows amid weak steel demand.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Iron Ore 62% DCE $/dmt backwardation |
86.5 | +0.6% +0.5 |
-14.0% | -11.8% | -0.3% |
| Rebar SHFE $/mt backwardation |
401 | +0.6% +3 |
+1.9% | +4.5% | -36.8% |
| HRC SHFE $/mt contango |
407 | +0.3% +1 |
-1.3% | -0.8% | -40.2% |
China iron ore port stocks dip 0.9% to 176Mt
Mysteel's survey of 47 major Chinese ports showed imported iron ore inventories fell 1.6Mt or 0.9% week-on-week to 176Mt as of Nov 19 after three weeks of rises, driven by stronger port outflows. This follows earlier builds amid falling blast-furnace output and environmental curbs in northern China. Lower stocks ease some immediate oversupply pressure but highlight persistent weak mill demand tied to thin steel margins and soft property/infrastructure activity. Read →
Iron ore breaks below $90 as port stocks build
Shanghai Metals Market (SMM) · Thu, Nov 20, 2026 · Share
SGX iron ore futures fell 2.43% week-on-week to $88.40/mt while DCE I2701 dropped 3.43% to 648 yuan/mt, with the onshore discount widening. Stocks at 35 ports rose to 153.75Mt amid building inventories and falling hot-metal output; funds added shorts. The moves underscore how rising port stocks and weak Chinese steel demand are pressuring prices, with SGX expected to trade in a $86 to 90/mt range. Read →
Check out Commodities 101: steel section.
| Precious Metals | Commodities 101 |
What's moving · Hawkish Fed rate-hike bets and firm dollar drive gold to worst week in eight months, with silver, platinum and palladium also sliding.
| Futures | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Gold Dec 2026 |
3,582 | -2.8% -104 |
-17.5% | -12.2% | +98.3% |
| Silver Dec 2026 |
42.37 | -4.5% -1.99 |
-39.6% | -15.0% | +74.5% |
| Platinum Jan 2027 |
1,305 | -3.2% -43 |
-35.9% | -13.8% | +28.7% |
| Palladium Dec 2026 |
901 | -1.9% -18 |
-44.7% | -34.9% | -53.8% |
Gold heads for worst week in eight months on dollar and Fed hike bets
Spot gold fell 1.9% to $3,552.39/oz Friday after hitting its lowest since September 2025, on track for an 8.5% weekly drop, the sharpest since March. Markets price a 99.3% chance of a December 25bp Fed rate hike; higher rates raise bullion's opportunity cost. Silver fell 2.4% to $41.73/oz, platinum 3.1% to $1,302.45/oz and palladium 2.5% to $886.86/oz, all heading for weekly losses. Read →
Gold on track for worst week since March amid hawkish Fed and AI rout
Gold tumbled as much as 3.1% below $3,515/oz Friday, on pace for nearly 9% weekly losses and its lowest level since September 2025. Chicago Fed President Austan Goolsbee and other officials signaled further rate hikes to combat inflation; investors sold bullion to cover AI-stock losses. Silver has fallen about 14% over the same period. Read →
Central banks bought 321t gold in Q3, up 42% y/y
ad-hoc-news.de / World Gold Council data · Fri, Nov 20, 2026 · Share
World Gold Council data show central banks and official institutions added a net 321 tonnes in Q3 2026, a 42% rise from a year earlier, lifting nine-month purchases to 675t (+6% y/y). China added 26t in October, its largest monthly increase since October 2023, while Poland led year-to-date buying. Official accumulation contrasts with recent ETF outflows and provides a floor under prices amid the selloff. Read →
Check out Commodities 101: gold section.
| Rare Earths & Critical Minerals | Commodities 101 |
What's moving · China extends rare-earth export-control suspension to Jan 10 2027 while antimony mine halts and India advances magnet plants.
China extends rare earth export suspension to Jan 10 2027
China's Ministry of Commerce extended the suspension of six October 2025 export-control measures on rare earths, lithium batteries and graphite anode materials from Nov 11 2026 to Jan 10 2027. The move continues a bilateral trade truce with the US and keeps the April 2025 licensing regime for seven medium and heavy rare earths in force. It delays tighter curbs that would have resumed next week and preserves current export flows. Read →
India picks four firms for 6,000 t rare earth magnet plants
The Economic Times · Fri, Nov 20, 12:00 AM ET · Share
India's Heavy Industries Ministry issued letters of intent to Coal India, ReNew, Prozeal Green Energy and Midwest Energy under a ₹7,280 crore scheme to build 6,000 tonnes per year of sintered rare-earth permanent magnet capacity. The program offers ₹6,450 crore in sales-linked incentives and ₹750 crore in capital subsidies over five years. The projects target EV motors, wind turbines and defence applications to cut reliance on Chinese imports. Read →
Check out Commodities 101: rare earths section.
| Shipping & Freight | Commodities 101 |
What's moving · BDI slips 0.5% to 2,901 as Capesize rates ease after recent gains; VLCC rates down sharply.
Maersk, Hapag-Lloyd resume more Suez services.
Maersk and Hapag-Lloyd redirected ME1 India-Europe service via Suez in November and announced NE1, NE2, NE3 Gemini services will follow from December 2026 into January 2027. The phased return cuts transit times versus Cape routing for Asia-Europe cargoes while carriers monitor Red Sea security. Read →
COSCO orders 16 dual-fuel VLCCs for $2B.
COSCO Shipping Development contracted 16 307,000 DWT methanol- and LNG-ready VLCCs from China State Shipbuilding for about $2.01 billion, with deliveries late 2029 to 2030. The vessels will be bareboat chartered long-term to an affiliate of COSCO Shipping Energy, expanding the group's tanker fleet. Read →
Check out Commodities 101: shipping section.
| Environment | Commodities 101 |
What's moving · EUAs drop to €81.31/t on Nov 19 auction amid reform talks and energy weakness.
EU carbon price falls 5% on reform talks
The benchmark EU Allowance contract fell more than 5% to trade around €82.95/t, hitting an intraday low of €82.63/t. The drop came as the European Parliament signaled it would not accept steeper than 4% post-2030 emissions cap cuts during ongoing ETS reform talks, with mixed-to-bearish energy and equity markets adding pressure. Lower EUA prices ease compliance costs for covered emitters but signal potential policy softening. Read →
CA, WA, Québec agree to link carbon markets
Environmental Defense Fund · Thu, Nov 19, 2026 · Share
California, Washington and Québec signed an agreement to link their Cap-and-Invest programs into a unified carbon market, with joint auctions targeted for 2027. The linkage is projected to cut an additional 45 million metric tons of emissions through 2045. It expands North America’s largest economy-wide carbon market and boosts demand for allowances across the linked jurisdictions. Read →
Check out Commodities 101: carbon section.
Real-World Assets & On-Chain Commodities
What's moving · Hyperliquid stock/commodity perps hit $4B daily volume as stocks/commodities take 69% of non-BTC/ETH flow.
MAS issues S$100M tokenized bills settled in wholesale CBDC
Singapore’s central bank completed a S$100 million (about $77.5 million) four-week tokenized MAS Bills issuance on November 6, issued natively on its Singapore Dollar Test Network and settled directly in wholesale CBDC with five primary dealers bidding more than double the size. The native ledger format eliminates reconciliation steps and intermediaries required for post-issuance tokenization. The test network will be renamed SG Digital Ledger and the bills will serve as collateral for secured lending; MAS plans larger issuances, more participants and expanded collateral use in 2027 live trials. Read →
Hyperliquid stock/commodity perps top $4B daily, 69% of non-crypto volume
Crypto Briefing · Thu, Nov 19, 2026 · Share
Delphi Digital data show Hyperliquid’s daily stock and commodity perpetual volume exceeded $4 billion, up from roughly $140 million a year earlier and now comprising 69% of volume outside Bitcoin and Ether (versus 94% altcoins previously). The category accounts for about one-third of total platform activity, with equities leading and commodities including oil contributing meaningfully; revenue from these markets rose about sixfold and continued growing through crypto downturns. HIP-3 third-party markets enable the expansion, providing 24/7 on-chain exposure that traditional venues lack on weekends. Read →
Industry News
What the companies said
From the companies' own call transcripts and prepared remarks, verbatim. Markets, never the stock.
Venture Global: Mike Sabel, CEO
Winter LNG price outlook · Q3 2026 earnings call, Nov 10 · Share
“If LNG volumes coming from the Middle East remain limited, we expect LNG prices to remain volatile this winter and potentially move higher from currently elevated levels.” Read →
Devon Energy: Clay M. Gaspar, President, CEO & Director
Asset portfolio roles · Q3 2026 earnings call, Nov 6 · Share
“The Permian Basin is our cornerstone, and the Anadarko, Marcellus and Rockies play complementary roles.” Read →
Venture Global: Mike Sabel, CEO
Asia coal-LNG switching · Q3 2026 earnings call, Nov 10 · Share
“In Asia, many markets looking to manage geopolitical risk have increased coal consumption as an alternative to buying spot LNG. This switching has pressured coal inventories and contributed to sharply higher coal prices.” Read →
Devon Energy: Clay M. Gaspar, President, CEO & Director
Global oil storage, supply/demand · Q3 2026 earnings call, Nov 6 · Share
“That gives us confidence that we can accelerate some of that for the shareholders in a market that I can tell you looks pretty radically different than it did a year ago when it comes to inventory, global storage and supply/demand numbers.” Read →
Corporate & Deals
What's moving · US-led consortium wins Kenya's Mrima Hill rare earths project as FERC approves Cheniere Sabine Pass LNG expansion.
FERC approves Cheniere Sabine Pass LNG expansion.
FERC approved Cheniere Energy's application to expand Sabine Pass LNG terminal in Louisiana by up to 20 million metric tons per year via three new trains. Phase 1 adds over 6 mtpa with long-term contracts already secured and FID targeted in coming months. Approval also covers related pipeline expansions. Read →
Baker Hughes raises 2026 revenue and EBITDA outlook.
World Energy News · Thu, Nov 19, 2026 · Share
Baker Hughes lifted full-year 2026 revenue guidance to $28.5 to 30.3 billion and adjusted EBITDA to $4.88 to 5.48 billion after closing its Chart Industries acquisition. The update reflects integration benefits and LNG equipment demand visibility into 2027. Shares rose on the announcement. Read →
Canadian Natural acquires Advantage Energy for C$2.53B.
Canadian Natural Resources agreed to buy Advantage Energy for C$2.53 billion including debt, adding 79,000 boe/d of Montney and Charlie Lake production in Alberta. The deal at C$13.55 per share includes infrastructure and development inventory adjacent to existing assets. It is the latest in Canadian upstream consolidation. Read →
Regulation & Government
What's moving · EU delays methane rules two years, easing US LNG contract fears with Europe.
EU extends methane importer rules delay to two years from 2027.
EU negotiators agreed to postpone monitoring, verification and reporting obligations for fossil fuel importers until 2029, double the Commission's original one-year proposal. The move addresses supply security concerns after Middle East disruptions and follows US and industry lobbying. Further delays would require new legislation. Read →
Trump extends Jones Act waiver 90 days for US oil and commodities.
President Trump extended the Jones Act waiver for 90 days, allowing foreign-flagged ships to move oil, gasoline and other commodities between US ports on a case-by-case basis. The measure, the longest in history, has enabled 90 million additional barrels of petroleum shipments since March to ease fuel price pressures from the Iran conflict. It takes effect without gap from the prior waiver. Read →
Sen. Baldwin bill would revoke China's PNTR status, raising tariffs.
Democratic Sen. Tammy Baldwin introduced the Ending China’s Special Treatment Act to revoke China's Permanent Normal Trade Relations status one year after enactment. Chinese imports would shift to higher Column 2 tariff rates under the Harmonized Tariff Schedule. The bill arrives days before Trump-Xi talks on the expiring trade truce. Read →
What traders and commodity market feeds are talking about
Oil falls 2% as Iran plots Hormuz breakout and Ukraine drones hit Russian fuel o
X / multiple traders · Fri, Nov 20 · Share
Traders on X are reacting to reports of Iran planning to break a US blockade of the Strait of Hormuz using dozens of vessels, alongside Ukrainian drone strikes limiting Russian refinery output and forcing more regions to ration fuel sales. Oil is down around 2% in the session as physical market concerns mount. #OOTT accounts highlight the dual supply risks and immediate price reaction. Read →
Iraq crude at $55 effective after Dubai drop and Hormuz freight risks
X / multiple traders · Fri, Nov 20 · Share
Discussions on X focus on Iraq resuming heavy discounts of $29 to 33/bbl to benchmarks, now implying some barrels near $55 after recent Dubai price weakness. Traders note the added challenges of expensive freight and Hormuz transit risks. #OOTT community sees this as a sign of softening physical markets. Read →
Gold, copper, silver, corn and wheat all extend weekly losses in broad selloff
X / multiple traders · Fri, Nov 20 · Share
Commodity traders on X note a fifth straight weekly loss led by metals, with gold, copper, silver and grains like wheat and corn all posting sharp declines. Saxo Bank commentary links the move to possible economic slowdown signals, AI capex slowdown and easing inflation concerns. Long-term supply tightness in some areas remains a counterpoint. Read →
US holds 90% of exchange copper stocks as China import premiums hit records
X / @Ole_S_Hansen · Fri, Nov 20 · Share
Ole S Hansen highlights rising LME and CME copper inventories, almost entirely in US warehouses due to prior tariff-driven stockpiling. Meanwhile China sees a historic squeeze with record Yangshan premiums and traders shipping metal from the US. The shift could ease China's tightness but depends on tariff expectations. Read →
Norway October production at 1.843 mbpd, up 8.6% m/m but down 3.1% y/y
X / @staunovo · Fri, Nov 20 · Share
Commodity analyst Giovanni Staunovo reports official NPD data showing Norwegian oil production at 1.843 million barrels per day in October. The monthly gain contrasts with a yearly decline, adding to the supply picture for European and global markets. #OOTT discussion follows the update closely. Read →
Recent video and podcast calls from respected oil and commodity analysts
The Commodities Show, latest episode: A 5 Million Barrel Oil Glut in 2027? with Jorge Leon (Rystad Energy) · Watch →
Funds pushed grain prices too low amid supply risks
Commodity funds have pushed prices too low, overlooking tightening supplies and shipping disruptions in the Black Sea and Strait of Hormuz. Watch/Listen →
Supply disruptions to keep energy and fertilizer tight
George Cheveley (Ninety One) via Bloomberg article · Thu, Nov 19 · Share
Disruptions to shipping in the Strait of Hormuz will keep pressure on energy and fertilizer markets. Watch/Listen →
Where commodity traders watch asymmetric risk · live odds via Polymarket
Hormuz Crisis
US-Iran tensions disrupting Strait of Hormuz oil flows. Polymarket odds, last 7 days.
US announces the end of the Iran blockade by March 31, 2027
42%
-18pp w/w
Hormuz traffic returns to normal by December 31
50%
WTI tops its $147 record by March 31, 2027
16%
+1pp w/w
Source: Polymarket
Russia / Ukraine Energy
A ceasefire agreement would open the way to sanctions relief on Russian crude, diesel and pipeline gas, bearish for Brent, European diesel cracks and TTF. Polymarket odds, last 7 days.
Russia-Ukraine ceasefire agreement by March 31, 2027
28%
-7pp w/w
Source: Polymarket
Red Sea / Bab el-Mandeb
Houthi threat to Red Sea shipping; a closure reroutes tankers and LNG around the Cape. Polymarket odds, last 7 days.
Bab el-Mandeb effectively closed by December 31
6%
-3pp w/w
Source: Polymarket
Fed Policy
Fed rate decisions move USD strength and industrial energy demand expectations. Polymarket odds, last 7 days.
Fed hikes 25 bps at the December meeting
93%
+4pp w/w
US recession by end of 2027
31%
+2pp w/w
Source: Polymarket
Paid listings · list your event
Commodity & Energy Trading Week APAC · Mar 3-4 · Singapore
Commodity Trading Week Europe · May 19-20 · London
Was this forwarded to you? Subscribe free.
The cash price of physical crude globally, real‑time live even on weekends.
WetBarrels.com is Morgan’s service providing free real‑time cash prices for physical crude oil, refined products, freight, natural gas and more. See today’s prices.
Morgan Downey's Commodity News is published by Wooden Table Press LLC. Informational only, not financial or legal advice. Do your own research. No representation is made as to accuracy or completeness.
Unsubscribe · View in browser · Subscribe · Advertise
Unsubscribe · View in browser · Subscribe · Advertise