Morgan Downey's Commodity News
The gen alpha daily zeitgeist of the physical commodity world
Oil · Gas · NGLs · Power · Coal · Ags · Metals · Fertilizers · Rare Earths · Shipping · Environment · RWA
Friday, October 23, 2026 · 48 stories
▶Listen · the 2-minute market briefToday's markets in two minutes. Tap to play
Prefer audio only? Listen here.
Markets at a glance
Charts: grey is the prior session, color is today.
Macro
|
S&P 500 Fut
7,692
-0.2%
-13 |
Dollar Index
101.77
+0.2%
+0.16 |
EUR/USD
1.1199
-0.2%
-0.0023 |
US 10Y Yield
4.953
-19 bp
|
Last price as of Fri, Oct 23, 5:35 AM ET. Click price for news.
Today's sponsor slot is open. Ask us about it →
Downey's Take
Crude up $1.16 (+1.0%) on Houthi attacks on Saudi Aramco infrastructure and shipping risks stoking Middle East supply disruption fears. Brent crude is on track for a third straight weekly gain. Many fear a strike on Iran this weekend ahead of Israeli elections. However US state dept only told government employees and their family members “in Saudi Arabia only” to leave. Other US regional withdrawals were not made. Saudi Aramco ordered its HQ employees in Dhahran (first since Iran war began) to work from home. So maybe the possible weekend action is Houthi targeted rather than Iran directly.
Dutch TTF European nat gas up $3.81 (+4.2%) on LNG supply fears from renewed US-Iran escalation risks ahead of winter.
US Nat Gas down $0.068 (-2.4%) on mild weather forecasts cutting heating demand.
JKM Asian LNG up $0.57 (+1.9%) on persistent tanker strike risks and Asian winter demand strength.
Silver down $1.00 (-1.8%) on higher oil prices reviving inflation concerns and stronger dollar.
Tin down $673 (-1.3%) on LME price weakness and macro risk aversion.
Drivers are sourced from third-party news and bank or desk commentary. Informational only, not trade advice.
The marquee commodity stories of the day
Wheat on track for longest weekly slump since 1997
Bloomberg · Fri, Oct 23, 2026
Wheat futures are heading for their eighth straight weekly decline, the longest losing streak in nearly three decades, reversing earlier gains driven by Black Sea supply concerns from Ukraine and Russia strikes. Read →
Physical oil prices fall while futures rally
Bloomberg · Thu, Oct 22, 2026
Brent futures have surged about $10 a barrel to a five-month high near $112 amid Middle East tensions and Saudi attacks, but physical barrel prices are diverging lower as traders assess supply recovery versus shipping risks. Read →
Corn futures rise second day on dip buying
Bloomberg · Thu, Oct 22, 2026
US corn futures climbed as much as 0.7% on Thursday, extending Wednesday's rebound after a six-day losing streak, supported by dip-buying and improving demand signals from Europe. Read →
Silver hits lowest settlement since Nov 2025
Anthony Harrup · Wall Street Journal · Thu, Oct 22, 2026
Silver futures fell 4.5% to $55.11 an ounce, on track for their lowest settlement since November 2025, pressured by rising Treasury yields, a stronger dollar and inflation concerns from Brent crude above $110 per barrel; gold also dropped 2.1% to $4,062.40. Read →
Natural gas futures rise after EIA storage report
Anthony Harrup · Wall Street Journal · Thu, Oct 22, 2026
US natural gas futures settled modestly higher for the first time in five sessions after the EIA reported a 77 Bcf net storage injection, narrowing the surplus over the five-year average to 35 Bcf as mild weather lingers. Read →
Most clicked yesterday
In this issue · tap a section to jump to it
Oil 5US Nat Gas 1NGL/LPG & Petchems 3Global Nat Gas & LNG 3Power 2Coal 3Agriculture 3Fertilizers 2Base Metals 3Iron Ore & Steel 4Precious Metals 3Rare Earths & Critical Minerals 3Shipping & Freight 2Environment 3On-Chain Commodities 1Corporate & Deals 5Regulation & Government 2Social buzz 5Podcasts 2Prediction Markets
Markets News
| Oil | Oil 101 |
What's moving · Houthi attacks on Saudi energy sites and tanker threats drive Brent to five-month high near $114.
Cash WTI 107.40 +1.12 | Cash Brent 121.94 +0.86 | Cash Br–TI 14.54 -0.26 |
Physical cash prices from Prism.
| Futures | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| WTI Crude Dec 2026 |
101.04 | +1.6% +1.57 |
+76.0% | +64.3% | +20.6% |
| Brent Dec 2026 |
114.33 | +1.0% +1.16 |
+80.4% | +66.4% | +27.6% |
| RBOB Gasoline Nov 2026 |
3.204 | +0.9% +0.028 |
+82.7% | +62.1% | +23.8% |
| Heating Oil Nov 2026 |
4.977 | +0.9% +0.045 |
+126% | +99.1% | +86.6% |
| RBOB Crk $/bbl |
33.54 | -1.2% -0.40 |
+107% +17.31 |
+55.7% +12.00 |
+34.6% +8.63 |
| NY HO Crk $/bbl |
108.01 | +0.3% +0.33 |
+207% +72.78 |
+148% +64.52 |
+282% +79.72 |
| NY 321 Crack $/bbl |
58.37 | -0.3% -0.15 |
+159% +35.80 |
+102% +29.51 |
+124% +32.32 |
Houthi strikes lift Brent 4% to five-month high.
Farhan Rafid and Anthony Harrup · Wall Street Journal · Thu, Oct 22, 2026
December Brent settled at $113.17 per barrel after rising 4%, its highest close since May 4. Iran-backed Houthis attacked Saudi Aramco's Shaybah oil field and other infrastructure, prompting Saudi Aramco to order evacuation of its Dhahran headquarters. US-Iran tensions added to supply disruption fears in the Middle East. Read →
Brent settles at $113.17 after Houthi attacks.
Reuters · Thu, Oct 22, 2026
Brent futures rose $4.35 or 4% to $113.17 per barrel. Attacks on Saudi targets and US orders for diplomats to leave Saudi Arabia heightened risks. Middle East crude exports remain above pre-conflict levels per Kpler data but shipping attacks persist. Read →
Tanker spill closes UAE beaches in Umm Al Quwain.
Reuters · Fri, Oct 23, 2026
UAE Ministry of Climate Change and Environment detected a tanker oil spill impacting beaches. All beaches in Umm Al Quwain closed temporarily for assessment. Odors reported in nearby areas but no health risks identified. Read →
Crude rises on Saudi attacks and Iran risks.
OPIS · Thu, Oct 22, 2026
December Brent traded up $2.38 at $111.20 per barrel amid Houthi drone attack on Shaybah field. US State Department ordered nonemergency personnel out of Saudi Arabia. Middle East exports recovered above 24 million b/d per Kpler despite shipping threats. Read →
US crude stocks fall 3.1 million barrels.
Anthony Harrup · Wall Street Journal · Wed, Oct 21, 2026
Commercial crude inventories dropped 3.1 million barrels to 412.5 million in the week ended Oct. 16. The draw exceeded analyst expectations and marked the third consecutive weekly decline. US crude production fell 410,000 b/d to 13.3 million b/d. Read →
Check out Oil 101.
| US Natural Gas | NatGas 101 |
What's moving · EIA 77 Bcf storage injection narrows surplus to 35 Bcf, lifting Henry Hub futures 0.2% to $2.796.
Cash Henry Hub 2.921 -0.032 |
Physical cash price from Prism.
| Futures | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Henry Hub Nov 2026 |
2.728 | -2.4% -0.068 |
-15.3% | -5.5% | -47.0% |
EIA gas storage · week ending Fri, Oct 16
A 77 Bcf injection took working gas to 3,644 Bcf, 35 Bcf (1%) above the five-year average and 152 Bcf below a year ago. That is 5 Bcf below the +82 Bcf consensus, bullish for price.
Working gas 3,644 Bcf +77 Bcf w/w | Year ago 3,796 Bcf | 5-yr avg 3,609 Bcf |
Consensus +82 Bcf this week | Year-ago chg +86 Bcf | 5-yr avg chg +93 Bcf |
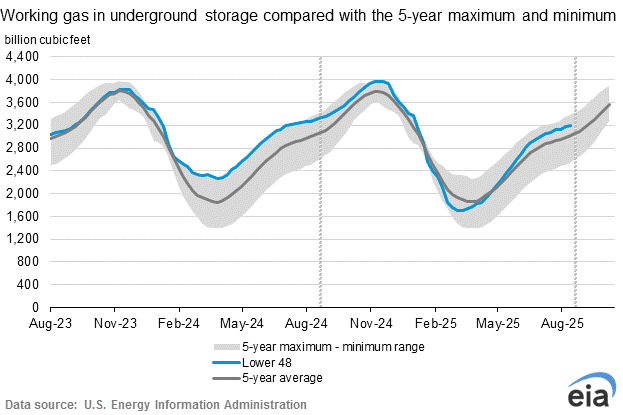
Source: EIA Weekly Natural Gas Storage Report · Full EIA report →
Permian output hits records; Waha stays positive
Kevin Dobbs · Natural Gas Intelligence · Mon, Oct 20, 2026, 10:34 AM ET
Permian Basin gas production set new records, yet Waha cash prices remained positive and above 2025 levels. New takeaway capacity is routing supply to Gulf Coast and other markets. Producers continue to manage localized pressure while basin output grows. Read →
Check out NatGas 101.
Your ad here
One sponsor per issue, and nobody else
This is where a sponsor's block sits: room to actually say what you do, to the people who read this letter every morning.
Email us for target audience and the rates →
| Wet Gas, NGLs/LPGs & Petchems | Commodities 101 |
What's moving · Mont Belvieu propane rises 0.8% to 105.1¢/gal on strong export draws tightening Gulf Coast stocks.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Ethane C2 $/gal |
0.301 | -0.0% -0.000 |
+27.0% | +13.1% | -30.1% |
| Propane C3 $/gal |
1.051 | +0.8% +0.009 |
+70.3% | +60.7% | -27.6% |
| N-Butane NC4 $/gal |
1.703 | -0.0% -0.001 |
+128% | +104% | +5.3% |
| Isobutane IC4 $/gal |
1.849 | -0.4% -0.008 |
+138% | +113% | +14.2% |
| Pentane C5 $/gal |
2.206 | +1.2% +0.025 |
+88.2% | +77.3% | +14.9% |
| Spread | Now | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| C2 Frac Sprd ¢/gal | 12 | unch | +10 | +5 | +3 |
| C3 Frac Sprd ¢/gal | 80 | +2 | +48 | +41 | -18 |
| C2 vs NWE Naph $/mt | -684 | -11 | -380 | -363 | -253 |
| C3 vs NWE Naph $/mt | -369 | -6 | -203 | -183 | -362 |
| C5 as % WTI | 92 | unch | +6 | +7 | -5 |
Mont Belvieu front-month settlement. Frac spread is the liquid over Henry Hub fuel value; naphtha spreads are before freight.
Targa set to overtake Enterprise as top Mont Belvieu fractionator
East Daley · Tue, Oct 21, 2026
Targa Resources will surpass Enterprise Products as Mont Belvieu’s largest fractionator when its 150 Mb/d Train 12 starts in 1Q27, followed by Train 13 in 1Q28. The shift ends Enterprise’s six-and-a-half-year lead amid rising ethane export demand that is making fractionation capacity a key bottleneck. Chinese ethane demand growth and new VLEC deliveries support higher recovery economics. Read →
Enterprise Neches River drives record US ethane exports
East Daley · Tue, Oct 21, 2026
US waterborne ethane exports hit a record 580 Mb/d average in September, led by Enterprise Products’ new Neches River terminal near Beaumont. Cargoes to China reached 403 Mb/d, nearly 70% of the total, as Chinese buyers returned. Mont Belvieu ethane traded at $0.28/gal on Oct 22, up from the $0.20 to 0.22/gal range in August. Read →
US propane exports set record amid Europe and Asia pull
World Ports Organization · Thu, Oct 22, 2026
US propane, ethane and butane exports held steady at 3.2 MMb/d in September with Asia taking the largest share. Europe imported 12 MMbbl of propane that month. FOB Gulf Coast premiums to Mont Belvieu more than doubled to 10.8 ¢/gal month-over-month per Platts data, lifting VLGC rates on Houston-Japan to 57.45 ¢/gal. Read →
Check out Commodities 101: NGLs section.
| Global Nat Gas & LNG | NatGas 101 |
What's moving · TTF surges above €90/MWh on low EU storage and Middle East supply risks, lifting JKM toward $31/MMBtu.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Dutch TTF €/MWh |
93.86 | +4.2% +3.81 |
+233% | +193% | +5.8% |
| Dutch TTF $/MMBtu |
30.81 | +4.2% +1.25 |
+233% | +193% | +5.8% |
| JKM $/MMBtu |
30.63 | +1.9% +0.57 |
+219% | +173% | -8.8% |
EU gas storage · gas day Wed, Oct 21
EU gas storage is 74.6% full, 845 TWh in store, 14.8 points below the five-year average for this date and 8.2 points below a year ago. Germany, the bloc's largest store, is 61.1%.
EU full 74.6% +0.02 pts d/d | Year ago 82.8% | 5-yr avg 89.4% same date |
Germany 61.1% |
Source: GIE AGSI+ · Full AGSI+ data →
TTF tops €91/MWh for first time since 2022
EFE · Thu, Oct 22, 2026
Dutch TTF hit €91.42/MWh intraday on Oct 22, up 4.8% from the prior close and the highest since Dec 2022. The move reflects geopolitical tensions in the Middle East plus EU storage at 75% full, well below seasonal norms, tightening the winter balance and supporting prices. Read →
European gas benchmark breaks 2022 highs
elDiario.es · Thu, Oct 22, 2026
TTF exceeded €91/MWh on Oct 22 amid Middle East tensions and winter supply concerns, with year-to-date gains over 220%. Analysts cite low inventories and geopolitical risks as the key drivers pushing the European benchmark to multi-year highs. Read →
TTF jumps 2.7% to highest since Dec 2022
Oilprice.com · Thu, Oct 22, 2026
TTF rose 2.7% to the equivalent of $100.84/MWh on Oct 22, the highest level since Dec 2022. Escalating Saudi-Houthi and Iran-related tanker incidents plus EU storage at only 74% full are cited as immediate drivers tightening the European gas balance. Read →
Chart of the day
Strait of Hormuz LNG crossings Oct 2026
via @CRUDEOIL231 on X · 86 likes
Line and bar chart of daily LNG transits through Hormuz with 10-day MA; shows sharp drop after US-Iran events, tying LNG balances to USGC
Strait of Hormuz LNG crossings Oct 2026
via @CRUDEOIL231 on X · 86 likes
Line and bar chart of daily LNG transits through Hormuz with 10-day MA; shows sharp drop after US-Iran events, tying LNG balances to USGC

Check out NatGas 101: LNG section.
| Power | Power 101 |
What's moving · PJM delays backstop capacity auction after FERC partial approval amid 6.8 GW data-center-driven shortfall.
PJM files FERC plan for backstop auction to fill 6.8 GW gap
Utility Dive · Thu, Oct 22, 2026
PJM filed a one-time reliability backstop auction proposal at FERC to procure up to 6.8 GW of new capacity from Sept. 30 to Oct. 21, with a proposed $555/MW-day price cap. The shortfall stems from the last base residual auction and growing data-center demand projected to reach 70 GW by 2038. Costs would be allocated across zones and load-serving entities, with bilateral deals able to reduce the target. Read →
PJM board approves backstop auction for data-center load growth
Utility Dive · Thu, Oct 22, 2026
PJM’s board directed staff to launch a reliability backstop capacity procurement after the prior auction fell short of the 20% reserve margin by 6.6 GW amid record prices. The move forms part of a broader plan for fast-track large-load interconnections and bilateral deals with data centers. Analysts expect the temporary fix to expand and support additional gas-fired capacity. Read →
Check out Power 101.
| Coal | Commodities 101 |
What's moving · India ramps record 2.6 Mt daily coal deliveries to power plants as stocks hit critical lows amid El Niño-driven demand surge.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| API2 Rotterdam $/t |
146.00 | +0.5% +0.70 |
+49.8% | +57.7% | -36.9% |
| Newcastle $/t |
154.45 | +1.3% +1.95 |
+46.1% | +41.7% | -15.1% |
India hits record 2.6 Mt daily coal supply to plants
Reuters / Economic Times · Thu, Oct 22, 2026
India is delivering a record 2.6 million tonnes of coal daily to power plants, with supply expected to normalize soon per a senior power ministry official. This follows data showing 96 of 191 coal plants at critically low stocks (under 3 days) as of Oct 19, up from 60 in mid-September, due to surging power demand and reduced hydropower from El Niño weather. The boost targets easing shortages at plants including NTPC amid 45 to 50 GW higher peak demand versus last year. Read →
Whitehaven posts record 11 Mt Q1 ROM output
Reuters · Fri, Oct 23, 2026
Whitehaven Coal reported managed ROM production of 11 million tonnes in the September quarter, beating consensus estimates and up 22% year-over-year, driven by strong Queensland output including Blackwater and Daunia mines. Equity sales of produced coal reached 6 Mt with average realized prices at A$226/t, up 20% YoY, while unit costs stayed at the low end of guidance. The company reaffirmed FY27 production targets and expects stronger cash generation as sales slippages unwind. Read →
China mine-mouth thermal coal prices slip on supply rise
Sxcoal · Thu, Oct 22, 2026
China's key production hub mine-mouth thermal coal prices edged lower on Oct 22 as supply-boosting policies and subdued end-user purchases eroded sentiment. Northern port spot liquidity eased with CCI 5500 unchanged at 1,040 yuan/t amid gradual production resumptions. Coking coal held steady while overall market confidence weakened despite winter restocking expectations. Read →
Check out Commodities 101: coal section.
| Agriculture | Commodities 101 |
What's moving · Wheat futures slide for eighth straight week in longest losing streak since 1997 amid harvest pressure and easing supply fears.
| Futures | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Corn Dec 2026 |
459 | -0.4% -2 |
+4.1% | +8.3% | -14.8% |
| Wheat Dec 2026 |
626 | +0.1% +1 |
+23.4% | +22.0% | -17.6% |
| Soybeans Jan 2027 |
1,265 | +0.0% +0 |
+22.7% | +21.4% | +2.2% |
| Sugar Mar 2027 |
20.23 | +0.5% +0.10 |
+34.8% | +35.1% | +4.3% |
| Coffee Dec 2026 |
309.5 | -1.0% -3.0 |
-11.3% | -23.2% | +52.8% |
| Cocoa Dec 2026 |
5,622 | +0.7% +40 |
-7.3% | -11.0% | +115% |
| Cotton Dec 2026 |
80.47 | -0.4% -0.32 |
+26.1% | +26.2% | -25.3% |
Soybeans climb on export sales but eye weekly loss
Reuters via Business Recorder · Fri, Oct 23, 2026
Chicago soybeans rose 0.32% to $12.57/bushel on USDA data showing 2.84 million metric tons of net export sales for the week ended Oct. 15, well above the prior four-week average. Strong Chinese buying provided support, but dry Midwest weather accelerating a bumper U.S. harvest and expectations for a larger Brazilian crop cap gains, leaving prices on track for a weekly decline. Read →
Soybeans edge lower near eight-week low on harvest
Reuters via Business Recorder · Fri, Oct 23, 2026
Chicago soybeans fell 0.12% to $12.43 to 3/4 per bushel Thursday as favorable dry weather speeds U.S. harvest of projected record crops. Renewed Chinese demand confirmed by USDA offered limited support but was outweighed by harvest pressure, while corn rebounded modestly on ethanol demand and wheat recovered from recent lows amid Black Sea monitoring. Read →
Cocoa drops 4.5% as coffee and sugar ease
CocoaIntel · Thu, Oct 22, 2026
New York cocoa December futures plunged $261 (4.47%) to $5,582/t on persistent selling despite dry weather concerns in Ivory Coast. Arabica coffee retreated from a near six-week high, and raw sugar extended losses for a fifth session to 20.13 cents/lb amid narrowing white premiums and fund positioning. Read →
Check out Commodities 101: agriculture section.
| Fertilizers | Commodities 101 |
What's moving · Middle East conflict and sulfur squeeze drive nitrogen and phosphate tightness, with Nutrien Trinidad gas shutdown adding ammonia pressure.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Urea | |||||
| China (ZCE) CNY/t |
1,679 | +0.2% +3 |
-4.0% | +2.5% | -39.7% |
| Egypt FOB $/t |
505.00 | +0.0% +0.00 |
-12.2% | +16.4% | -37.5% |
| Brazil CFR $/t |
480.50 | -0.1% -0.50 |
+17.9% | +13.9% | -38.4% |
| US Gulf FOB $/st |
436.75 | +0.0% +0.00 |
+12.9% | +15.6% | -37.1% |
| DAP | |||||
| NOLA FOB $/st |
802.50 | +0.0% +0.00 |
+28.4% | +4.6% | +17.1% |
The 5Y column starts from the October 2021 peak, when the European gas crisis shut ammonia plants and China halted urea exports. Daily settles; these contracts barely trade, so flat days are common.
StoneX: Nitrogen firm, potash stable, phosphates may correct in Brazil Q4.
Kim Clarksen · Fertilizer Daily · Thu, Oct 22, 5:00 PM ET
StoneX’s quarterly outlook flags firm nitrogen prices into Q4 from reduced Middle East supply, Hormuz risks, and potential December Indian buying. Potash holds steady on ample stocks; phosphates face output caps from Chinese MAP/DAP curbs and high sulfur costs despite some Russian/Kazakh relief. Brazil’s weak September imports and idled phosphate plants underscore supply-driven constraints over demand. Read →
China adds urea quotas; India tender shows buyer-seller price gap at $352 to 356 CF
IFDC (Argus Media) · Wed, Oct 21
China’s third and fourth urea export rounds (est. 1.5 to 2Mt each) surprised markets and softened prices, but shipment details remain unclear. India’s 1.7Mt tender drew lowest offers at $352.10/mt CFR east and $356.25/mt west (netback $320 FOB China), with only partial volumes awarded as suppliers resisted. Ammonium sulfate firms on tight availability while potash nears floor amid Black Sea/Baltic logistics risks and Uralkali 20% output cut. Read →
Check out Commodities 101: fertilizer section.
| Base Metals | Commodities 101 |
What's moving · LME copper falls 1.8% to five-week low as inventories surge 29kt on inflows easing supply fears.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Copper NY $/mt |
14,231 | +0.9% +126 |
+14.7% | +26.7% | +41.8% |
| Copper SHFE $/mt |
14,346 | -0.6% -89 |
+13.0% | +34.3% | +50.3% |
| Aluminium SHFE $/mt |
3,117 | +0.1% +3 |
+4.8% | +19.4% | -0.8% |
| Zinc SHFE $/mt |
3,365 | -0.8% -28 |
+12.0% | +22.3% | +7.2% |
| Nickel SHFE $/mt |
16,010 | -1.2% -195 |
-5.5% | +5.6% | -18.5% |
| Lead SHFE $/mt |
2,152 | +0.2% +5 |
-2.3% | +1.8% | +7.9% |
| Tin SHFE $/mt |
50,205 | -1.3% -673 |
+19.5% | +41.9% | +31.1% |
Copper hits five-week low as LME stocks surge
Tom Daly · Reuters · Thu, Oct 23, 2026
LME three-month copper fell 1.8% to $14,089/t, its lowest since mid-September, after 29,050 tonnes flowed into warehouses, mainly New Orleans, lifting total stocks to 272,950 tonnes, the highest since July 24. The build eased near-term supply concerns despite persistent regional bottlenecks outside the US and ongoing backwardation. Other LME metals also declined, with zinc down 1.7% and tin down 2.2%. Read →
Base metals tumble overnight; LME zinc, tin drop over 2%
Shanghai Metals Market (SMM) · Thu, Oct 23, 2026, 8:28 AM ET
LME zinc fell 2.24% and tin 2.44%; copper, aluminum and nickel each dropped more than 1% overnight. SHFE zinc, tin and nickel also declined over 1%, with only SHFE lead rising 0.25%. Precious metals led losses, with COMEX silver plunging 5.34% to its lowest since November 2025. Read →
Copper slips as LME inventories climb sharply
Reuters · Wed, Oct 22, 2026
LME copper dropped 0.8% to $14,310/t after inventories rose 11,475 tonnes, up 8% in a week with available stocks surging 40%. The build followed heavy US-bound shipments ahead of potential tariffs, leaving COMEX holding 70% of visible global stocks. Nickel rose 2.4% on prospects of Indonesian production cuts by Chinese operators. Read →
Check out Commodities 101: base metals section.
| Iron Ore & Steel | Commodities 101 |
What's moving · CMRG-Rio Tinto multiyear iron ore supply deal eases supply fears, sending DCE futures to CNY 669/mt amid Fortescue standoff and high port stocks.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Iron Ore 62% DCE $/dmt |
89.6 | +0.9% +0.8 |
-11.0% | -8.4% | -12.9% |
| Rebar SHFE $/mt |
409 | -0.6% -2 |
+3.8% | +6.7% | -48.3% |
| HRC SHFE $/mt |
422 | -0.7% -3 |
+2.4% | +3.8% | -47.2% |
Rio Tinto seals multiyear CMRG iron ore supply deal
Bloomberg · Thu, Oct 22, 2026
China Mineral Resources Group reached a multiyear agreement with Rio Tinto covering November 2026 to May 2028. The deal follows earlier instructions to mills to pause certain Rio purchases during talks and adds to CMRG contracts with other producers. It reduces near-term supply disruption risks for Chinese steelmakers while highlighting CMRG’s growing role in centralizing procurement. Read →
Fortescue keeps FY27 guidance despite CMRG talks
Adam Daunt · Australian Mining · Fri, Oct 23, 2026
Fortescue shipped 46.8 Mt of iron ore in Q1 FY27 but sold only 42.9 Mt due to ongoing CMRG negotiations, with inventories set to rise another 4 to 5 Mt in October. The miner maintained full-year shipment guidance of 197 to 207 Mt and C1 cost targets but warned operations could face adjustments if no deal is reached by year-end. Maintenance shutdowns also weighed on volumes and lifted unit costs 13% QoQ. Read →
DCE iron ore futures settle at 669 yuan/mt, down 1.83%
Shanghai Metals Market (SMM) · Thu, Oct 22, 2026
The most-traded DCE iron ore contract closed at 669 yuan/mt, down 1.83%, with Qingdao port spot prices falling 9 to 15 yuan/mt on average. Hot metal output edged up slightly to 2.3584 Mt/day while 10-port inventories stood at 104.65 Mt; mills bought on a need-only basis amid losses. Seaborne supply remains ample, capping upside despite modest demand improvement. Read →
China 47-port iron ore stocks fall to 172.8 Mt
Mysteel · Fri, Oct 23, 2026
Inventories of imported iron ore at China’s 47 major ports slipped to 172.8 million tonnes as of October 22, down 0.5% week-on-week after five weeks of builds. Fines stocks declined notably while lumps rose; the total remains 13.1% above year-ago levels. Lower arrivals and modest hot metal gains provided limited support as mills continued just-in-time purchasing. Read →
Check out Commodities 101: steel section.
| Precious Metals | Commodities 101 |
What's moving · Gold dips below $4,000 on stock rout and oil-driven inflation fears, pressuring the complex.
| Futures | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Gold Dec 2026 |
4,043 | -0.4% -17 |
-6.9% | -2.3% | +124% |
| Silver Dec 2026 |
54.01 | -1.8% -1.00 |
-23.0% | +11.6% | +120% |
| Platinum Jan 2027 |
1,565 | -0.8% -12 |
-23.1% | -1.8% | +47.3% |
| Palladium Dec 2026 |
1,052 | -0.4% -5 |
-35.4% | -28.1% | -48.7% |
Gold slips below $4,000 on stock selloff and volatility.
Bloomberg · Thu, Oct 22, 9:13 PM ET
Gold fell as much as 0.9% below $4,000/oz to a three-month low near $3,990 amid a deepening equity rout and rotation into Treasuries. The move followed a nearly 3% drop Thursday and reflects liquidity-driven selling rather than a shift in fundamentals. It underscores short-term pressure on bullion despite ongoing safe-haven interest. Read →
Silver hits lowest close since Nov 2025 on oil spike.
Anthony Harrup · WSJ · Thu, Oct 22, 2026
Silver futures settled down 4.6% at $54.764/oz, the lowest since November 2025, as rising oil prices revived inflation concerns and higher-for-longer rate expectations. The decline extended a second straight session and reflects silver's dual exposure to industrial demand and macro headwinds. It highlights near-term vulnerability for the white metal amid energy volatility. Read →
Newmont tops Q3 profit estimates on gold prices and Cadia.
Reuters / Mining Weekly · Thu, Oct 22, 2026
Newmont posted adjusted Q3 profit of $2.20/share, beating estimates, with revenue up 15% to $6.36 billion on higher gold prices averaging $4,204.59/oz. Copper output at Cadia jumped 35% sequentially after recovering from disruption. The results demonstrate operational resilience and margin support from elevated prices even as the broader market sells off. Read →
Check out Commodities 101: gold section.
| Rare Earths & Critical Minerals | Commodities 101 |
What's moving · China suspends US-specific gallium, germanium, antimony export ban to Nov 27 while rare earth pause nears Nov 10 deadline.
China suspends gallium, germanium, antimony export ban to US until Nov 27
Reuters via Awani International · Sun, Oct 11, 2025, (suspension effective then, r
China's commerce ministry suspended the US-specific outright ban on gallium, germanium and antimony exports, effective Sunday and running until November 27, 2026. The metals stay on the dual-use licensing list and the military end-user prohibition remains in force. The move eases a prior December 2024 restriction that had caused US shortages and workarounds, following the Trump-Xi trade truce, though broader controls persist. Read →
Phoenix Tailings to build $375M rare earth separation plant in NY
New York State Governor's Office · Tue, Oct 20, 2026
Phoenix Tailings will build a $375 million commercial-scale rare earth separation facility at Eastman Business Park in Rochester, NY, with state support of up to $3 million in tax credits for at least 90 new jobs. The 500,000 sq ft plant will process up to 18,000 tons of rare earth feedstock annually into over 4,400 tons of separated oxides starting 2027, full production 2028. It is backed by a conditional $500 million US Department of War Office of Strategic Capital loan and aims to reduce reliance on Chinese processing using cleaner waste-recovery methods. Read →
S&P Global releases critical minerals pricing reports for trade talks
Inside U.S. Trade · Fri, Oct 23, 2026
USTR Jamieson Greer said S&P Global's new draft market reports on tungsten, neodymium-praseodymium, antimony, gallium and germanium supply chains and pricing are an important step informing US-led trade negotiations that include price floors. The US also assumed chair of the Forum on Resource Geostrategic Engagement (FORGE) successor to the Minerals Security Partnership, releasing guiding principles for diversified critical mineral supply chains among coalition members. Read →
Check out Commodities 101: rare earths section.
| Shipping & Freight | Commodities 101 |
What's moving · Capesize strength lifts Baltic Dry Index 0.5% to 2,693 on Thursday, extending four-day rally.
| Route | $/day | Wk | 1Y | $/t | $/bbl |
|---|---|---|---|---|---|
| VLCC TD3C MEG to China |
$1.43M | -3.0% | +1515% | 238.4 | 32.52 |
| Suezmax TD20 WAF to UKC |
$551k | -6.7% | +778% | 151.7 | 20.70 |
| Aframax TD25 USG to UKC |
$249k | -23.4% | +479% | 142.8 | 19.48 |
| LR2 TC1 MEG to Japan |
$300k | +6.5% | +1280% | 196.5 | 26.38 |
| LR1 TC5 MEG to Japan |
$215k | +4.5% | +1185% | 203.2 | 22.83 |
| MR TC18 USG to Brazil |
$64k | +43.0% | +40.7% | 91.3 | 10.74 |
| MR TC7 Singapore to Aus |
$72k | -5.2% | +236% | 100.1 | 13.44 |
Report of Oct 15, 2026. Weekly round-voyage TCE and freight cost per tonne and per barrel; TD routes carry crude, TC routes refined products. 1Y is the $/day change; Prism's history starts in October 2023, so there is no 5Y. Source: Prism.
Capesize rates drive Baltic dry index to weekly high.
Linh Nguyen · World Ports Organization · Wed, Oct 21, 2026
The Baltic index rose 3.36% to 2,680 points on Wednesday, its highest since October 13. Capesize surged 7.69% to 3,793 points with daily earnings up $2,453 to $30,895; panamax slipped 1.91%. Iron ore futures stayed flat as higher freight costs offset weak demand signals. Read →
Largest containerships return to Red Sea in force.
Linton Nightingale · Lloyd's List · Wed, Oct 22, 2026
More than 100 ships above 16,000 TEU have transited the Suez Canal since September as carriers restore Red Sea services. Weekly container capacity through Suez averaged 753,000 TEU in early October, exceeding 50% of 2023 levels for the first time. 63% of Asia-Europe capacity now routes via Red Sea loops, cutting Cape diversions to the lowest since January 2024. Read →
Check out Commodities 101: shipping section.
| Environment | Commodities 101 |
What's moving · Gas above €90/MWh lifts EUAs as EP boosts free allowances to fallback industries.
CCAs near $33 as midterms, Q4 auction loom
Carbon Pulse · Thu, Oct 22, 2026
California Carbon Allowance futures ticked up toward $33 on heightened trading ahead of US midterm elections and the November Q4 auction. Washington Carbon Allowances rose to around $40. The moves reflect pre-election positioning in the linked WCI market. Read →
EP boosts free EU ETS allowances for fallback sectors
Carbon Pulse · Thu, Oct 22, 2026
The European Parliament voted Thursday to raise free EU ETS allowances for industries in the ‘fallback’ benchmark category by nearly 100 million before 2030. The decision eases compliance costs for certain heavy emitters ahead of tighter benchmarks. It comes amid ongoing EU ETS reform talks that could affect overall allowance supply. Read →
EUAs rise as TTF gas hits €90/MWh peak since 2022
Carbon Pulse · Thu, Oct 22, 2026
EU carbon prices edged higher Thursday with little reaction to the prior day’s MSR adjustment decision. European gas prices settled above €90/MWh, their highest level since December 2022, pushing power prices above €150/MWh and supporting EUA demand via coal-to-gas dynamics. Read →
Check out Commodities 101: carbon section.
Real-World Assets & On-Chain Commodities
What's moving · CFTC updated FAQs clearing tokenized assets and blockchain recordkeeping for commodities firms, spurring on-chain commodity adoption.
Ripple Prime adds 100+ RWA perps via Hyperliquid
Yogita Khatri · The Block · Thu, Oct 15, 2026, 10:43 AM ET
Ripple Prime launched institutional perpetual swaps referencing more than 100 traditional markets including metals and energy, routed through Trade.xyz perpetual futures on Hyperliquid. The 24/7 products allow cross-margining and RLUSD collateral where permitted, with market maker Virtu among early users; Ripple Prime acts as principal. This extends continuous on-chain commodity and macro exposure to Wall Street desks without direct platform access. Read →
Industry News
Corporate & Deals
What's moving · Eni doubles Q3 profit, pays €1.3B special dividend and lifts buyback to €3.8B on high refining margins.
Eni doubles Q3 profit, adds €1.3B dividend and raises buyback to €3.8B
Reuters · Fri, Oct 23, 2026
Eni reported Q3 adjusted net profit of €2.8 billion, more than double the prior year, beating consensus. It will pay a €1.3 billion special dividend in December and raise its 2026 share buyback to €3.8 billion while lifting full-year cash flow guidance to €16.5 billion. Strong refining margins and higher oil and gas output drove the cash windfall for the Italian major. Read →
QatarEnergy in advanced talks for at least 3M mtpa LNG from Venture Global
Reuters · Thu, Oct 22, 2026
QatarEnergy is negotiating a long-term deal to purchase at least 3 million metric tons per year of LNG from Venture Global. The talks follow spot purchases to offset supply disruptions from the Iran conflict and Strait of Hormuz issues. A separate deal with Cheniere for 4 mtpa through 2054 was announced earlier. Read →
ADNOC's XRG in early talks to acquire stake in Eni's Libya assets
Reuters · Thu, Oct 22, 2026
XRG, ADNOC's international investment arm, is in preliminary talks to buy a stake in Eni's Libya oil and gas operations, which produced 162,000 boe/d last year. The move supports XRG's goal to grow LNG capacity to 20 to 25 mtpa by 2035 amid Gulf geopolitical risks. Both companies declined to comment on speculation. Read →
Infineum explores $8B sale as Shell and Exxon refocus on core operations
Reuters · Thu, Oct 22, 2026
Infineum, the 50:50 Shell-ExxonMobil lubricants and fuel additives joint venture, has tapped Bank of America to explore a sale targeting roughly $8 billion. The process is early-stage and may attract private equity interest. Shell is seeking to streamline non-core chemicals exposure. Read →
Dow beats Q3 estimates, sees Q4 profit above views on polyethylene prices
Pooja Menon · Reuters · Thu, Oct 22, 2026
Dow posted Q3 adjusted EPS of 71 cents, beating estimates, with sales up 13% to $11.3 billion on higher polyethylene prices and cost cuts. It guided Q4 adjusted core profit above consensus at about $1.54 billion. The company is on track for over $1 billion in annual core profit gains in 2026 and 2027. Read →
Regulation & Government
What's moving · Trump waives Graham Act Russia tariffs/sanctions and invokes DPA for oil refining to ease diesel prices ahead of midterms.
Trump delays wind turbine tariffs for 180-day talks
Bloomberg · Thu, Oct 22, 4:07 PM ET
President Trump signed an executive order Thursday declaring wind turbine imports a national security threat under Section 232 but directed the USTR and Commerce Secretary to negotiate with partners instead of imposing tariffs immediately. Existing aluminum, copper and steel tariffs on components remain. The 180-day review period allows time for talks before any further remedies. Read →
Trump invokes DPA for oil production and refining
Reuters · Thu, Oct 22, 9:14 PM ET
Trump issued a presidential determination Thursday classifying domestic petroleum production, refining and logistics as essential to national defense under the Defense Production Act. The move waives certain statutory requirements to enable purchases, commitments and funding for projects aimed at expanding capacity amid high fuel prices. It follows earlier announcements of up to $150 million in DPA Title III funding for refineries. Read →
What traders and commodity market feeds are talking about
Tanker hits and Hormuz threats lift Brent near $114
X / multiple traders · Thu, Oct 22
#OOTT traders and analysts highlight recent Iranian claims of tanker strikes and ongoing Hormuz disruptions, with Dated Brent volatility and shipping premiums keeping prices elevated despite some flow recovery. Discussions note Brent's premium over WTI and risks of further escalation from Houthi or Iranian actions. This matters as sustained high prices could pressure global demand and inflation. Read →
Valero: no meaningful demand destruction at high prices
X / @ZmansEnrgyBrain · Thu, Oct 22
The refiner's outlook sparks chatter among energy traders that consumers will absorb higher costs rather than cut usage significantly. #OOTT users discuss implications for refining margins and crude demand holding up amid geopolitical premiums. Relevant for oil bulls betting on inelastic demand supporting prices above $100. Read →
Gold silver slide as oil surge sparks selloff
X / multiple traders · Thu, Oct 22
Traders note spot gold dropping sharply to multi-week lows and silver following, attributing it to oil prices stoking inflation worries that could delay rate cuts. Discussions contrast safe-haven flows into bonds with commodity rotation. Matters for metals bulls as higher energy costs weigh on precious metals sentiment. Read →
PTJ: long oil, stocks will hate higher prices
X / multiple traders · Thu, Oct 22
Traders recirculate the hedge fund manager's call for further oil gains post-midterms, warning equities could suffer from the resulting inflation pressure. #OOTT and broader feeds debate timing and macro fallout. Highlights professional positioning in energy amid volatility. Read →
Trump DPA order targets oil production and refining
X / multiple traders · Thu, Oct 22
Energy accounts discuss the executive action to boost domestic supply as a counter to Middle East risks, with potential impacts on US refining and exports. Conversations weigh policy effects on prices and energy security. Relevant for North American producers and traders monitoring government intervention. Read →
Recent video and podcast calls from respected oil and commodity analysts
GS Struyven: precautionary buying props oil
Daan Struyven on Goldman Sachs Exchanges (YouTube) · Fri, Oct 23
Precautionary physical buying and portfolio hedging keep prices elevated despite rebounding Middle East flows. Watch/Listen →
Suderman: soybeans lead midday ag trade
Arlan Suderman (StoneX) on Market Talk podcast · Thu, Oct 22
Soybeans and soybean oil lead midday while other grains trade mixed to lower. Watch/Listen →
Where commodity traders watch asymmetric risk · live odds via Polymarket
Hormuz Crisis
US-Iran tensions disrupting Strait of Hormuz oil flows. Polymarket odds, last 7 days.
Hormuz traffic returns to normal by December 31
12%
unch
US-Iran ceasefire holds through December 31
28%
-3pp w/w
Source: Polymarket
US Diesel Export Ban
Would cut US distillate exports, widen the US-Europe diesel spread and hit Gulf Coast refining margins. Polymarket odds, last 7 days.
US announces a diesel export ban by December 31
11%
+1pp w/w
Source: Polymarket
Red Sea / Bab el-Mandeb
Houthi threat to Red Sea shipping; a closure reroutes tankers and LNG around the Cape. Polymarket odds, last 7 days.
Bab el-Mandeb effectively closed by December 31
16%
+2pp w/w
Source: Polymarket
Fed Policy
Fed rate decisions move USD strength and industrial energy demand expectations. Polymarket odds, last 7 days.
Fed hikes 25 bps at the October meeting
7%
-7pp w/w
US recession by end of 2026
7%
unch
Source: Polymarket
Hurricane Season 2026
US Gulf Coast hurricane landfall risk for upstream NG + oil supply. Polymarket odds, last 7 days.
Any Cat 4+ hurricane US landfall before 2027
6%
-2pp w/w
Source: Polymarket
Russia / Ukraine Energy
A ceasefire would shift Russian crude and product flows and European gas pricing. Polymarket odds, last 7 days.
Russia-Ukraine ceasefire agreement by December 31
20%
+5pp w/w
Source: Polymarket
Paid listings · list your event
Energy Trading Week Americas · Oct 27-28 · The Woodlands, Texas
Commodity & Energy Trading Week APAC · Mar 3-4 · Singapore
Commodity Trading Week Europe · May 19-20 · London
Was this forwarded to you? Subscribe free.
The cash price of physical crude globally, real‑time live even on weekends.
Prism is Morgan’s service providing free real‑time cash prices for physical crude oil, refined products, freight, natural gas and more. See today’s prices.
Morgan Downey's Commodity News is published by Wooden Table Press LLC. Informational only, not financial or legal advice. Do your own research. No representation is made as to accuracy or completeness.
Unsubscribe · View in browser · Subscribe
Unsubscribe · View in browser · Subscribe