The gen alpha daily zeitgeist of the physical commodity world
Oil · Gas · NGLs · Power · Coal · Ags · Metals · Fertilizers · Rare Earths · Shipping · Environment · RWA · Podcast · Street views · Archive
Saturday, November 14, 2026
Prefer audio only? Listen here.
Markets at a glance
Charts: grey is Friday's session, color is since Friday's settle, with WTI, Brent and nat gas live onchain through the weekend.
Live on this page: the onchain tiles, their charts and WetBarrels.com cash prices, with cash vs futures, refresh every minute.
Macro
|
S&P 500 Fut
7,583
-0.4%
-32 |
Dollar Index
103.41
-0.00%
-0.00 |
EUR/USD
1.1028
-0.3%
-0.0031 |
US 10Y Yield
5.154
+5.1 bp
|
Friday's settlements; except live weekend prices for WTI, Brent and US nat gas from 24/7 on chain trading as of Sat, Nov 14, 5:36 AM ET. Click here for updated live weekend prices on the Commodity News web page. Click price for news.
Downey's Take
Crude flat this morning (live Saturday on chain trading) amid ongoing Strait of Hormuz tanker incidents with no fresh weekend escalation reported. Brent settled Friday at $95.84 and WTI at $88.56, narrowing the Brent-WTI spread to $7.28.
US Nat Gas down $0.110 (-3%) Friday on above-average storage build and warmer forecasts easing heating demand.
Platinum down $31 (-2%) Friday on rising US rate-hike expectations pressuring precious metals.
Silver down $0.94 (-2%) Friday on stronger US inflation data lifting the dollar and yields.
Ethane down $0.005 (-2%) Friday on broader energy complex weakness tied to macro rate signals.
Copper down $234 (-2%) Friday on Nvidia CEO resignation and AI demand concerns weighing on industrial metals.
US Nat Gas down $0.110 (-3%) Friday on above-average storage build and warmer forecasts easing heating demand.
Platinum down $31 (-2%) Friday on rising US rate-hike expectations pressuring precious metals.
Silver down $0.94 (-2%) Friday on stronger US inflation data lifting the dollar and yields.
Ethane down $0.005 (-2%) Friday on broader energy complex weakness tied to macro rate signals.
Copper down $234 (-2%) Friday on Nvidia CEO resignation and AI demand concerns weighing on industrial metals.
Drivers are sourced from third-party news and bank or desk commentary. Informational only, not trade advice.
Street Commodity Views
Goldman Sachs (Fri Nov 13) recommends positive allocation to commodities as portfolio hedge, favouring long copper and short aluminium on mine supply constraints and demand from electrification and AI.
Saxo Bank (Fri Nov 13) sees copper physical tightness in China as counterweight to bearish AI demand narrative.
IEA (Fri Nov 13) sees global oil market swinging into surplus in October on lofty Persian Gulf exports.
Dated views from banks and research houses, as published; houses change them without notice. Informational only, not trading advice. Past views by commodity and house →
The week
Biggest moves of the week: Nat Gas +7.7%, Dutch TTF +6.3%, Silver -5.2%, Gold -4.6%, Soybeans +3.6%.
| 📑 | Commodity Research Reports →5 reports picked for the weekend |
| 🎧 | Commodity Podcasts →6 episodes for the weekend |
| 📈 | Commodity Forward Curves →WTI, Brent, 3-2-1 crack and Henry Hub |
| 📅 | Week Ahead Commodity Diary →2 dated events in the week ahead |
The marquee commodity stories of the day
IEA: Oil market swings to surplus as Gulf exports recover
Bloomberg · Fri, Nov 13, 9:00 AM ET
The International Energy Agency said global oil markets will swing to a supply surplus for the first time since the start of the Iran war as Persian Gulf exports recover despite the ongoing conflict. “The oil market is showing tentative signs of rebalancing, with global oil supplies surpassing demand for the first time since the outbreak of the war in Iran,” the IEA said in its monthly report. Read →
Copper heads for worst weekly run in nearly two years
Bloomberg News · Bloomberg · Fri, Nov 13, 8:13 AM ET
Copper tumbled toward a fifth weekly loss, the longest run in nearly two years, on upheaval in the artificial-intelligence industry and growing expectations for further US interest-rate hikes. Benchmark three-month futures dropped below $13,500 a ton on the London Metal Exchange, on track for the lowest close since mid-July. Read →
Gold holds ground after PPI miss; silver at 52-week low
Anthony Harrup · Wall Street Journal · Fri, Nov 13, 11:54 AM ET
Gold futures held their ground in choppy trading as a below-estimate US producer price reading and steadying oil prices eased inflation concerns. Silver fell to a new 52-week low; front-month gold settled up $1.30 at $3,879.70 an ounce for a 4.5% weekly loss. Read →
US natural gas futures give back weather-driven gains
Anthony Harrup · Wall Street Journal · Fri, Nov 13
U.S. natural gas futures settled lower, giving back the previous day’s weather-driven gains as a spell of cold weather is set to lift near-term heating demand. The EIA reported a 61 Bcf storage injection for last week; Nymex natural gas fell 3.3% to $3.230/mmBtu. Read →
West African crude discounts widen sharply on shipping costs
Bloomberg · Fri, Nov 13, 5:02 PM ET
West African grades such as Nigeria’s Forcados and Qua Iboe crude have fallen far faster than headline prices this month as the cost of shipping oil around the world has tumbled, making some barrels up to $64 cheaper for certain buyers. Read →
Most clicked yesterday
In this issue · tap a section to jump to it
OilUS Nat Gas 3NGL/LPG & Petchems 3Global Nat Gas & LNG 4Power 2Coal 2Agriculture 2Fertilizers 2Base Metals 3Iron Ore & Steel 3Precious Metals 2Rare Earths & Critical Minerals 3Shipping & Freight 3Environment 3On-Chain Commodities 2Corporate & Deals 5Regulation & Government 3Social buzz 5Podcasts 3Prediction Markets
Markets News
| Oil | Oil 101 |
What's moving · IEA report signals first global oil surplus since Iran war as Gulf exports rebound, driving Brent to $95.84/bbl and second straight weekly loss.
| Physical cash | Last 1D | Cash vs futures |
|---|---|---|
| WTI |
92.53 +0.87 | +3.97 backwardation, tight |
| Brent |
95.20 +0.53 | +1.66 DFL, kink, balanced |
| Brent minus WTI | 2.67 -0.34 |
LIVE Cash from WetBarrels.com, live on weekend. Cash vs futures is cash minus the first futures month; for Brent, Dated to frontline (DFL). Above zero is backwardation; a kink is a curve that turns between cash and the 2nd month. In physical terms backwardation is a tight market, contango a loose one, and a kink or flat curve a balanced one.
| Futures | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| WTI Crude Dec 2026 LIVE |
88.51 | -0.05% -0.05 |
+54.2% | +47.8% | +9.5% |
| Brent Jan 2027 LIVE |
96.02 | +0.2% +0.18 |
+57.5% | +49.3% | +16.8% |
| RBOB Gasoline Dec 2026 |
2.621 | -1.8% -0.049 |
+51.8% | +30.1% | +11.2% |
| Heating Oil Dec 2026 |
4.259 | -0.7% -0.028 |
+101% | +67.2% | +77.6% |
| RBOB Crk $/bbl |
21.54 | -8.1% -1.89 |
+42.6% +6.44 |
-12.9% -3.18 |
+18.7% +3.39 |
| NY HO Crk $/bbl |
90.30 | -1.1% -1.00 |
+185% +58.65 |
+91.9% +43.23 |
+355% +70.46 |
| NY 321 Crack $/bbl |
44.46 | -3.5% -1.60 |
+116% +23.84 |
+38.2% +12.29 |
+138% +25.74 |
LIVE: price and 1D live onchain since Friday's settle.
Charts of the day
| 1 | Sanctioned tankers Middle East chartvia @CRUDEOIL231 on X · 144 likesData chart on sanctioned oil tankers dominating Iraq and ME crude exports, important for sanctions evasion and supply logistics |
| 2 | Oil freight rates plunge 50-75%via @JavierBlas on X · 597 likes |
| 3 | UK power prices drop £120/MWhvia @renewablesmiffy on X · 119 likes |
Check out Oil 101.
| US Natural Gas | NatGas 101 |
What's moving · EIA reports 61 Bcf storage build, below expectations, widening surplus to 75 Bcf above five-year average.
| Physical cash | Last 1D | Cash vs futures |
|---|---|---|
| Henry Hub |
3.202 +0.006 | -0.028 contango, loose |
LIVE Cash from WetBarrels.com, live on weekend. Cash vs futures is cash minus the first futures month. Above zero is backwardation; a kink is a curve that turns between cash and the 2nd month. In physical terms backwardation is a tight market, contango a loose one, and a kink or flat curve a balanced one.
| Futures | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Henry Hub Dec 2026 LIVE |
3.233 | +0.08% +0.003 |
-12.4% | -25.9% | -35.6% |
LIVE: price and 1D live onchain since Friday's settle.
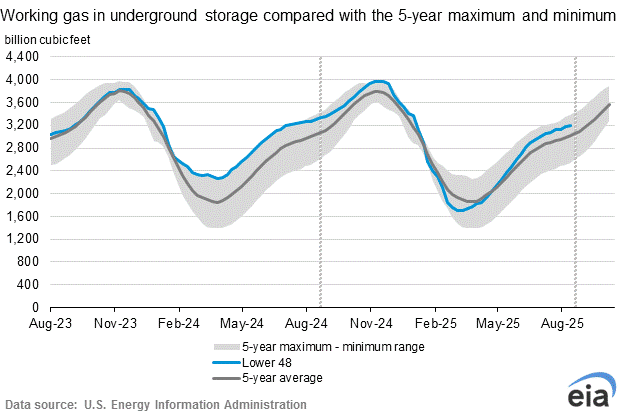
EIA gas storage · week ending Fri, Nov 6
A 61 Bcf injection took working gas to 3,862 Bcf, 75 Bcf (2%) above the five-year average and 92 Bcf below a year ago. That is 6 Bcf below the +67 Bcf consensus, bullish for price.
Working gas 3,862 Bcf +61 Bcf w/w | Year ago 3,954 Bcf | 5-yr avg 3,787 Bcf |
Consensus +67 Bcf this week | Year-ago chg +45 Bcf | 5-yr avg chg +33 Bcf |
Source: EIA Weekly Natural Gas Storage Report · Full EIA report →
EIA: Lower 48 storage up 61 Bcf to 3,862 Bcf week ended Nov. 6.
Energy Jobline / EIA · Fri, Nov 14
The EIA weekly report released Nov. 13 (delayed by Veterans Day) confirmed a 61 Bcf build to 3,862 Bcf. Stocks sit 2.3% below year-ago levels but 2.0% above the five-year average of 3,787 Bcf. South Central led with +27 Bcf; the build was smaller than the prior week’s 77 Bcf and below analyst estimates. Read →
EIA storage +61 Bcf misses estimates; LNG feedgas hits 20.5 Bcf/d.
Energy Edge Consulting · Fri, Nov 13, 7:52 PM ET
The 61 Bcf injection undershot Bloomberg and BofA forecasts of 63 to 67 Bcf. Lower 48 output recovered to 110 Bcf/d with Permian, Haynesville and Northeast gains. LNG feedgas nominations reached 20.5 Bcf/d (Sabine Pass at 5.1 Bcf/d), pointing to a potential daily record near 21.9 Bcf/d amid rising spot prices. Read →
Traders eye EIA storage amid warm forecasts and above-average stocks.
FXEmpire · Fri, Nov 13, 10:49 AM ET
Pre-report analysis noted stocks at 3,801 Bcf (below year-ago, above five-year average) with regional South Central deficits near LNG hubs. EIA’s November STEO lowered Henry Hub forecasts to $3.37/MMBtu for 2026. Warm weather outlook tempers demand while LNG exports and potential cold shots remain key supports. Read →
Check out NatGas 101.
Sponsored · Kpler
How much oil is moving, in real time
With Hormuz and the Red Sea redrawing trade routes minute by minute, you need the quickest, most reliable source of truth. Kpler tracks commodity cargoes and the vessels carrying them. You can see exports, imports, floating storage and more as they develop in real time.
Kpler covers oil, products, gas, and dry bulk. Pair flows with refinery runs, inventories and freight analytics, and the story behind a price move becomes visible before the market has priced it in.
| Wet Gas, NGLs/LPGs & Petchems | Commodities 101 |
What's moving · Mont Belvieu propane futures settled 3.6% higher at $1.10275/gal on Nov 13 amid surprise EIA propane stock build and regional imbalances.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Ethane C2 $/gal |
0.290 | -1.9% -0.006 |
+22.3% | +8.4% | -28.5% |
| Propane C3 $/gal |
1.103 | +1.1% +0.012 |
+78.7% | +69.8% | -16.7% |
| N-Butane NC4 $/gal |
1.726 | +1.1% +0.019 |
+132% | +100% | +11.9% |
| Isobutane IC4 $/gal |
1.720 | -0.8% -0.014 |
+121% | +92.8% | +11.4% |
| Pentane C5 $/gal |
1.967 | -0.2% -0.004 |
+67.8% | +56.2% | +4.8% |
| Spread | Now | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| C2 Frac Sprd ¢/gal | 8 | unch | +8 | +10 | unch |
| C3 Frac Sprd ¢/gal | 81 | +2 | +53 | +56 | -6 |
| C2 vs NWE Naph $/mt | -600 | +8 | -297 | -273 | -163 |
| C3 vs NWE Naph $/mt | -250 | +19 | -85 | -54 | -189 |
| C5 as % WTI | 93 | unch | +8 | +5 | -4 |
Mont Belvieu front-month settlement. Frac spread is the liquid over Henry Hub fuel value; naphtha spreads are before freight.
ONEOK expands Permian NGL pipeline for 2028 exports
East Daley Analytics · Wed, Nov 12, 2026
ONEOK announced a 245 Mb/d NGL pipeline expansion in the Delaware Basin, expected online in 3Q27, to access third-party volumes and extend its system into New Mexico. The move follows its Brazos Midstream acquisition and aligns with its Texas City LPG export JV with MPLX, set for early 2028 startup with 400 Mb/d capacity (200 Mb/d reserved for ONEOK). NGL throughput in the Gulf Coast/Permian region grew 16% in 3Q26. Read →
Dorian LPG orders three Panamax VLGCs from Hanwha
World Ports Organization · Thu, Nov 12, 2026
Dorian LPG contracted three 90,000m³ dual-fuel Panamax VLGCs at Hanwha Ocean for delivery in June, September and December 2030 at roughly $345 million total. The vessels feature LPG-capable engines, shaft generators and optimized hulls for efficiency, with Panamax dimensions enabling transit of the original Panama Canal locks. The order supports fleet renewal and decarbonization amid tight VLGC markets driven by longer voyages and canal constraints. Read →
Dorian LPG orders new VLGC, sells older vessels
World Ports Organization · Fri, Nov 13, 2026
Dorian LPG ordered a 90,000-cbm dual-fuel Panamax VLGC from HD Hyundai for delivery in July 2029 as part of fleet renewal, alongside MOAs to sell three older vessels (including the 2014-built Corsair) for about $256 million. The company highlighted strong near-term chartering with high utilization and TCE rates. This follows its recent Hanwha order and supports positioning amid elevated freight from U.S.-Asia routes and Panama restrictions. Read →
Check out Commodities 101: NGLs section.
| Global Nat Gas & LNG | NatGas 101 |
What's moving · TTF falls 4% to €90.78/MWh on accelerating EU storage withdrawals at record pace amid low 71% fill levels.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Dutch TTF €/MWh |
90.95 | -1.4% -1.31 |
+223% | +189% | +13.8% |
| Dutch TTF $/MMBtu |
29.40 | -1.4% -0.42 |
+223% | +189% | +13.8% |
| JKM $/MMBtu |
29.60 | – | +226% | +175% | -0.8% |
EU gas storage · gas day Thu, Nov 12
EU gas storage is 71.0% full, 804 TWh in store, 17.8 points below the five-year average for this date and 11.2 points below a year ago. Germany, the bloc's largest store, is 57.6%, 30.7 points below its five-year average and 17.1 points below a year ago. LNG terminals are 49.2% full and sent out 4,251 GWh, 5% less than the day before.
EU full 71.0% -0.24 pts d/d | Year ago 82.2% | 5-yr avg 88.8% same date |
Germany 57.6% | Year ago 74.7% | 5-yr avg 88.3% same date |
Source: GIE AGSI+ and ALSI+ · Full AGSI+ data →
Orlen cancels Qatar LNG contract, saving up to $2B
Reuters · Fri, Nov 13, 5:10 PM ET
Poland's Orlen terminated a long-term QatarEnergy LNG supply contract citing force majeure after deliveries failed due to Middle East disruptions. Analysts estimate the move could save the company up to $2 billion by replacing volumes with cheaper US LNG priced off Henry Hub instead of oil-linked terms. The cancellation affects about 14 cargoes annually and signals shifting European buyer preferences away from disrupted Gulf supplies. Read →
Dark Hormuz LNG transits hit post-war high in Nov
Anna Pringle · Argus Media · Fri, Nov 13, 2026
Confirmed dark (AIS-off) LNG carrier transits through the Strait of Hormuz reached their highest post-war rate this month with 17 laden sailings so far in November. Six vessels transited this week, some likely involving ship-to-ship transfers, with most heading to Asia though a few appear bound west of Suez. Three carriers loaded at Ras Laffan on Nov 12, two without broadcasting locations, showing Qatar's partial recovery in loadings despite ongoing disruptions. Read →
Europe drains storage fast as TTF nears €100
Seb Kennedy · Energy Flux · Fri, Nov 13, 2026
Dutch TTF surged 17% in three days to trade as high as €96.42/MWh on Nov 13 as EU storage withdrawals accelerated to nearly three times the seasonal norm. EU aggregate storage sits at 71% full, 19 points below the five-year average, with Germany at 58% and net daily draws hitting record levels for the date. Norwegian supply is also constrained by extended outages at Visund and Troll totaling 24.5 mcm/d or 7% of export capacity. Read →
China curbs LNG buys on cheap domestic gas
Bloomberg · Sun, Nov 9, 2026
China's national average LNG price fell to the equivalent of $21.97/MMBtu, nearly $10 below JKM, as domestic supply weakens winter spot demand from the world's largest importer. This eases competition for Atlantic-basin cargoes and supports potential diversions to Europe where TTF remains elevated. The development narrows the JKM-TTF arb and could moderate Asian price pressure amid Northeast Asia's entry into peak heating season. Read →
Check out NatGas 101: LNG section.
| Power | Power 101 |
What's moving · PJM data-center load forecasts drive capacity shortfall, pushing backstop auction and higher costs into December auction.
PJM market monitor warns of $5 to 10B extra data-center costs
Bloomberg · Thu, Nov 13, 2026
Monitoring Analytics said PJM’s data-center load forecasts will add $5 billion to $10 billion in capacity costs to the upcoming December auction for the 2029/30 delivery year. The watchdog previously attributed $29.4 billion in irreversible costs to data centers across the prior four auctions, warning households face higher bills without reforms. Read →
ERCOT targets Dec. 10 finish for data-center audit
Utility Dive · Thu, Nov 13, 2026
ERCOT plans to finish auditing hundreds of data-center proposals by Dec. 10 to resume interconnections after Gov. Abbott’s directive. The 474 GW large-load queue, 90% data centers, exceeds five times the grid’s record peak; the audit aims to weed out speculative requests before Batch Zero studies advance. Read →
Check out Power 101.
| Coal | Commodities 101 |
What's moving · China port thermal coal prices flatten at 1,025 yuan/t amid rising stocks and weak demand.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| API2 Rotterdam $/t |
136.40 | -0.7% -1.00 |
+40.0% | +42.1% | -2.9% |
| Newcastle $/t |
146.75 | +0.2% +0.25 |
+38.8% | +32.2% | -3.5% |
China port thermal coal flattens as stocks build, sentiment sours
Sxcoal · Fri, Nov 13, 2026
Northern China port thermal coal weakened Nov 12 with scant inquiries and traders trimming offers; CCI 5500 held flat at 1,025 yuan/t FOB VAT as combined stocks at four ports rose 0.40% DoD to 26.41 Mt. High-CV scarcity limits any fall while weak utility burn caps rebounds. Warmer weather and ample contract coal delay restocking, leaving prices dependent on the next cold front. Read →
Indonesia raises coal benchmark prices for second half of November
Reuters · Sat, Nov 14, 2026
Indonesia raised its coal benchmark prices (HBA) for the second half of November. The move follows government efforts to regulate production via quotas and raise the price index after earlier rules went unobserved, with 2026 output now seen at 720 Mt above the initial 600 Mt quota but below 2025 levels. Read →
Check out Commodities 101: coal section.
| Agriculture | Commodities 101 |
What's moving · USDA November WASDE cuts U.S. corn yield 1.6 bushels/acre and ending stocks while raising soybean exports 25 million bushels, lifting prices.
| Futures | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Corn Dec 2026 |
446 | +0.7% +3 |
+1.2% | +2.5% | -22.7% |
| Wheat Dec 2026 |
593 | +1.5% +9 |
+17.0% | +9.0% | -28.2% |
| Soybeans Jan 2027 |
1,232 | +1.0% +13 |
+19.5% | +6.4% | -2.0% |
| Sugar Mar 2027 |
18.40 | -0.1% -0.01 |
+22.6% | +24.3% | -6.8% |
| Coffee Dec 2026 |
279.3 | +0.2% +0.6 |
-19.9% | -30.6% | +25.4% |
| Cocoa Dec 2026 |
5,123 | +0.1% +4 |
-15.5% | -2.7% | +108% |
| Cotton Dec 2026 |
78.68 | -0.1% -0.10 |
+23.0% | +26.7% | -32.8% |
USDA cuts corn crop, lifts soybean exports in November WASDE
Kylene Scott · High Plains Journal · Thu, Nov 13, 2026
USDA trimmed 2026/27 U.S. corn production 141 million bushels to 15.9 billion on a 1.6-bushel yield drop to 179.6 per acre, cutting feed use and exports 25 million bushels each and ending stocks 91 million bushels to 1.758 billion. Soybean production rose 12 million bushels to 4.574 billion on higher yields in key states, with exports lifted 25 million bushels to 1.72 billion, trimming ending stocks 15 million bushels to 300 million. The report also lowered U.S. cotton output 267,000 bales and adjusted wheat and sugar balances. Read →
Arabica coffee falls to six-week low as cocoa, sugar rebound
Business Recorder / Reuters · Wed, Nov 12, 2026
Arabica futures fell 1.2% to $2.6270 per lb, hitting a six-week low of $2.6215 on improved Brazilian supply prospects and favorable 2027/28 crop conditions. Cocoa rebounded 2.9% in London to £3,875 per ton and sugar rose 1.1% to 18.29 cents per lb after hitting four- and five-week lows, supported by El Niño risks for Ivory Coast cocoa and shifting energy-price incentives for sugar production. Read →
Check out Commodities 101: agriculture section.
| Fertilizers | Commodities 101 |
What's moving · Strait of Hormuz disruption and elevated natural gas costs tighten ammonia and sulfur supply, lifting ammonia prices while urea softens on weak demand.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Urea | |||||
| China (ZCE) CNY/t |
1,747 | +0.1% +1 |
-0.1% | +5.4% | -22.8% |
| Brazil CFR $/t |
468.50 | +0.9% +4.00 |
+15.0% | +13.7% | -45.8% |
| US Gulf FOB $/st |
422.25 | -0.7% -3.00 |
+9.2% | +8.8% | -46.0% |
| DAP | |||||
| NOLA FOB $/st |
790.00 | +0.0% +0.00 |
+26.4% | +6.5% | +9.3% |
The 5Y column starts from the October 2021 peak, when the European gas crisis shut ammonia plants and China halted urea exports. Daily settles; these contracts barely trade, so flat days are common.
Nutrien advances $500M, $1B potash export terminal at Longview Port
Brian Cook · Hoodline / The Daily News · Thu, Nov 13, 2026
The Port of Longview and Nutrien reached tentative lease and development agreements for a potash export terminal at Berth 4 capable of storing 200,000 metric tons and handling 5, 8 million metric tons annually for Indo-Pacific markets. The non-binding deal includes up to 105 acres under a 50-year lease with Nutrien funding $500 million to $1 billion in construction; final investment decision is slated for 2028 and operations potentially by 2032. The project adds Pacific export capacity from Saskatchewan mines amid ongoing global potash supply dynamics. Read →
Maaden ships opportunistic ammonia cargoes to India despite Hormuz limits
Argus Media · Mon, Nov 9, 2026
Maaden idled two 1.1 million t/yr ammonia units at Ras al-Khair in March due to Hormuz closure but has exported over 70,000 t since October in three shipments to India, with another 25,500 t loading, as inventory management. CEO Bob Wilt said full resumption awaits clear shipping routes; the company withdrew 2026 ammonia production guidance while one unit continues for captive phosphate use. UKMTO reported 11 vessel attacks in the week to Nov 4, including eight in the strait, keeping exports opportunistic. Read →
Check out Commodities 101: fertilizer section.
| Base Metals | Commodities 101 |
What's moving · Copper tumbles toward fifth straight weekly loss on AI rout and US rate-hike bets, LME three-month below $13,500/t.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Copper NY $/mt |
13,426 | -1.7% -234 |
+8.2% | +21.8% | +38.2% |
| Copper SHFE $/mt |
14,372 | +0.5% +73 |
+13.2% | +32.9% | +47.2% |
| Aluminium SHFE $/mt |
3,050 | -0.1% -3 |
+2.5% | +14.3% | +9.7% |
| Zinc SHFE $/mt |
3,349 | -0.5% -16 |
+11.5% | +20.0% | +0.3% |
| Nickel SHFE $/mt |
16,206 | -0.1% -21 |
-4.3% | +8.1% | -19.2% |
| Lead SHFE $/mt |
2,108 | +0.0% +1 |
-4.3% | -2.4% | -3.2% |
| Tin SHFE $/mt |
47,533 | +1.3% +630 |
+13.2% | +34.1% | +21.0% |
Copper drops to three-month low on weak demand and US rate expectations
Pratima Desai · Reuters · Thu, Nov 13, 2026
LME three-month copper fell 1.2% to $13,645/t, touching an intraday low of $13,629, the weakest since July 29, before a modest recovery. Analysts cited soft industrial demand, AI stock weakness pressuring the metal's data-center outlook, and a stronger dollar from hotter US inflation data and Fed hawkish comments. Aluminium cash-to-three-month backwardation hit a 36-year high above $175/t on record-low LME stocks. Read →
LME aluminium backwardation hits 36-year high on tight stocks
Mining.com.au / Reuters data · Thu, Nov 13, 2026
The LME cash-to-three-month aluminium spread surged to $176.80/t on November 12, its highest since November 1990, as available warehouse stocks fell to 226,350 t, the lowest since 1990 and down over 50% year-to-date. Nearly all remaining metal is Russian-origin, with one holder controlling a large share of warrants, tightening near-term supply amid Middle East shipment disruptions. Three-month aluminium prices fell around 1.4% to near $3,030/t despite the squeeze. Read →
LME base metals mostly higher on China NEV data, easing tensions
Argus Media · Wed, Nov 12, 2026
LME three-month nickel rose 0.40% to $16,140/t while copper edged down 0.25% to $13,795/t in official trading. Aluminium gained 1.22% to $3,064/t and tin rose 1.26% to $46,900/t. Support came from resilient Chinese new-energy vehicle production, October output up 14% year-on-year to 2.02 million units, and easing geopolitical tensions, though US warehouse copper accumulation continued. Read →
Check out Commodities 101: base metals section.
| Iron Ore & Steel | Commodities 101 |
What's moving · DCE iron ore I2701 closed at 669.5 yuan/t Friday as port stocks hit 152Mt amid rising steel export orders.
| Market | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Iron Ore 62% DCE $/dmt |
88.8 | -0.3% -0.2 |
-11.8% | -9.5% | +2.4% |
| Rebar SHFE $/mt |
398 | -0.0% -0 |
+1.0% | +3.7% | -37.3% |
| HRC SHFE $/mt |
413 | -0.4% -2 |
+0.3% | +0.8% | -39.3% |
Steel export orders rise fourth straight month
Shanghai Metals Market (SMM) · Fri, Nov 13, 2026
October steel export orders reached 3.3742Mt, up 3.62% MoM and the fourth consecutive rise; long-steel orders jumped 10.83% to 1.79Mt. DCE I2701 closed at 669.5 yuan/t (down 0.52%) while 35-port stocks built 2.99Mt WoW to 152.12Mt. Rising exports and coke price cuts ease mill costs and may slow iron-ore declines short-term. Read →
Baowu completes Simandou North full chain
IndexBox · Thu, Nov 13, 2026
China Baowu said the northern Simandou block (Blocks 1 to 2, 1.54Bt resources at 65.28% Fe) reached full mine-rail-port operation with both 30Mtpa lines live, shifting the $20bn project from construction to production. Guinea supply diversifies China’s imports away from Australia/Brazil dominance. High-grade ore will support low-carbon steelmaking. Read →
DCE iron ore futures close lower Friday
Bastille Post · Fri, Nov 13, 2026
DCE most-active January 2027 iron ore contract fell 0.52% to 669.5 yuan/t ($99.70/t). SGX near-month settled near $91.35/t. Weak hot-metal output, environmental curbs in Hebei and building port stocks (152Mt+) capped gains despite export-order support. Read →
Check out Commodities 101: steel section.
| Precious Metals | Commodities 101 |
What's moving · Gold steadies near $3,880 after weekly 4.5% drop as Fed December hike odds hold near 91%.
| Futures | Last | 1D | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Gold Dec 2026 |
3,886 | +0.0% +1 |
-10.5% | -4.6% | +108% |
| Silver Dec 2026 |
49.12 | -1.9% -0.94 |
-30.0% | -3.0% | +95.6% |
| Platinum Jan 2027 |
1,490 | -2.0% -31 |
-25.3% | -1.6% | +38.7% |
| Palladium Dec 2026 |
1,008 | +1.6% +16 |
-39.1% | -29.9% | -53.9% |
Gold, silver futures post weekly losses amid rate fears.
Anthony Harrup · Wall Street Journal · Fri, Nov 13, 2026
Comex gold settled up $1.30 at $3,879.70/oz for a 4.55% weekly loss; silver fell 1.9% to $49.031/oz, its lowest close in a year and down 5.4% on the week. A below-estimate PPI and steadying oil eased some inflation concerns but did not dent December rate-hike expectations, with higher yields and a stronger dollar weighing on the metals. Read →
Gold holds near one-year low as rate-hike bets rise.
Bloomberg · Fri, Nov 13, 2026
Gold advanced modestly on dip-buying after Thursday's tumble to a 13-month low near $3,871 but steadied just below $3,890/oz. Surging Treasury yields and persistent Fed tightening bets from hot inflation data kept pressure on bullion despite long-term buyers stepping in. Read →
Check out Commodities 101: gold section.
| Rare Earths & Critical Minerals | Commodities 101 |
What's moving · China extends rare-earth export-control suspension to Jan 10, 2027, keeping heavy-element licenses in force and dysprosium at $4,100/kg ex-China.
China extends rare-earth export pause to Jan 10, 2027
Reuters · Mon, Nov 9, 6:13 AM ET
China’s Ministry of Commerce announced on Nov 9 a two-month extension of the suspension on October 2025 export controls covering rare earths, lithium batteries and synthetic graphite anode material, running through Jan 10, 2027. The move formalizes a bilateral truce with the US ahead of a planned Trump-Xi meeting and preserves the existing April 2025 licensing regime for seven medium and heavy rare earths including dysprosium, terbium and yttrium. Non-Chinese producers such as Lynas retain a pricing premium in overseas markets while the core supply constraint remains unchanged. Read →
Lynas benefits as China keeps heavy rare-earth curbs
AD HOC NEWS · Fri, Nov 13, 3:21 PM ET
China’s Nov 9 extension keeps the April 2025 licenses on samarium, gadolinium, terbium, dysprosium, lutetium, scandium and yttrium in force through at least Jan 10, 2027. Lynas reported 23 tonnes of dysprosium and terbium output in the September quarter at an average selling price of A$102.1/kg, with dysprosium oxide assessed at $4,100/kg in North America on Oct 30. Planned maintenance shutdowns at its Malaysian and Australian facilities will test stockpiles in the December quarter while ex-China prices stay elevated. Read →
MP Materials rises on $3.35M insider buying
MarketBeat · Fri, Nov 13, 12:00 AM ET
MP Materials shares gained 3.3% to $38.70 on Nov 13 after insiders bought more than $3.35 million in stock, including purchases by the CFO, a director and the COO. The company’s Q3 revenue rose 176% year-over-year to $147.7 million on higher NdPr volumes and pricing plus initial heavy-rare-earth sales, beating estimates. The moves occur against the backdrop of the China export-control extension and MP’s progress toward domestic magnet production. Read →
Check out Commodities 101: rare earths section.
| Shipping & Freight | Commodities 101 |
What's moving · Tanker rates correct sharply as VLCC earnings drop 31% weekly amid improving vessel availability and fading Atlantic demand.
| Route | $/day | Wk | 1Y | $/t | $/bbl |
|---|---|---|---|---|---|
| VLCC TD3C MEG to China |
$1.37M | -3.0% | +1180% | 227.2 | 31.00 |
| Suezmax TD20 WAF to UKC |
$239k | -42.8% | +198% | 71.4 | 9.74 |
| Aframax TD25 USG to UKC |
$116k | -49.6% | +85.9% | 73.8 | 10.07 |
| LR2 TC1 MEG to Japan |
$308k | +1.4% | +879% | 200.7 | 26.94 |
| LR1 TC5 MEG to Japan |
$227k | +1.9% | +857% | 212.6 | 23.89 |
| MR TC18 USG to Brazil |
$71k | -16.5% | +241% | 97.8 | 11.51 |
| MR TC7 Singapore to Aus |
$72k | -5.0% | +242% | 98.8 | 13.26 |
Report of Nov 5, 2026. Weekly round-voyage TCE and freight cost per tonne and per barrel; TD routes carry crude, TC routes refined products. 1Y is the $/day change; the WetBarrels.com history starts in October 2023, so there is no 5Y. Source: WetBarrels.com.
VLCC spot rates fall 31% weekly as attacks escalate in Hormuz.
Walter (宏利) · Xinde Marine News · Thu, Nov 13, 2026
Iran claimed four oil tankers hit by explosions in the Strait of Hormuz on November 12. VLCC spot earnings fell 31% over the past week to around $531,000 per day, with fixtures by Vitol and Unipec at two-month lows. The correction follows October peaks above $1 million daily despite persistent Gulf risks. Read →
Aframax tanker Affinity V grounds in Suez, blocking traffic for hours.
The Maritime Executive · Thu, Nov 13, 2026
The 114,600 dwt Singapore-flagged Affinity V lost steering southbound and wedged across the channel south of Little Bitter Lake. Five tugs refloated it after nearly five hours; six vessels were delayed. The incident occurred in the single-lane section near the Ever Given site. Read →
Container spot rates ease as blank sailings increase post-peak.
The Loadstar · Thu, Nov 13, 2026
Drewry’s World Container Index showed Shanghai-Rotterdam rates down 3% to $3,504 per 40ft and Shanghai-Los Angeles down 2% to $7,416 per 40ft. Eight blank sailings are scheduled next week versus five this week as post-peak demand softens. Carriers plan modest FAK hikes amid softening spot markets. Read →
Check out Commodities 101: shipping section.
| Environment | Commodities 101 |
What's moving · EUAs drop nearly €2.50 on spec selling after EU agrees 120M extra free allowances to 2030.
EU adds 120M free ETS allowances for fallback industries
Carbon Pulse · Fri, Nov 13, 2026
EU Parliament and Council agreed late Thursday to allocate over 120 million additional free EU ETS allowances to energy-intensive industries under fallback benchmarks from 2026 to 2030. The deal increases free allocation to protect competitiveness and curb carbon leakage risk. Extra supply weighs on EUA prices, triggering Friday's sharp selloff. Read →
EUAs plunge €2.50 on extra free allowances supply
Alessandro Vitelli · Carbon Pulse · Fri, Nov 13, 2026
EUAs fell more than €2 amid heavy speculative and algorithmic selling after Thursday's agreement to issue up to 120 million extra free permits by 2030. Gas and power markets also sold off, amplifying the risk-off move. The drop erased two days of prior gains and reflects immediate market digestion of higher near-term supply. Read →
CA, WA, Québec sign carbon market linkage deal
Environmental Defense Fund · Thu, Nov 12, 2026
California, Washington and Québec signed an agreement to link their cap-and-invest programs into a unified carbon market. The linkage is expected to launch in 2027 after final rulemaking. A larger combined market should boost liquidity, price discovery and clean-energy investment across the three jurisdictions. Read →
Check out Commodities 101: carbon section.
Real-World Assets & On-Chain Commodities
What's moving · Tether Gold pushes to rival gold ETFs with instant blockchain settlement and fresh KPMG audit amid rising tokenized commodity demand.
Tether Gold targets gold ETF dominance with blockchain speed and audit
Neils Christensen · Kitco News · Fri, Nov 13, 9:41 PM ET
Tether CEO Paolo Ardoino stated XAUT aims to become the first true competitor to gold ETFs by offering instant settlement, lower custody costs, and blockchain transparency. KPMG completed an independent audit of XAUT's 2025 reserves, physically inspecting bars, bolstering credibility for the $2.4B tokenized gold token. The World Gold Council estimates tokenization could unlock $700B in new demand, highlighting tokenized gold's edge in utility over traditional ETFs. Read →
Nasdaq tokenization pilot starts Dec. 6 with extended trading hours
TheStreet · Thu, Nov 13
Nasdaq CEO Adena Friedman announced the SEC-approved tokenized securities pilot and nearly 23-hour trading day begins Dec. 6, 2026, covering Russell 1000 stocks and S&P 500/Nasdaq-100 ETFs with tokenized and traditional shares on the same order book. The move tests blockchain-based settlement to free trillions in trapped capital and expands access beyond standard hours. It positions Nasdaq in the growing tokenized equities and RWA infrastructure push alongside DTCC and other players. Read →
Industry News
Corporate & Deals
What's moving · Freeport-McMoRan’s $110M BC copper stake purchase and ADNOC Gas/Venture Global Q3 earnings rebounds drive commodity corporate news.
Freeport buys 51% of Aurora West copper-gold project in BC for C$110M.
Northern Miner Staff · The Northern Miner · Thu, Nov 13, 2026
Freeport-McMoRan agreed to pay C$110 million (US$77.2 million) for a 51% interest in TDG Gold’s Aurora West project in British Columbia, with options to increase its stake by funding up to C$80 million in exploration and an additional C$40 million payment. The deal advances Freeport’s consolidation around the neighboring Aurora copper-gold discovery in the Toodoggone district and includes commitments to spend at least C$30 million on exploration within three years. It gives Freeport new exploration exposure in a key copper-growth region amid strong global demand for the metal. Read →
ADNOC Gas doubles Q3 net income to $1.34B and raises full-year guidance.
Newswire.ca / ADNOC Gas · Tue, Nov 10, 2026
ADNOC Gas reported Q3 2026 net income of $1.34 billion, up 101% quarter-on-quarter from $665 million, with EBITDA rising 70% to $2.03 billion on stronger domestic gas sales, international product sales and sulfur performance. The company approved a $940 million quarterly dividend (up 5% year-on-year) and raised full-year 2026 net income guidance to at least $4 billion despite ongoing Strait of Hormuz disruptions. Domestic UAE sales rose 20% QoQ while the firm continues major growth projects including Ruwais LNG and Rich Gas Development. Read →
Venture Global posts record Q3 with $2.5B net income and raises 2026 EBITDA guid
Venture Global · Tue, Nov 10, 2026
Venture Global reported Q3 revenue of $4.8 billion (up 43% YoY), net income of $2.5 billion (up 493% YoY) and consolidated adjusted EBITDA of $2.6 billion (up 69% YoY) on higher LNG volumes and prices, with 124 cargos exported. The company commenced commercial operations at Plaquemines Phase 1 on October 31 and raised full-year 2026 consolidated adjusted EBITDA guidance to $10.0, 10.3 billion while tightening its cargo range upward. It also executed new long-term offtake agreements and frame agreements for power islands to support potential AI data-center infrastructure. Read →
Brookfield-CPPIB advances in Uniper sale; Equinor also progresses.
Christoph Steitz · Reuters · Thu, Nov 13, 2026
A Brookfield and Canada Pension Plan Investment Board consortium advanced to the next stage of bidding for Germany’s state-owned utility Uniper, alongside Equinor; a KKR-RWE consortium and EPH did not. The German government seeks to reduce its near-99% stake to a blocking minority via sale or re-IPO, potentially valuing Uniper at up to €14 billion. The process follows Uniper’s 2022 government bailout after Gazprom supply cuts. Read →
Lucara raises 2026 revenue guidance after strong Q3 diamond sales.
CNW Group / Lucara Diamond Corp. · Thu, Nov 13, 2026
Lucara Diamond Corp. reported Q3 revenue of $61.1 million (up from $51.2 million a year earlier) from the sale of 113,227 carats, including a large Type IIa diamond, with adjusted operating earnings of $32.8 million. The company raised its full-year 2026 revenue guidance to $140, 160 million from the prior $100, 130 million range, citing contributions from recent high-value diamond recoveries at its Karowe mine. Operations processed 829,822 tonnes of ore at an average grade of 11.3 carats per hundred tonnes. Read →
Regulation & Government
What's moving · Trump extends Jones Act waiver 90 days for oil, fertilizer, commodities to ease US fuel costs.
China, US discuss tariffs and farm trade ahead of Xi-Trump meeting
Reuters · Sat, Nov 14, 7:13 AM ET
China and the US held their first trade council meeting on Friday via video link, discussing tariff cuts, a proposed $30 billion reciprocal tariff reduction deal, and agricultural trade. The talks come days before an expected Xi-Trump meeting in Shenzhen. No agreements were announced, but both sides committed to ongoing dialogue on trade issues including US farm goods. Read →
Trump extends Jones Act waiver 90 days for oil and fertilizer
Bloomberg · Fri, Nov 13, 12:47 PM ET
President Trump will extend by 90 days a waiver allowing foreign-flagged ships to carry oil, fertilizer and other commodities between US ports under the Jones Act. The extension takes effect Nov 16 and aims to lower fuel costs amid disruptions from the Iran conflict. It continues the longest waiver in the law's history, with case-by-case reviews required for voyages. Read →
US extends Jones Act waiver 90 days for oil and commodities
Reuters · Fri, Nov 13, 7:08 PM ET
President Trump extended a Jones Act waiver for 90 days to permit foreign-flagged vessels to transport oil and commodities between US ports. The move seeks to ease shipping bottlenecks and contain gasoline, diesel and fertilizer prices elevated by the Iran war. Since March, the waivers have enabled an extra 90 million barrels of petroleum products to move domestically. Read →
What traders and commodity market feeds are talking about
Norway court says emissions from exported oil must be considered
X / multiple traders · Sat, Nov 14
Traders on X are discussing a landmark Norwegian Supreme Court decision requiring the government to account for emissions from burning oil abroad when approving projects. The ruling is seen as likely to complicate or delay new oilfield developments, with implications for European supply and global oil markets. Read →
Alberta finance minister sees quick oil sands capex boost
X / multiple traders · Sat, Nov 14
Multiple traders highlight Alberta's new royalty regime changes, with the finance minister stating investment in oil sands is expected 'immediately.' Discussions focus on how the policy shift could accelerate Canadian heavy crude supply and impact WTI-WCS spreads. Read →
China oil product demand down 100 kb/d in recent figures
X / multiple traders · Sat, Nov 14
Oil traders note fresh JODI data showing a 100 kb/d drop in Chinese product demand. The figure adds to concerns about slowing Asian consumption amid broader commodity price weakness and supports bearish views on near-term crude balances. Read →
Ukraine targets Russian oil infrastructure again
X / multiple traders · Fri, Nov 13
Discussions across energy accounts track ongoing Ukrainian strikes on Russian refining capacity, with the latest hitting a ninth facility this month. Traders debate supply disruption risks, diesel export shifts from Russia, and potential price support for European products. Read →
White House extends Jones Act waiver another 90 days
X / multiple traders · Sat, Nov 14
Energy traders note the 90-day extension of the Jones Act waiver, which allows foreign vessels to move US energy cargoes. The move is viewed as supporting domestic logistics flexibility amid tight Jones Act tonnage and seasonal demand. Read →
Recent video and podcast calls from respected oil and commodity analysts
|

Book: Balanced oil market not optimal
Kevin Book, ClearView Energy Partners on CNBC Squawk Box · Fri, Nov 13
Balanced oil market is not an optimal market. Watch/Listen →
JPM: El Niño vs dunkelflaute on gas
Competing weather patterns affect natural gas. Watch/Listen →
S&P: Europe storage gap, Russian LNG exit
S&P Global Commodities Focus podcast · Wed, Nov 12
Europe storage below year-ago; preparing Russian LNG phaseout. Watch/Listen →
Where commodity traders watch asymmetric risk · live odds via Polymarket
Hormuz Crisis
US-Iran tensions disrupting Strait of Hormuz oil flows. Polymarket odds, last 7 days.
US announces the end of the Iran blockade by March 31, 2027
56%
-14pp w/w
Hormuz traffic returns to normal by December 31
6%
-4pp w/w
WTI tops its $147 record by March 31, 2027
14%
-6pp w/w
Source: Polymarket
Russia / Ukraine Energy
A ceasefire agreement would open the way to sanctions relief on Russian crude, diesel and pipeline gas, bearish for Brent, European diesel cracks and TTF. Polymarket odds, last 7 days.
Russia-Ukraine ceasefire agreement by March 31, 2027
36%
+1pp w/w
Source: Polymarket
Red Sea / Bab el-Mandeb
Houthi threat to Red Sea shipping; a closure reroutes tankers and LNG around the Cape. Polymarket odds, last 7 days.
Bab el-Mandeb effectively closed by December 31
8%
-2pp w/w
Source: Polymarket
Fed Policy
Fed rate decisions move USD strength and industrial energy demand expectations. Polymarket odds, last 7 days.
Fed hikes 25 bps at the December meeting
88%
+11pp w/w
US recession by end of 2027
28%
-3pp w/w
Source: Polymarket
Paid listings · list your event
Commodity & Energy Trading Week APAC · Mar 3-4 · Singapore
Commodity Trading Week Europe · May 19-20 · London
This week's biggest movers
Weekly changes based on settlements Friday, November 13, 2026
Charts: grey is the prior week, color is this week.
Dots under the energy markets and copper: the shape of the curve at Friday’s close. WTI, Brent and Nat Gas run cash to 1st to 2nd month, cash from WetBarrels.com; Dutch TTF and copper run their first three contracts.
| Market | Last | Weekly | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| Nat Gas contango |
3.230 | +7.7% +0.232 |
-12.4% | -25.9% | -35.6% |
| Dutch TTF backwardation |
90.95 | +6.3% +5.36 |
+223% | +189% | +13.8% |
| Soybeans |
1,232 | +3.6% +43 |
+19.5% | +6.4% | -2.0% |
| Corn |
446 | +0.9% +4 |
+1.2% | +2.5% | -22.7% |
| Wheat |
593 | +0.3% +2 |
+17.0% | +9.0% | -28.2% |
| Copper contango |
13,426 | -2.1% -282 |
+8.2% | +21.8% | +38.2% |
| WTI Crude backwardation |
88.56 | -2.5% -2.27 |
+54.2% | +47.8% | +9.5% |
| Brent backwardation |
95.84 | -2.5% -2.48 |
+57.5% | +49.3% | +16.8% |
| Gold |
3,886 | -4.6% -189 |
-10.5% | -4.6% | +108% |
| Silver |
49.12 | -5.2% -2.68 |
-30.0% | -3.0% | +95.6% |
Nat Gas led the week. Start with NatGas 101.
Macro this week
| Market | Last | Weekly | YTD | 1Y | 5Y |
|---|---|---|---|---|---|
| S&P 500 Fut |
7,583 | +2.4% +181 |
+10.0% | +13.3% | +62.1% |
| Dollar Index |
103.41 | +1.1% +1.11 |
+5.2% | +3.8% | +8.4% |
| EUR/USD |
1.1028 | -1.8% -0.0200 |
-6.1% | -5.1% | -3.6% |
| US 10Y Yield |
5.154 | +30bp | +99bp | +101bp | +353bp |
Tanker freight this week
| Route | $/day | Wk | 1Y | $/t | $/bbl |
|---|---|---|---|---|---|
| VLCC TD3C MEG to China |
$1.37M | -3.0% | +1180% | 227.2 | 31.00 |
| Suezmax TD20 WAF to UKC |
$239k | -42.8% | +198% | 71.4 | 9.74 |
| Aframax TD25 USG to UKC |
$116k | -49.6% | +85.9% | 73.8 | 10.07 |
| LR2 TC1 MEG to Japan |
$308k | +1.4% | +879% | 200.7 | 26.94 |
| LR1 TC5 MEG to Japan |
$227k | +1.9% | +857% | 212.6 | 23.89 |
| MR TC18 USG to Brazil |
$71k | -16.5% | +241% | 97.8 | 11.51 |
| MR TC7 Singapore to Aus |
$72k | -5.0% | +242% | 98.8 | 13.26 |
Report of Nov 5, 2026. Weekly round-voyage TCE and freight cost per tonne and per barrel; TD routes carry crude, TC routes refined products. 1Y is the $/day change; the WetBarrels.com history starts in October 2023, so there is no 5Y. Source: WetBarrels.com.
Forward curves
The heavy line: months 1 to 24 at Friday’s settlement Fri Nov 13. Amber: the same contracts a week earlier. Dotted: a month earlier. Dashed: months 1 to 24 as they stood a year earlier. Refinery cracks in $/bbl from the NYMEX curves.
WTI $/bbl
Backwardation. Front Dec 26 $88.56, down $2.27 on the week; Nov 28 $70.58. A year ago the front (Dec 25) was $60.09.
Brent $/bbl
Backwardation. Front Jan 27 $95.84, down $2.48 on the week; Dec 28 $74.56. A year ago the front (Jan 26) was $63.01.
3-2-1 crack $/bbl
Backwardation. Front Dec 26 $44.46, down $3.10 on the week; Nov 28 $28.12. A year ago the front (Dec 25) was $31.67.
Henry Hub $/MMBtu
Contango. Front Dec 26 $3.230, up $0.232 on the week; Nov 28 $3.665. A year ago the front (Dec 25) was $4.566.
The diesel and gasoline cracks, copper and propane: all eight curves.
The Week Ahead
Scheduled events next week that could move commodities.
Wed Nov 18 |
FOMC Minutes Oct 27 to 28 2:00pm ET
reveals Fed views on inflation path and rate outlook |
Fri Nov 20 |
monthly LPR or rate signal could affect CNY and demand outlook |
Commodity Research
The week's most interesting commodity research.
Commodities as 2027 portfolio hedge
Goldman · Nov 13 · Read →
Geopolitics and supply risks support positive commodity allocation for diversification and upside protection.
Copper mine supply tight, AI/electrification demand
Gold central bank buying, private recovery
Oil Brent $88/bbl 2027 avg, $130+ upside risk
Aluminium short vs copper on Indonesia supply
Oil market returns to surplus
IEA · Nov 13 · Read →
Global oil market swings to surplus in 4Q26 with larger build in 2027 as Gulf exports recover faster than demand.
Supply +2.3 mb/d Oct to 105.4 mb/d
Demand -2.7 mb/d 2026 to 102.3 mb/d
Stocks +52 mb Oct observed build
Prices Dated crude -32% from Oct high
Agri surplus of risks outlook
JPMorgan · Nov 6 · Read →
Agri risk premia eroded post-midterms; 2027 outlook shaped by politics, fundamentals and weather.
Fertiliser input costs elevated, demand weak
Grains volatility to rise off low levels
El Niño upside price risks ahead
Stocks-to-use near multi-year lows
China materials earnings forecasts
Goldman · Nov 9 · Read →
Copper top pick with raised price forecasts; steel profits cut on property slump.
Copper LME $15,600/t 2027, deficits widen
Steel profit forecasts lowered broadly
Aluminium neutral on supply growth
Coal neutral to sell ratings
BofA raises copper long-term forecast
BofA · Nov 6 · Read →
Long-term copper raised 20% to $12,000/t on persistent supply issues.
Supply ongoing constraints main driver
Aluminium 2027 forecast cut 5%
Gold bearish on higher rates, stronger USD
Risks energy demand shock or capex pause
Commodity Podcasts
Commodity sounds for your commute, run, walk or background.
|
MacroVoices #558 Mike Alkin: Uranium at a Crossroads
MacroVoices · Nov 12 · Listen →
Uranium structural deficit drives prices higher even as mining shares fall on AI capex slowdown fears
Bull case rests on reactor demand and rising production costs
Utilities must replenish depleted inventories
Not enough economically viable uranium for 440+ reactors plus pipeline
The Duration Trade: crude and products with Emily Kyne
HC Commodities · Nov 4 · Listen →
Middle East producers have positioned for a duration trade with oil likely oscillating $80-$100
Saudi flows near pre-war 7 mbpd via Red Sea workarounds
Freight adds $10 to 40/bbl to delivered costs
Europe missing 1.3 mbpd seaborne diesel; Q1 risk remains
No way out: Trapped European crude sinks differentials
Oil Markets (S&P Global Platts) · Nov 5 · Listen →
Ballooning European supply glut with elevated freight limiting refinery absorption
Refineries unable to take more feedstock
Freight economics block moves out of region
Market enters final stretch of 2026 with surplus pressure
An edgy winter for European gas
Energy Evolution (S&P Global Platts) · Nov 10 · Listen →
Prices at 2022 highs as low storage in Germany and Netherlands tightens balance
Loss of most Qatari LNG and upcoming EU Russian LNG ban
Storage levels below recent averages at winter start
Tight start raises risk of paying more or shortages
Oil to Remain at $100 Through 2027
Bloomberg Surveillance (Paul Sankey appearance) · Nov 3 · Listen →
Oil remains at $100 through 2027 amid ongoing risk premium
Geopolitical tensions sustain floor
Macro economy struggles above $100
Duration of conflict priced into back of curve
MacroVoices #557 Michael Every: The Blue Tsunami Lands on Markets... and Geopolitics
MacroVoices · Nov 5 · Listen →
Weaker inward-looking US creates power vacuums raising Middle East and Ukraine escalation risks
Tariffs as key reindustrialization tool
Foreign policy constraints from congressional shift
Power vacuums heighten global conflict odds
Was this forwarded to you? Subscribe free.
The cash price of physical crude globally, real‑time live even on weekends.
WetBarrels.com is Morgan’s service providing free real‑time cash prices for physical crude oil, refined products, freight, natural gas and more. See today’s prices.
Morgan Downey's Commodity News is published by Wooden Table Press LLC. Informational only, not financial or legal advice. Do your own research. No representation is made as to accuracy or completeness.
Unsubscribe · View in browser · Subscribe
One sponsor per issue. Ask us about a future month →
Unsubscribe · View in browser · Subscribe